70% LTV non-resident mortgage, Estepona
€1.6m purchase · 70% LTV · primary residence
In short
How was 70% LTV non-resident mortgage, Estepona financed?
Clifton International helped facilitate this Spanish non-resident mortgage through a specialist partner for an Estepona purchase — €1.6m purchase, 70% LTV, primary residence. A substantial Spanish mortgage facility at 70% LTV against a €1.6m Estepona property intended as the client's primary residence. Commercial terms and fees were negotiated through the specialist partner to reflect the client's requirements.
- Location: Estepona, Costa del Sol. Finance type: Spanish non-resident mortgage.
- Headline terms: €1.6m purchase · 70% LTV · primary residence.
- A UK tax-resident international professional was planning to relocate to Spain and buy a €1.6m primary residence in Estepona through a Spanish corporate entity that was still being established. The application also depended on a lender taking a fair view of substantial commission and bonus income alongside permanent base salary.
- The specialist Spanish mortgage partner secured the required financing after the lender reviewed the client's employment, affordability, assets, documentation and proposed ownership structure.
Financing something comparable? A specialist will review your scenario and revert within one working day.
Start an enquiry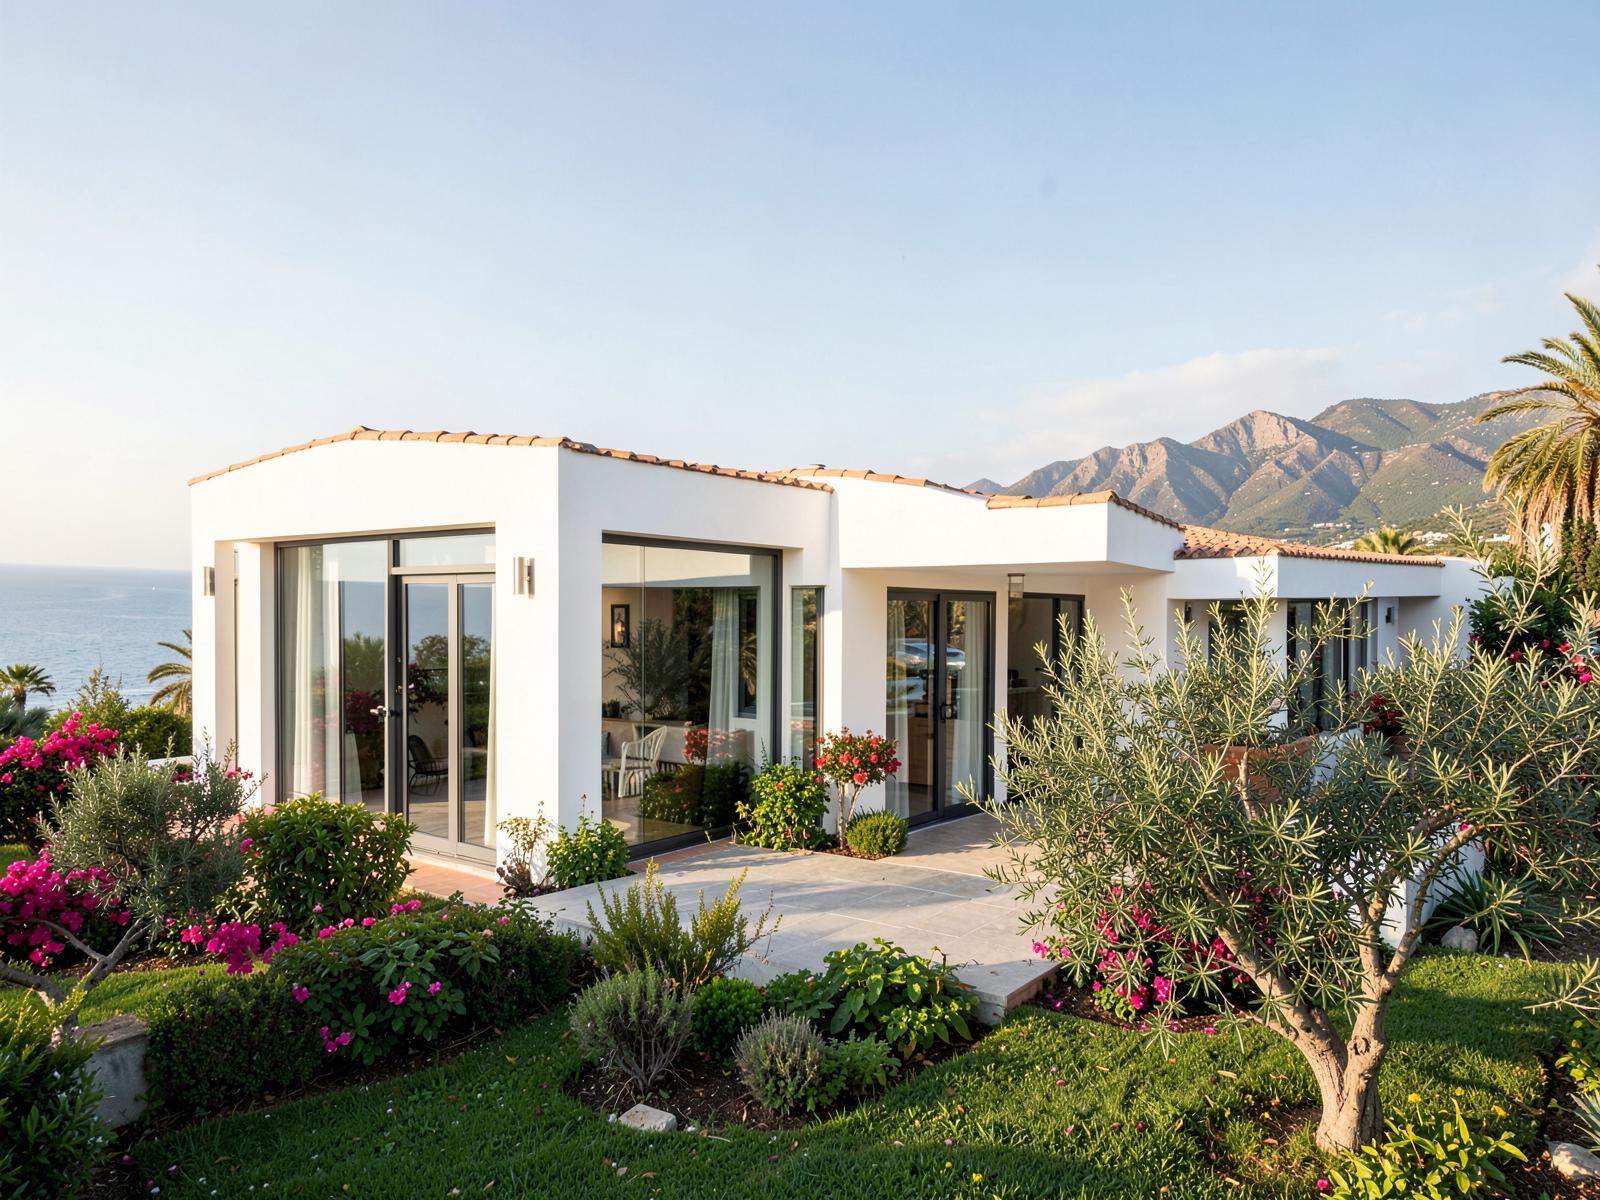
- Property value
- €1,600,000
- Loan to value
- 70%
- Client
- UK tax resident
- Purpose
- Primary residence
- Income
- Salary + variable pay
- Location
- Estepona, Costa del Sol
Spanish mortgage in Estepona, Málaga province
Estepona sits at the western end of the Costa del Sol, where a large share of purchases are made by buyers who are tax resident outside Spain — exactly the profile this non-resident mortgage was placed for.
- Challenge
- A UK tax-resident international professional was planning to relocate to Spain and buy a €1.6m primary residence in Estepona through a Spanish corporate entity that was still being established. The application also depended on a lender taking a fair view of substantial commission and bonus income alongside permanent base salary.
- Solution
- Clifton introduced the client to a specialist Spanish mortgage specialist with expertise in placing cases from non Spanish residents. The file clearly evidenced permanent international employment, remote working, variable remuneration history, liquid savings and investments, minimal existing debt, the planned relocation and proposed corporate purchase structure.
- Funding structure
- A substantial Spanish mortgage facility at 70% LTV against a €1.6m Estepona property intended as the client's primary residence. Commercial terms and fees were negotiated through the specialist partner to reflect the client's requirements.
- Outcome
- The specialist Spanish mortgage partner secured the required financing after the lender reviewed the client's employment, affordability, assets, documentation and proposed ownership structure.
Client profile
The client held a senior commercial role with an established international technology business and worked fully remotely, supporting the intended move from the UK to Spain.
- Full-time, permanent employment with an established history
- Strong base salary plus performance-related commission and bonus
- UK tax resident at application, with a clear intention to relocate
- Introduced by a professional property finance referral partner
Assets and affordability
Cash savings, a diversified investment portfolio and additional international savings evidenced the deposit contribution and capacity to maintain the mortgage. Low existing debt strengthened the application, while the main UK housing commitment was expected to cease after relocation.
- Sufficient liquid assets for the required contribution
- Diversified investments and internationally held savings
- Minimal existing debt commitments
- Affordability improved when evidenced variable remuneration was recognised
The key underwriting challenge
The central issue was how much commission and bonus income the lender could reasonably include. The specialist partner supported the remuneration structure with employment and financial evidence so the lender could assess recurring variable income in context rather than relying only on base salary.
Spanish mortgage for a UK resident planning to relocate
Although the property was intended to become the client’s primary residence, the application began while he remained UK tax resident. The lender therefore had to assess the case as a non-resident Spanish mortgage at application, taking account of UK employment, international assets and the proposed move. The remote working arrangement helped explain how the client intended to retain established earnings after relocating to Estepona.
Property and mortgage requirement
The agreed purchase price was €1.6m and the requested loan represented 70% of the property value. The home had already been secured through a formal reservation or contractual agreement, so the application needed to progress alongside the purchase timetable. The proposed Spanish corporate ownership structure was also still being arranged, making it important that the lender understood the intended borrower and ownership position from the outset.
Why the application succeeded
A strong underlying financial position was combined with a carefully documented application and close coordination between the client, referral partner, specialist mortgage broker and lender. The result illustrates how a non-resident Spanish mortgage application can be strengthened when variable pay, liquid assets, existing commitments and the future use of the property are presented as one coherent case rather than assessed in isolation.
- Stable permanent international employment and strong base income
- Documented commission and bonus history
- Substantial savings and investments with a strong deposit contribution
- Minimal existing debt and a credible relocation plan
- Formal commitment to the property purchase
- A lending strategy selected for an international borrower and corporate structure
Enquire about a similar transaction
Prefilled with the context of this case study. A specialist will respond within one working day.
- 40+ lendersWhole-of-market panel
- 4–8 weeksTypical completion
- Rated ExcellentClient reviews
- No obligationFree initial review
More case studies
Related transactions

Ready to explore your options?
Speak to a Spanish property finance specialist.
A discreet, no-obligation conversation with a UK & Spain-focused specialist who understands both the UK and Spanish lending landscape.