
Spanish Property Finance
Finance secured against Spanish property, arranged by international specialists.
Funding for purchases, development projects and refinancing across Spain — with access to specialist Spanish lenders offering up to 65% LTV.
Get indicative terms
Four quick questions. We pre-fill your enquiry so you're done in under a minute.
- 40+ lenders · Whole-of-market panel
- Rated Excellent · Client reviews
- No obligation · Free initial review
In short
How do international buyers finance property in Spain?
International buyers finance Spanish property in two main ways: a non-resident mortgage at typically 60–70% loan-to-value over five to twenty-five years, or short-term bridging at up to 65% of value when speed matters. Budget a further 10–12% of the price for taxes and costs.
- Mortgages take eight to fourteen weeks; bridging completes in two to six.
- Lending is assessed on documented worldwide income, in any major currency.
- An NIE number and Spanish bank account are required before completion.
- Many buyers bridge to complete, then refinance onto a term mortgage.
Three questions to the right finance route
Tell us what you are financing, where, and how quickly you need funds. We will point you to the right page and pre-fill your enquiry.
What are you financing?
Where in Spain?
Location shapes valuation timelines and which lenders will look at the asset.
How quickly?
Answer questions 1 and 3 to see a suggested route.
Who we help
Bridging, mortgages and development finance for Spanish property.
Short-term bridging is a core focus of our work — helping US, UAE, UK and European clients complete quickly on Spanish acquisitions where timing, chain breaks or below-market opportunities demand speed. Alongside bridging we can introduce you for Spanish property mortgages (start at the Spanish mortgage hub or the Spanish buyer journey), development finance in Spain, Spanish commercial property finance and refinancing a Spanish property.
Explore Spanish bridging financeBridging & Short-Term Finance
Fast-turnaround bridging to secure below-market-value purchases, unlock chains and complete on tight deadlines — typically funded in weeks, not months.
Residential Purchases
Primary residences and second homes across mainland Spain and the Islands.
Holiday Homes
Coastal and resort properties along the Costa del Sol, Ibiza, Mallorca and beyond.
Development Finance
Ground-up build, conversion and refurbishment funding for residential schemes.
Commercial Property
Offices, retail, hospitality and logistics assets across Spain's major cities.
Refinance & Exit Finance
Improved terms, cash-out refinance and exit refinance for maturing bridge and development facilities.
Bridging finance — use cases
Where Spanish bridging finance solves a problem.
Five common scenarios where short-term, asset-backed lending on Spanish real estate is the right tool — completed in weeks, not months.
Property Purchase
Time-critical acquisitions, auction, off-market and chain-break completions.
Explore BridgingDebt Cancellation
Refinance and clear existing debt against Spanish real estate before a term facility.
Explore BridgingBusiness Liquidity
Working capital for the company, secured against Spanish property assets.
Explore BridgingCash in Advance
Release liquidity while an asset is sold in an orderly manner.
Explore BridgingProfessional Investment
Capital to move on time-sensitive professional investment opportunities.
ExploreBridging & development — by location
Location-specific bridging and development finance.
Structured short-term and development facilities across Spain's most active markets — with local lender relationships and asset knowledge.
Development finance — stages
Staged funding for Spanish real estate developers.
Tranched facilities structured around land, construction milestones and commercialisation — for schemes across mainland Spain and the Islands.
Land Acquisition
Partial land funding on consented and pre-consented sites, rolling into senior debt on planning grant.
Explore DevelopmentGround-Up Development
Senior and stretch-senior facilities for new-build residential, mixed-use and hospitality schemes.
Explore DevelopmentAsset Rehabilitation
Refurbishment, conversion and repositioning finance for existing Spanish buildings.
Explore DevelopmentAdvanced-Stage
Finish-and-exit and sales-window facilities for schemes nearing practical completion.
ExploreWhy Clifton International
A boutique introduction service for cross-border property finance.
We combine international intermediary relationships with a specialist Spanish lender network built over years of high-value transactions. One point of contact, managing every element of a complex process.
International, English-speaking team
Deal with an experienced international specialist — not a call centre.
Specialist Spanish lender relationships
Introductions to intermediaries with relationships across banks and private lenders active in high-value cross-border lending.
Bespoke funding structures
Interest-only, capital repayment, multi-currency, portfolio and cross-collateralised structures.
One point of contact
Your dedicated point of contact manages the entire process — lender selection, valuation, notary and completion.
Experience with complex transactions
Development schemes, corporate structures, international tax considerations and trust ownership.
Selected case studies
Recent transactions
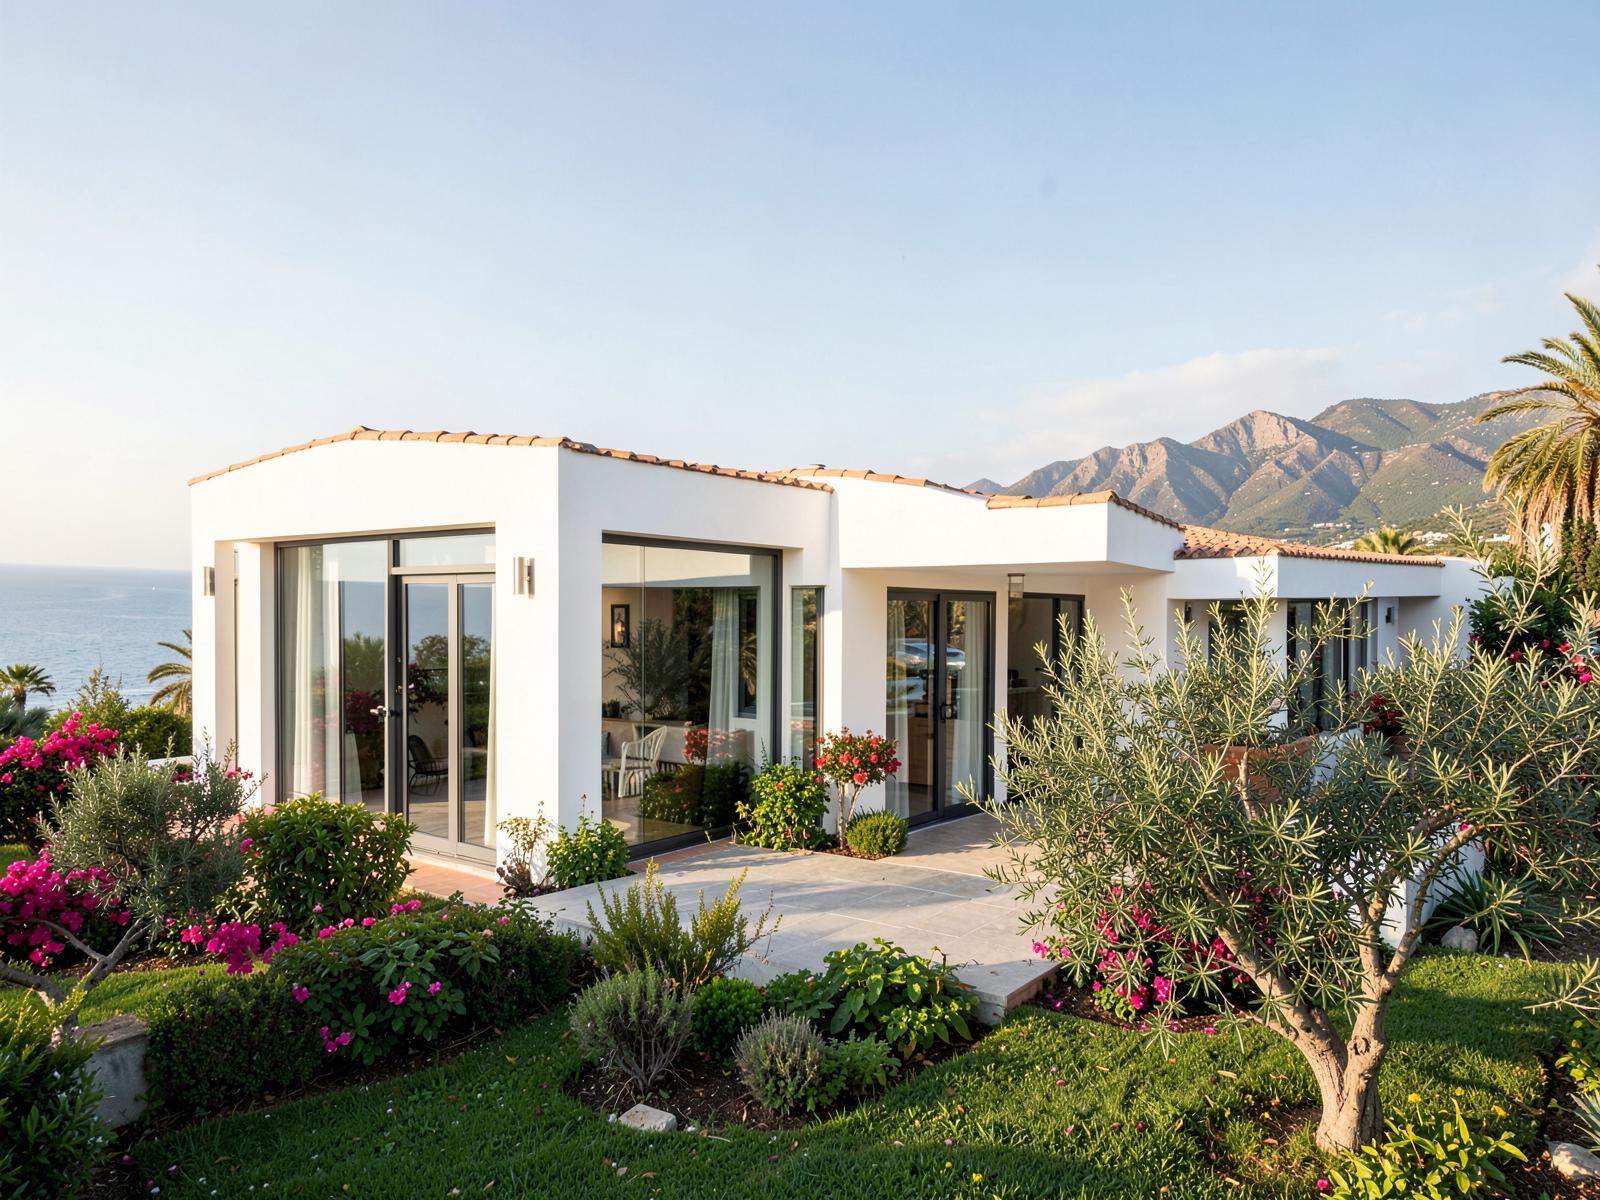
70% LTV non-resident mortgage, Estepona
A 70% LTV Spanish mortgage was secured through a specialist partner for a UK tax-resident international professional relocating to a €1.6m primary residence in Estepona.
€1.6m purchase · 70% LTV · primary residence
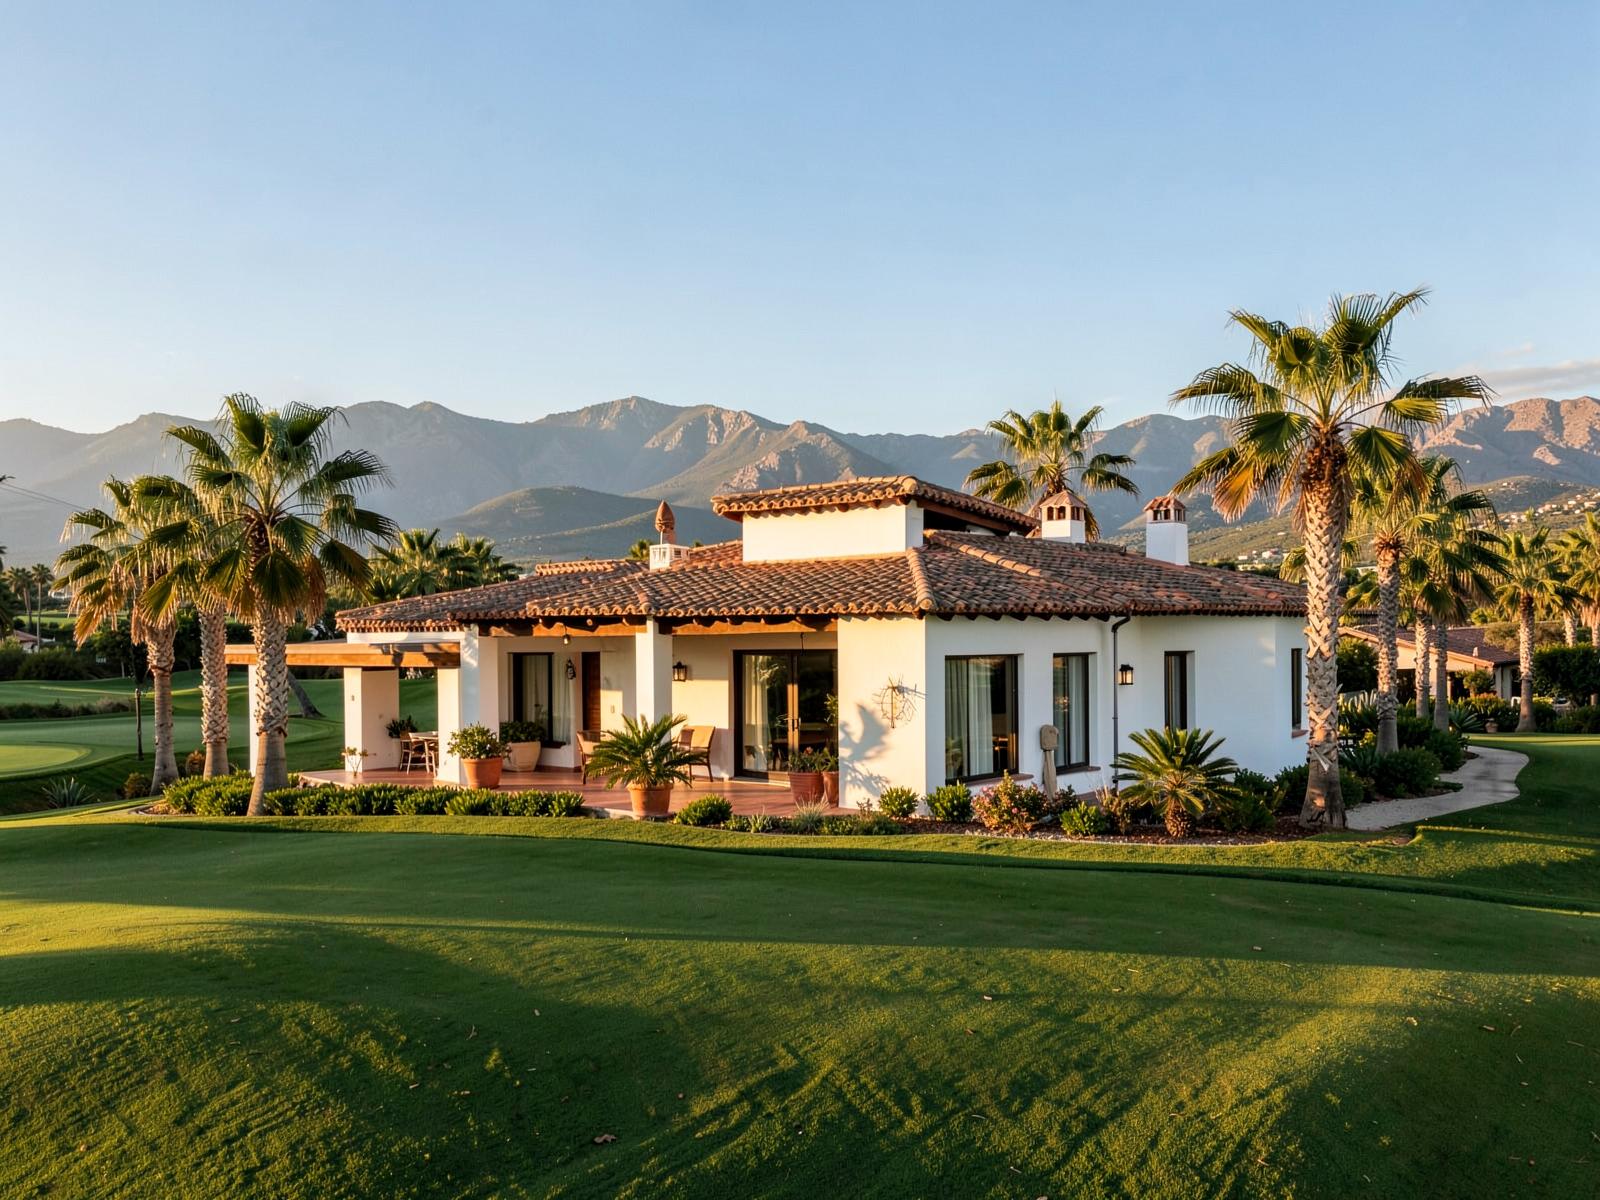
70% LTV holiday-home mortgage, Murcia
A 70% LTV Spanish mortgage was secured through a specialist partner for UK-resident joint applicants — one salaried, one long-established self-employed — buying a €750k holiday home on a Murcia golf resort.
€750k purchase · 70% LTV · holiday home
€1.5M villa refurb, Marbella
€3.24m interest-only facility for a UK technology entrepreneur acquiring a €5.4m front-line beach villa in Marbella — application to offer in 4 weeks.
€3.24m · 60% LTV · interest-only
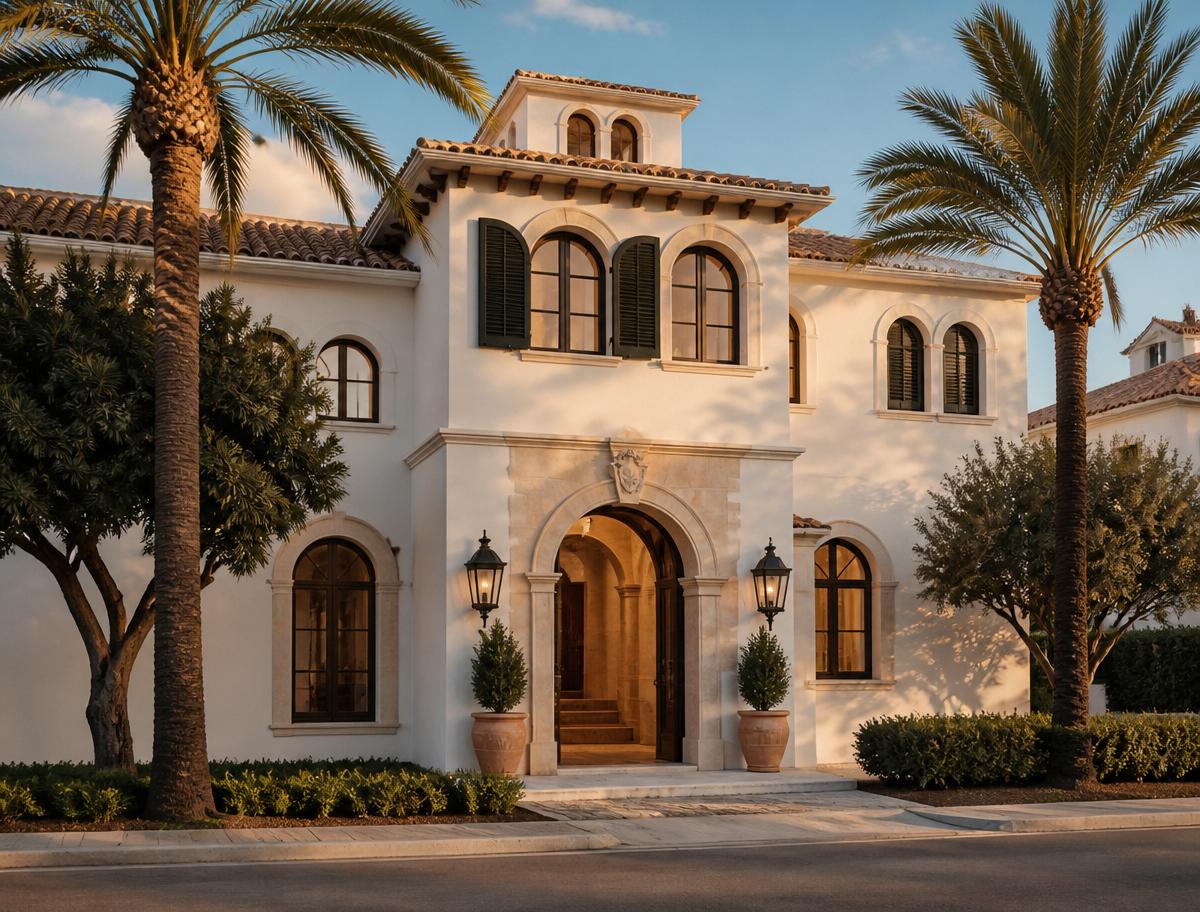
€4.5m developer loan, Santa Creu (Mallorca)
€4.5m developer loan at 43% LTV to complete a 6-unit residential building in a strategic Palma location. Funding delivered within 36 days.
€4.5m · 43% LTV · 36 days to funding
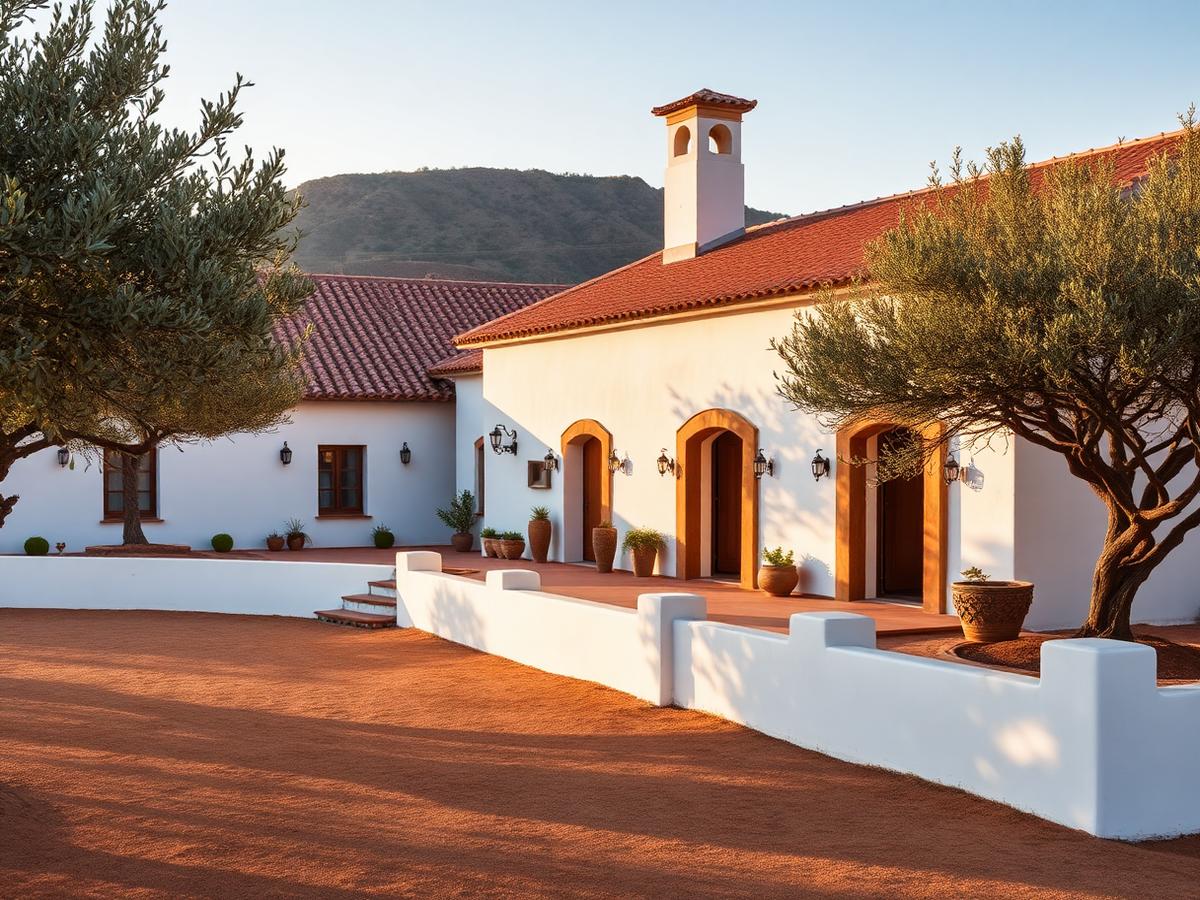
Refinance & equity release, Andalusian estate
€2.2m 15-year interest-only refinance of an unencumbered €4m Andalusian estate — releasing working capital for a UK business acquisition without disposing of the asset.
€2.2m · 55% LTV · 15-year interest-only
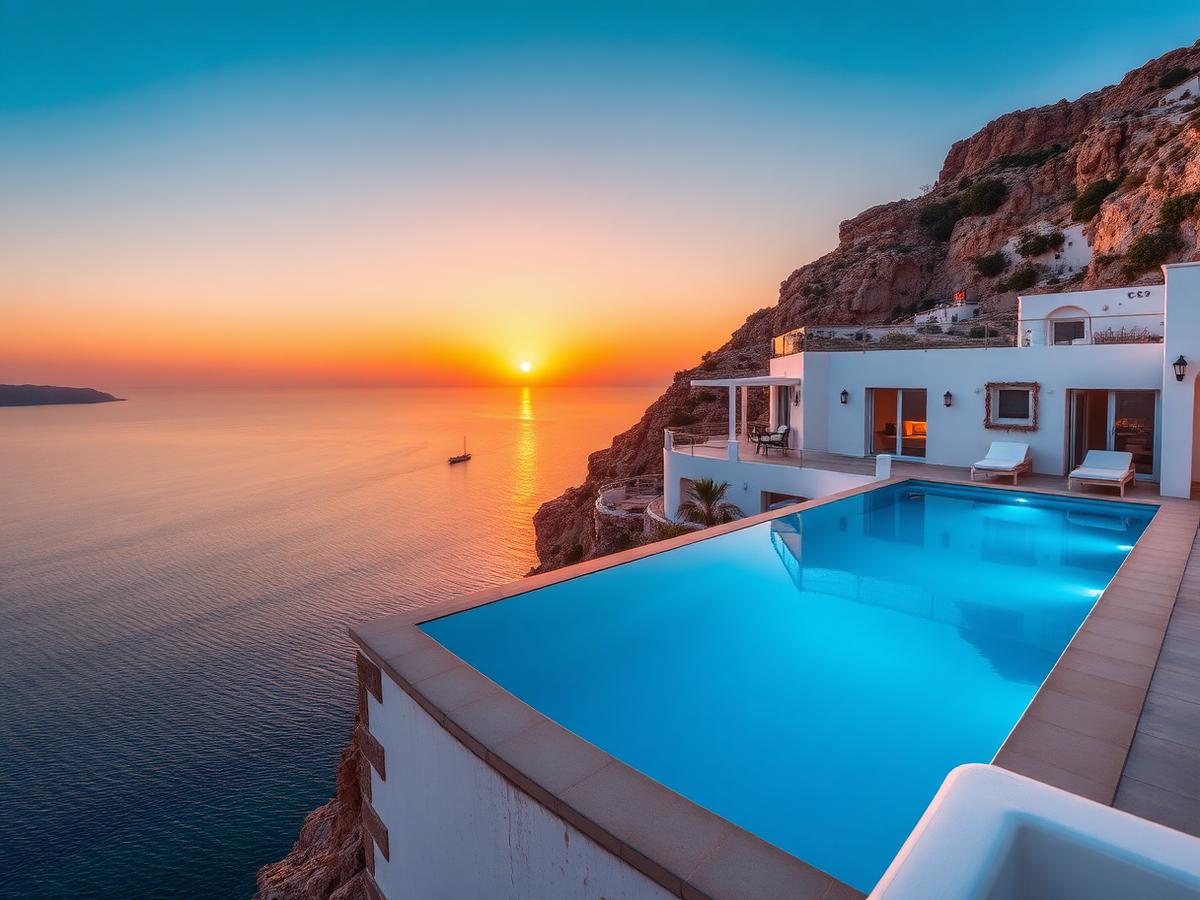
Luxury holiday home, Ibiza cliffside
€3.9m 20-year interest-only mortgage for a HNW UK client acquiring a €6.5m Ibiza cliffside villa — private bank comfortable with seasonal short-let income.
€3.9m · 60% LTV · 20-year interest-only
Browse every Spanish transaction
- 70% LTV non-resident mortgage, Estepona — Spanish non-resident mortgage, Estepona, Costa del Sol
- 70% LTV holiday-home mortgage, Murcia — Spanish non-resident mortgage, Murcia, Spain
- €1.5M villa refurb, Marbella — Spanish mortgage, Marbella, Costa del Sol
- €4.5m developer loan, Santa Creu (Mallorca) — Spanish development finance, Palma, Mallorca
- Refinance & equity release, Andalusian estate — Spanish refinance & equity release, Andalusia
- Luxury holiday home, Ibiza cliffside — Spanish holiday-home mortgage, Ibiza
- Development exit refinance, Costa Blanca — Spanish development exit bridge, Costa Blanca
- Below market value bridge purchase, Javea — Spanish bridging finance, Javea, Costa Blanca
- Complex re-bridge for Spanish villa in 6 working days — Regulated bridging finance, Spain / UK
- €3m villa capital raise, Ibiza — Spanish bridging finance, Ibiza
- €3.62m villa bridge, Benahavís — Spanish bridging finance, Benahavís, Costa del Sol
- €5.1m Madrid refinance and liquidity release — Spanish refinance & capital raise, Central Madrid
- €357,798 purchase-option mortgage, Jávea — Spanish private mortgage, Jávea, Costa Blanca
Our process
A clear, considered path to completion.
- 01
Initial assessment
A confidential conversation to understand your objectives, asset and profile.
- 02
Funding strategy
We prepare a bespoke funding strategy identifying suitable lenders and structures.
- 03
Introductions to lenders
We approach lenders directly on your behalf, negotiating indicative terms.
- 04
Offer & completion
We stay alongside you and your specialist partner through valuation, legal and notary process to funds released.
Frequently asked
Common questions from clients
A selection of questions we regularly answer. If yours isn't listed, please get in touch.
- How quickly can bridging finance in Spain complete?
- For well-prepared cases, bridging is typically arranged through our specialist partners in 3-6 weeks from instruction. Where the borrower profile, valuation and Spanish legal work can run in parallel, faster completions are achievable.
- When does bridging make sense over a Spanish mortgage?
- Bridging suits time-critical purchases: below-market-value opportunities, auction or off-market deals, chain-break scenarios, refurbishment before a mortgage refinance, and completing before a Spanish mortgage offer is in place.
- What LTV and exit is typical for a Spanish bridge?
- Bridging is typically arranged up to 60-65% LTV against Spanish real estate, with 6-24 month terms. Exit is normally via sale, refinance onto a Spanish mortgage, or repayment from other liquidity.
- Can non-residents (US, UAE, UK, European) get mortgages in Spain?
- Yes. Spanish and international lenders regularly lend to non-resident buyers from the US, UAE, UK, Europe and further afield, typically to a maximum of 65-70% LTV depending on borrower profile and asset.
- Do you arrange development finance in Spain?
- Yes. We introduce you to intermediaries who arrange senior development facilities for residential and mixed-use projects, structured against site value and GDV with staged drawdowns.
- Can you refinance an existing Spanish property or exit a bridge?
- Yes. We regularly refinance mortgaged and unencumbered properties, and structure term-mortgage exits for maturing bridge and development facilities.
- Do you lend directly?
- No. We do not lend, and we are not a Spanish mortgage adviser. We are a specialist introducer: we understand your requirement and introduce you to regulated third-party intermediaries in the UK and EU who arrange and advise on the finance with the lender.
Where we cover
16 covered locations across Spain
We facilitate non-resident mortgages and bridging finance across mainland Spain, the Balearics and the Canary Islands. Select a location to explore the local guide.
Success stories by region
- MadridCentral Spain
- BarcelonaCatalonia
- Girona / Costa BravaCatalonia
- ValenciaValencian Community
- Costa BlancaAlicante coast
- JáveaAlicante coast
- SevilleAndalucía (west)
- Málaga CityCosta del Sol
- Costa del SolAndalucía coast
- MarbellaCosta del Sol
- EsteponaCosta del Sol
- SotograndeCosta del Sol
- MallorcaBalearic Islands
- MenorcaBalearic Islands
- IbizaBalearic Islands
- Canary IslandsAtlantic
Buyer guides
Financing Spanish property from your country of residence
Non-resident lending in Spain varies materially by buyer origin — currency, EU/EEA status, tax reporting and documentation all affect LTVs and lender appetite. Pick your country of residence for a tailored guide.
American buyers
USD income, FATCA reporting and wire-transfer structuring for US residents.
Read guideUK buyers
Post-Brexit non-resident mortgages, UK-secured bridging and Spanish development finance.
Read guideGerman buyers
EU treatment, SCHUFA and euro-income buyers across the Costa del Sol and Mallorca.
Read guideFrench buyers
French residents buying on the Costa Brava, Barcelona and the Balearics.
Read guideDutch buyers
Box 3, mortgage-interest treatment and EU-friendly lender routes for NL residents.
Read guideBelgian buyers
Euro income, EU LTVs and the Costa Blanca corridor for Belgian residents.
Read guidePolish buyers
PLN income treatment, BIK reports and EU lender routes for Polish residents.
Read guideSwedish buyers
SEK income, EU treatment and the Costa del Sol Nordic corridor.
Read guideNorwegian buyers
NOK income, EEA lender treatment and the FX conversion right on a EUR loan.
Read guideDanish buyers
DKK–EUR peg, EU treatment and standard Nordic corridor timelines.
Read guideSwiss buyers
CHF income, private-banking routes and high-value villa financing.
Read guideIrish buyers
EU treatment, euro income and Central Bank of Ireland macroprudential rules.
Read guideCanadian buyers
CAD income, non-EU tax treatment and CRA T1135 foreign-property reporting.
Read guideAustralian buyers
AUD income, non-EU LTVs and why SMSF structures rarely work in Spain.
Read guideMiddle East buyers
UAE and GCC villa buyers, private-banking structures and AUM-backed lending.
Read guideReady to explore your options?
Speak to a Spanish property finance specialist.
A discreet, no-obligation conversation with a UK & Spain-focused specialist who understands both the UK and Spanish lending landscape.