United Kingdom property — Whole-of-market UK mortgage advice

UK Mortgages

Whole-of-market UK mortgage advice.

Residential, high-value, expat, buy-to-let and private bank mortgages — arranged by an independent brokerage with access to the entire lender market.

Get Your Finance Assessment

Two quick steps — a specialist will respond within one working day.

  • 40+ lendersWhole-of-market panel
  • 8–14 weeksTypical completion
  • Rated ExcellentClient reviews
  • No obligationFree initial review
£

An exact value lets us calculate your LTV straight away.

£

An exact figure lets us calculate LTV and indicative terms straight away.

Your figures

You're enquiring about finance for property in United Kingdom.
Confidential — no obligation Rated 4.9 on Trustpilot

Last updated Reviewed by our Clifton International finance team.

In short

How do UK mortgages work for international buyers?

International and expat buyers can generally borrow up to 75% of value on UK property, on personal or limited-company terms, over five to thirty years. Lending is assessed on documented income, and a well-prepared application typically completes in eight to fourteen weeks.

  • Foreign-currency income in USD, EUR and AED is accepted by specialist lenders.
  • Residential, buy-to-let and holiday-let purposes are all catered for.
  • Limited-company and SPV structures are standard for buy-to-let.
  • Private banks can support larger prime London purchases.

At a glance

Key facts

Figures reviewed:

Loan size
£100k – £25m+
Loan-to-value
Up to 90%
Term
Up to 35 years
Interest-only
Available
Income multiples
Up to 6x (select)
Typical set-up costs
1.5% – 2.5% of loan (arrangement, valuation, legals)Excludes stamp duty; non-resident surcharges may apply.
Typical timeline to drawdown
5 – 10 weeksAssumes a complete file; valuation and legal capacity drive the critical path. Where speed is of the essence, short term bridging finance can be used to secure the property (2 to 5 weeks to drawdown).
Adviser response time
Within one working day

Indicative figures for guidance only, correct as at October 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.

Methodology and assumptions

  • Figures are compiled by Clifton International specialists from live lender term sheets, indicative quotes and completed transactions arranged over the preceding 12 months.
  • Rates and costs are stated as ranges rather than a single number because pricing is set case-by-case on borrower profile, residency, asset type, location and loan-to-value.
  • Timelines assume a complete document file from the outset; valuation, legal capacity and (in Spain) NIE and notary availability drive the critical path.
  • Costs exclude any lender, broker or third-party fees not stated on the page, and exclude currency movement between agreement and drawdown.
  • Figures are reviewed monthly and re-checked against lender pricing whenever a material market change occurs.

Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.

Why clients choose us

Benefits at a glance

Large mortgages

Bespoke lending on mortgages from £500k to £25m+, including private bank introductions.

High-net-worth

Bespoke underwriting for HNW clients using AUM, bonus, dividend and international income.

Expat & international

UK mortgages for expatriates, foreign nationals and returning UK residents.

Buy-to-let & HMO

Individual and SPV structures for BTL, HMO, holiday let and multi-unit freehold blocks.

Interest-only

Interest-only structures with credible repayment strategies for qualifying borrowers.

Complex income

Self-employed, contractors, business owners, retained profits and non-standard income sources.

Borrower eligibility

Who we can help

  • UK residents and expatriates
  • High-net-worth individuals
  • Business owners and self-employed borrowers
  • Foreign nationals purchasing UK property
  • Buy-to-let and portfolio landlords

Typical lending criteria

Indicative parameters

Loan size
£100k – £25m+
Loan-to-value
Up to 90%
Term
Up to 35 years
Interest-only
Available
Income multiples
Up to 6x (select)

Indicative only. Actual terms depend on borrower profile, asset and lender criteria.

Recent transactions

Case studies from our files

Published transactions from our own case study library — select any to read the full brief.

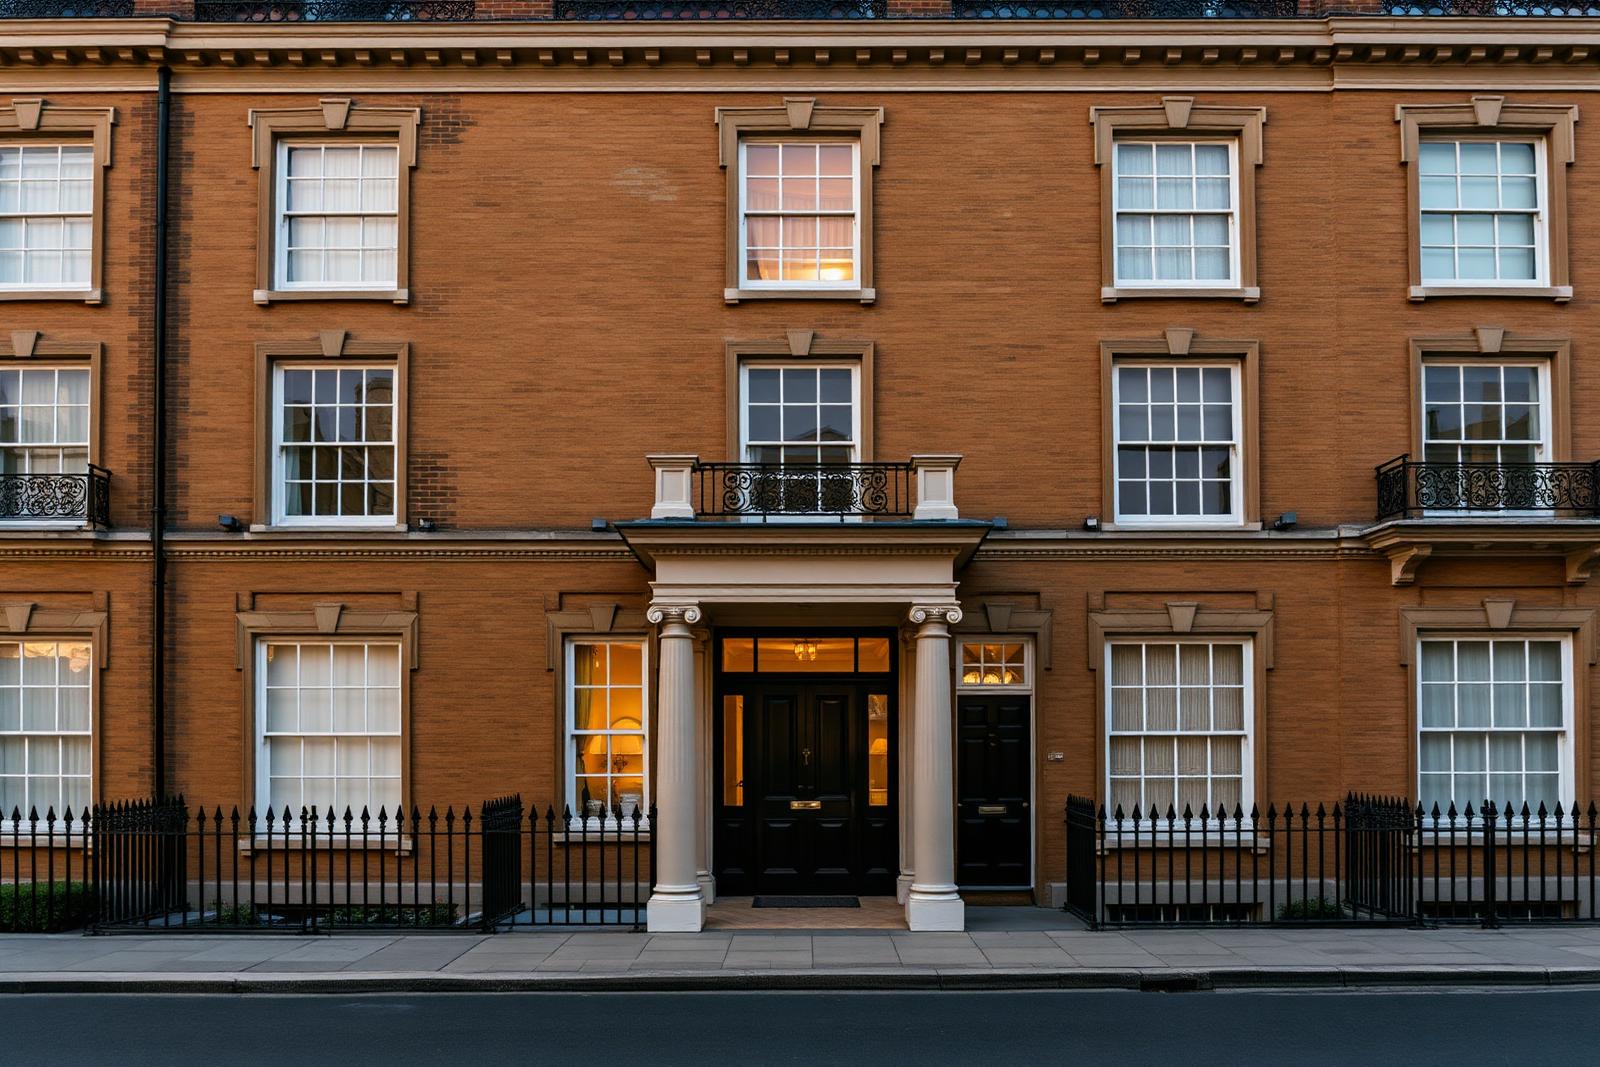
Illustrative detached Berkshire house and separate annexe — not the Reading clients’ actual property

Spain-based British expats · EUR income

£1.2m buy-to-let remortgage for British expats living in Spain

£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid

Clifton Private Finance reports a £1.2m buy-to-let remortgage for British expats living in Spain with euro salary income. Their six-bedroom former UK home with a detached annexe was retained as an investment, and the existing residential mortgage and bridging loan were refinanced before the bridge deadline. The supplied case identifies the location as Reading.

Read case study
Illustrative modern UK commercial office building — not the healthcare client's actual properties

London · Multi-site healthcare

£2m refinancing for a multi-site healthcare business: London, Birmingham and Bristol

£2m commercial mortgage · 15-year term · single charge on the London property

Clifton Private Finance’s January 2025 account reports a £2m owner-occupied commercial mortgage refinancing for a healthcare business operating from multiple UK sites: existing portfolio debt was consolidated into a single facility secured on the London property, leaving two offices unencumbered.

Read case study
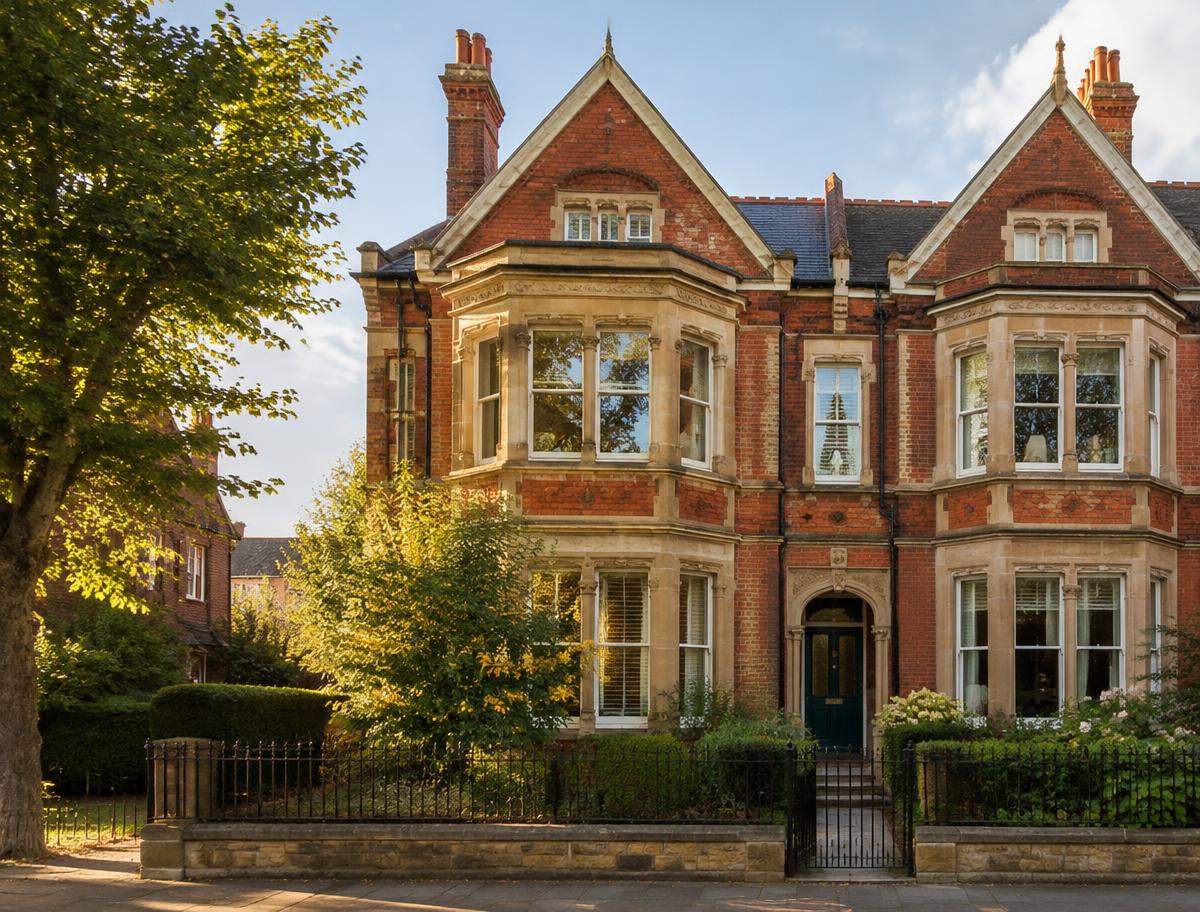
Illustrative Victorian red-brick townhouse on a leafy Oxford street — UK buy-to-let remortgage for expats in the US paid in dollars; not the clients' actual property

Oxford · US-based expats

£380,000 buy-to-let remortgage for UK expats in the US paid in dollars

£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income

A married couple living in San Francisco, paid largely in US dollars, remortgaged their Oxford buy-to-let — valued at approximately £1.29 million — and raised £380,000 through a lender experienced in expat and foreign-currency income.

Read case study

Frequently asked

Questions from clients

Do you arrange UK mortgages over £1 million?

Yes — large and million-pound mortgages are a core specialism, with direct access to UK private banks and specialist high-net-worth lenders for cases from £1m to £25m+.

Can expats and non-UK residents get a UK mortgage?

Yes. We arrange UK residential and buy-to-let mortgages for British expatriates, returning UK residents and foreign nationals purchasing UK property, including borrowers paid in USD, EUR, AED and other major currencies.

Do you handle complex or self-employed UK income?

Yes. Self-employed, company director, bonus, dividend, retained profits, LLP partner and international income cases are routine — we place them with lenders that underwrite manually rather than by algorithm.

Can I borrow more than 5x income on a UK mortgage?

In select cases yes. Professionals and HNW borrowers can access 5.5x–7x income through private banks and specialist lenders, subject to affordability, deposit and overall profile.

What deposit do I need for a UK mortgage?

Typically 10–25% for UK residents and 25–40% for expats and foreign nationals. Some private bank arrangements allow lower deposits against a broader assets-under-management relationship.

Can I use a UK mortgage to buy through a limited company or SPV?

Yes — buy-to-let and portfolio landlord mortgages via SPVs are widely available, and we regularly arrange structured lending for HNW clients purchasing through corporate or trust structures.

Are you regulated by the FCA?

Yes. Clifton International is authorised and regulated by the Financial Conduct Authority for regulated mortgage business in the UK.

Currency exchange

Funds coming from abroad? Plan the currency with the finance.

If any of your deposit, proceeds or income is held outside sterling, the rate you convert at matters as much as the mortgage rate. We can introduce you to an FCA-authorised currency specialist so your funds arrive on time for completion.

  • Fix today’s rate for a future completion date
  • Typically tighter margins than a bank international transfer
  • Transfers coordinated with your solicitor’s completion timetable

Clifton introduces clients to a specialist currency partner and does not hold, convert or transfer client funds.

Comparing countries

Also financing property in Spain?

Many of our clients hold Spanish and UK property, or are deciding between the two markets. Our international mortgage hub sets out what we arrange in each country, so you can compare the options side by side before you enquire.

Ready to explore your options?

Speak to a UK property finance specialist.

A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.