£2.2M buy-to-let mortgage for a Dubai-based investor
£2.2m · 55% LTV · 25-year expat BTL
In short
How did a Dubai-based investor secure a £2.2m UK buy-to-let mortgage?
A Dubai-based investor secured a £2.2m buy-to-let mortgage at approximately 55% loan-to-value on a prime London rental valued at around £4m, arranged interest-only over a 25-year term with a specialist expat lender. The interest-only structure preserved the client's capital for other investments, and the property was let within six weeks of completion.
- Borrower: a Dubai-based international investor, assessed on their overall financial position rather than conventional criteria alone.
- Facility: £2.2m buy-to-let mortgage at approximately 55% LTV against a London investment property valued at around £4m.
- Structure: 25-year interest-only term, keeping monthly commitments low and capital available for other investments.
- Reported outcome: purchase completed on schedule and let within six weeks; the rate and fees are not disclosed.
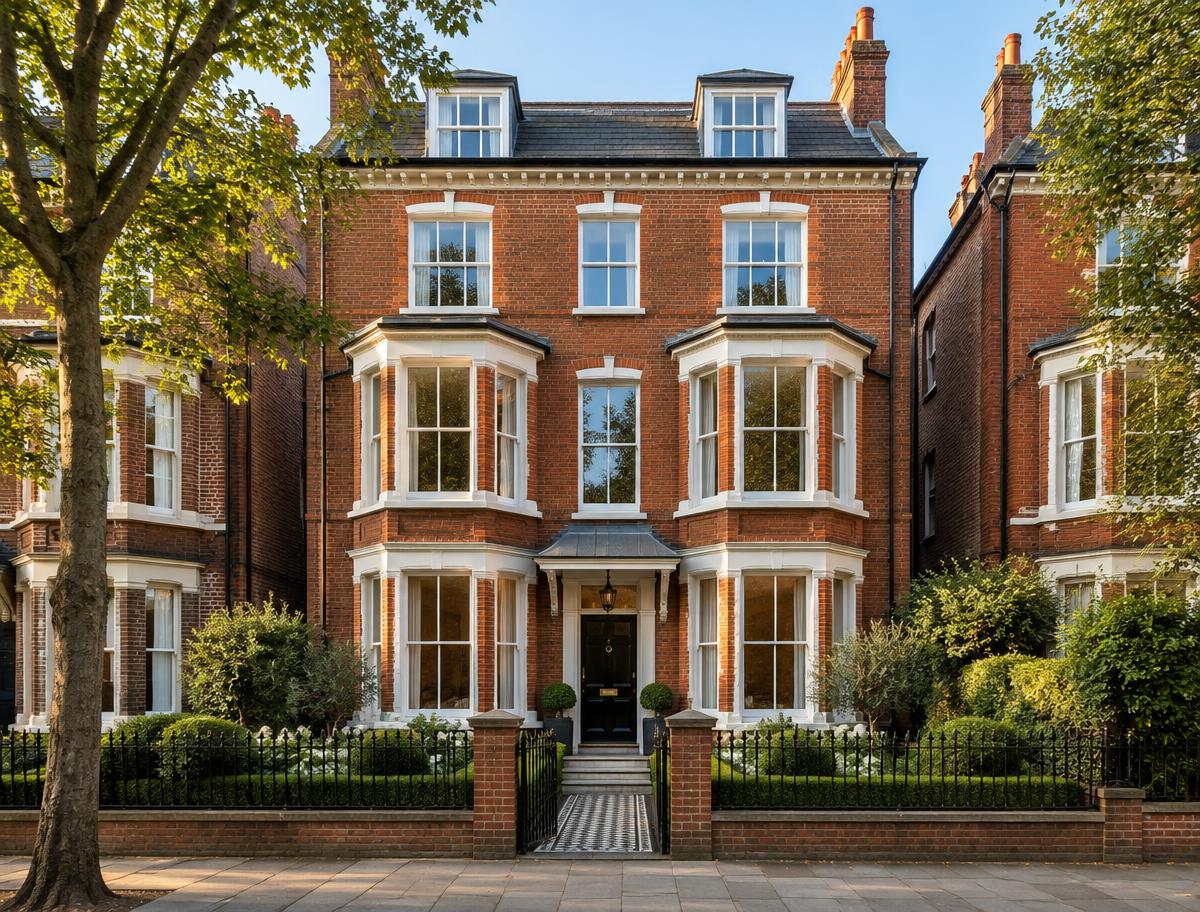
Illustrative property image — not the clients’ actual property.
- Loan amount
- £2,200,000
- Property value
- £4,000,000 (approx.)
- LTV
- 55%
- Term
- 25 years
- Repayment
- Interest-only
- Client base
- Dubai
- Challenge
- A Dubai-based investor had identified a substantial UK investment property — a prime rental in London valued at approximately £4m — and required a significant buy-to-let mortgage to complete the acquisition. While the client held considerable assets and strong earning capacity, the priority was to structure the acquisition efficiently, preserving capital for other investment opportunities rather than concentrating equity in a single property. As a borrower resident in the UAE, securing finance at this level required careful lender selection: large loan requirements combined with overseas income and international assets often fall outside mainstream buy-to-let appetite, and the funding needed to recognise the strength of the client's overall financial position rather than rely solely on conventional criteria.
- Solution
- Clifton International facilitates introductions to specialist property finance teams, rather than acting as lender or mortgage adviser. Drawing on a network of specialist expat lenders and private banks experienced with globally mobile clients, the case was placed with a lender familiar with UAE tax residency and high-value buy-to-let transactions. A comprehensive picture of the client's wealth, income and investment strategy was presented to the lender, and the transaction was managed from initial enquiry through to completion — packaged around the property's rental cover and negotiated against aggregated exposure limits — so the structure supported both the acquisition and the client's wider financial objectives.
- Funding structure
- A £2.2m expat buy-to-let mortgage at approximately 55% LTV against a London investment property valued at around £4m, arranged over a 25-year interest-only term.
- Outcome
- The mortgage completed and the acquisition proceeded on schedule, allowing the client to expand UK property holdings while retaining substantial liquidity for future investments. The property was tenanted on a long-term assured shorthold tenancy within six weeks of completion. This is a reported case-specific outcome, not a promise of comparable terms; expat buy-to-let eligibility, rental cover and structure are assessed individually.
Case evidence, sources and limitations
Source: Clifton International's supplied case-study account of an anonymised completed transaction for a Dubai-based investor acquiring UK buy-to-let property. Clifton International facilitates introductions to specialist property finance teams and was not the lender or mortgage adviser. Figures and outcomes are reported case facts, not independently audited market statistics.
The interest rate, product fees, rental-coverage calculation, lender identity and completion date are not disclosed. The approximately 55% LTV is indicative, calculated from the £2.2m loan against the property value of around £4m stated in the account; the lender's own valuation is not supplied. The property image is an illustration, not the client's actual property. Other applications require individual underwriting, evidenced overseas income and a satisfactory rental assessment. Your property may be repossessed if you do not keep up repayments on your mortgage.
Case narrative updated . This is an editorial date, not the completion date.
- HMRC: tax on UK rental income for landlords abroad
General tax context for overseas landlords, not evidence of this transaction or a statement of the client's tax position.
- GOV.UK: Stamp Duty rates for non-UK residents
Official residential SDLT rates, including the surcharges that can apply when buying an additional UK property from overseas; not the figures for this transaction.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£380,000 buy-to-let remortgage for UK expats in the US paid in dollars
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
FAQs
Questions on this case
- Can overseas residents get a UK buy-to-let mortgage?
- Yes. A dedicated expat buy-to-let market exists for UK nationals living abroad, though most mainstream BTL lenders restrict non-resident applicants. Specialist expat lenders underwrite overseas residency directly — this £2.2m purchase at about 55% LTV was arranged with a lender experienced in expat BTL.
- Can I use UAE income to qualify for a UK buy-to-let mortgage?
- Yes, with the right lender. Specialist expat BTL lenders are familiar with UAE tax residency, employment structures and documentation. This Dubai-based client's UAE income was accepted as the qualifying income for the £2.2m facility.
- How is rental cover assessed on an expat buy-to-let?
- Lenders assess whether the expected rent covers the mortgage interest — typically expressed as a rental coverage ratio, and usually calculated on an interest-only basis, sometimes stressed at a higher rate. In this case the deal was packaged around the rental cover of the prime London property.
- Are large expat buy-to-let loans available interest-only?
- Yes. Interest-only is common on buy-to-let, including for expat borrowers, with the loan repaid from sale, refinance or other assets at the end of the term. This £2.2m facility was arranged interest-only over a 25-year term.
- Why keep a large buy-to-let purchase interest-only?
- For portfolio investors, interest-only keeps monthly commitments low and leaves more capital free for other opportunities, with the loan repaid later from sale, refinance or other assets. In this case the Dubai-based client specifically wanted to avoid concentrating capital in a single property; the 25-year interest-only structure supported that strategy.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
UK expat finance
Explore more UK expat mortgage guidance
Expat guides and tools
- UK expat mortgages hub
- UK expat mortgage calculator — overseas income and deposit
- UK expat finance guide
- UK expat finance FAQs
- Which UK banks lend to expats
- Expat first-time buyer mortgages
- UK expat remortgage guide
- Limited company buy-to-let for expats
- Stamp Duty surcharge for non-residents
- Bridging loans for expats and non-residents
- UK mortgages on Australian dollar income
- Australian nationals buying in the UK
Expat case studies
- All expat case studies by country and topic
- £35,000 UK second charge for relocation to Normandy (source: Clifton Private Finance)
- Spain-based expats’ Reading buy-to-let remortgage (£1.2m; source: Clifton Private Finance)
- Singapore expat buy-to-let remortgage (£250k)
- Canada-based doctor's Ealing purchase (£862k)
- Canada-based expat’s Birmingham commercial portfolio (£1.5m; source: Clifton Private Finance)
- Qatar expat first-time buyer example (£290k)
- Hong Kong-based Cotswolds bridging loan
- £840k Surrey bridge for a family returning from Asia
UK mortgages by country of residence
- Expats in UAE
- Expats in Dubai
- Expats in Saudi Arabia
- Expats in Qatar
- Expats in Kuwait
- Expats in Bahrain
- Expats in Oman
- Expats in Hong Kong
- Expats in Singapore
- Expats in China
- Expats in Japan
- Expats in Australia
- Expats in New Zealand
- Expats in Canada
- Expats in USA
- Expats in Spain
- Expats in France
- Expats in Ireland
- Expats in Germany
- Expats in Netherlands
- Expats in Switzerland
- Expats in South Africa
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.