£230k bridging loan secured against UK property to buy a Malaga apartment
£230k · c.25% LTV · 36 days to completion
36 days to completion
In short
How was £230k bridging loan secured against UK property to buy a Malaga apartment financed?
Clifton International arranged regulated bridging loan for this Edinburgh / Malaga transaction — £230k, c.25% LTV, 36 days to completion. £230k regulated bridging loan secured against a £965k unencumbered Edinburgh residential property, c.25% LTV, used to complete the purchase of a Malaga apartment.
- Location: Edinburgh / Malaga. Finance type: Regulated bridging loan.
- Time to funding: 36 days to completion.
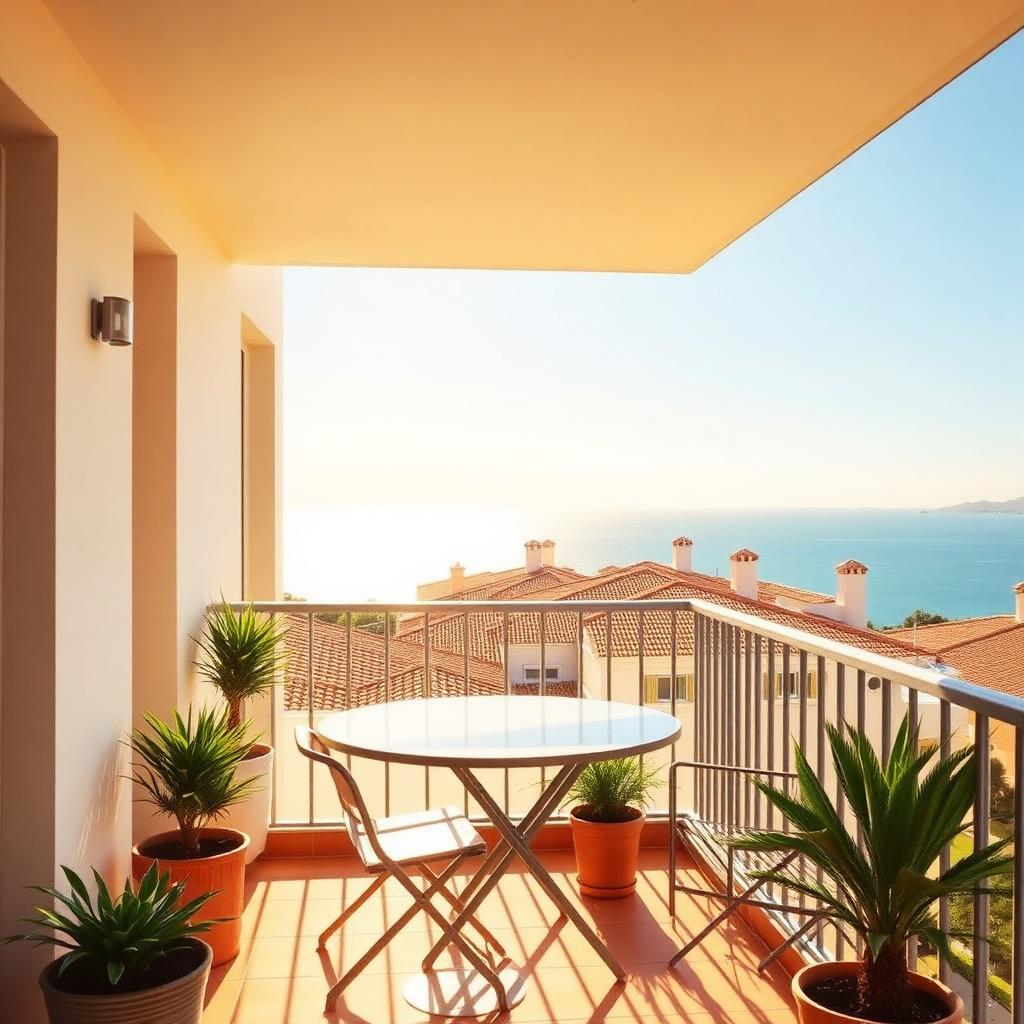
- Our client was relocating to Malaga to live near her daughter and had found a £230k apartment that ticked every box. The Malaga property was likely to sell quickly, while her main residence in Edinburgh — a unique, high-value detached home worth £965k with no mortgage — was expected to take longer to sell.
- The bridging offer was secured in 12 days, legal work completed in 24 days, and funds cleared in 36 days — allowing our client to secure her new home in Malaga without losing it to another buyer.
- Loan amount
- £230,000
- Security value
- £965,000
- LTV
- c.25%
- Use of funds
- Malaga apartment purchase
- Offer secured
- 12 days
- Completion
- 36 days
- Challenge
- Our client was relocating to Malaga to live near her daughter and had found a £230k apartment that ticked every box. The Malaga property was likely to sell quickly, while her main residence in Edinburgh — a unique, high-value detached home worth £965k with no mortgage — was expected to take longer to sell.
- Solution
- Using the unencumbered Edinburgh property as security, we arranged a £230k regulated bridging loan at approximately 25% LTV. This low loan-to-value opened up competitive bridging options despite the overseas use of funds. We negotiated terms with a specialist lender, managed the share-of-freehold complication, and chased both sets of solicitors through UK and Scottish legal overlap.
- Funding structure
- £230k regulated bridging loan secured against a £965k unencumbered Edinburgh residential property, c.25% LTV, used to complete the purchase of a Malaga apartment.
- Outcome
- The bridging offer was secured in 12 days, legal work completed in 24 days, and funds cleared in 36 days — allowing our client to secure her new home in Malaga without losing it to another buyer.
More UK case studies
Related transactions
Using Bridging Finance to Unlock Equity from London Investment Properties and Secure a New Family Home
£1.1m facility · 12-month term · investment-property sale exit
£120K Bridging Loan Secured Against a London Buy-to-Let to Release Capital for a Property Purchase Overseas
£120,000 bridge · ~£750,000 London BTL · completed in five weeks
£1.3M bridging loan to support a significant upsize in Leeds
£1.3m · 65% LTV · 12-month regulated bridge
FAQs
Questions on this case
- Can I use a UK property as security for a bridging loan to buy in Malaga?
- Yes. UK regulated bridging lenders will lend against an unencumbered or lightly mortgaged UK residential property and permit the funds to be used to purchase a home in Spain, including Malaga. In this case, £230k was raised against a £965k Edinburgh home at c.25% LTV.
- How quickly can a bridging loan for an overseas property purchase complete?
- With a low LTV, clean UK security and a proactive legal team, completion is typically 4–8 weeks. This Malaga case study completed in 36 days — offer in 12 days and legal work in a further 24 days.
- Is a bridging loan cheaper than a Spanish mortgage for a Malaga apartment?
- Not usually on headline rate, but a UK bridge can be faster, avoids Spanish non-resident mortgage underwriting delays, and lets buyers proceed as cash in Spain. It is typically refinanced onto a longer-term facility or repaid from the sale of the UK property.
- What loan-to-value can I raise against an unencumbered UK home for an overseas purchase?
- Regulated bridging lenders typically go up to 65–70% LTV against a UK residential property, subject to exit strategy. Lower LTVs — as in this 25% LTV Malaga case — unlock the most competitive pricing and fastest turnarounds.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.