UK Property & Business Finance
UK property finance.
Mortgages for homes and buy-to-let investments, short-term bridging for time-critical purchases, and development or commercial property finance. We introduce UK residents, expats and international buyers to specialist intermediaries.
Get Your Finance Assessment
Two quick steps. A specialist will respond within one working day.
- 40+ lendersWhole-of-market panel
- 8–14 weeksTypical completion
- Rated ExcellentClient reviews
- No obligationFree initial review
In short
What UK property finance is available to residents and expats?
UK property finance includes residential and buy-to-let mortgages, short-term bridging loans, development finance and commercial mortgages. UK residents, British expats and foreign nationals can be considered, depending on the lender, property, income and deposit. Clifton International introduces clients to specialist intermediaries; we are not a lender.
- Term mortgages depend on affordability and the lender's property criteria.
- Bridging finance requires suitable security and an evidenced repayment exit.
- Overseas-income applications involve currency, residency and local-document checks.
- Choose the London bridging or expat mortgage guidance below for costs, examples and next steps.
London bridging loans and UK expat mortgages
Bridging finance secured on London property
Compare regulated and unregulated bridging, explore a Richmond worked example and calculate indicative costs using approved rates. Read London transaction case studies, completion timelines and official borough market figures.
London bridging loans, rates and calculatorUK mortgages when you live or earn overseas
Explore residential and buy-to-let options, approved indicative rates and affordability checks for foreign-currency income. Country guides explain local income records, residency evidence and deposit documentation; lender acceptance is case by case.
UK expat mortgages, rates and country guidesUsing UK income or property equity to buy a home in Spain? Our guide to Spanish mortgages for UK buyers covers non-resident mortgage options, GBP-to-EUR planning, UK-secured borrowing and the residency and tax checks to consider before committing.
What we arrange
Specialist UK finance across property and business.
From a high-value residential mortgage to a multi-million-pound development facility, one adviser manages the full transaction — lender selection, negotiation and completion.
Residential Mortgages
High-value residential property finance, complex income cases and private bank introductions.
UK Expat Mortgages
Residential and buy-to-let mortgages for overseas residents, with approved rates, currency checks and country-specific document guides.
Bridging Loans
Fast short-term facilities secured against UK property — regulated and unregulated.
Development Finance
Ground-up, conversion and refurbishment funding for UK residential and mixed-use schemes.
Commercial Property Finance
Owner-occupier, investment and portfolio commercial mortgages across the UK.
Remortgage
Refinance existing UK mortgages to improve terms, release equity or restructure debt.
Currency Hub
GBP transfers, forward contracts and how currency fits your mortgage — with questions and real cases.
Buy-to-Let & Portfolio
Individual, SPV and portfolio buy-to-let structures via mainstream and specialist lenders.
Why Clifton International
An award-winning, independent UK brokerage.
Winners of B&C's Regulated Bridging Broker of the Year 2026, recognised by NACFB and What Mortgage. We combine specialist market access with a bespoke, client-first advisory approach.
Independent, whole-of-market advice
Access to high-street banks, private banks and specialist lenders — with no lender bias.
High-value & complex cases
Large mortgages, private bank introductions, HNW, self-employed, expat and international income.
Bridging & development specialists
Regulated Bridging Broker of the Year 2026, deep relationships across the short-term market.
One senior adviser
You deal with an experienced specialist end-to-end — not a case handler or call centre.
FCA authorised
Fully authorised and regulated by the Financial Conduct Authority.
Selected case studies
Recent UK transactions
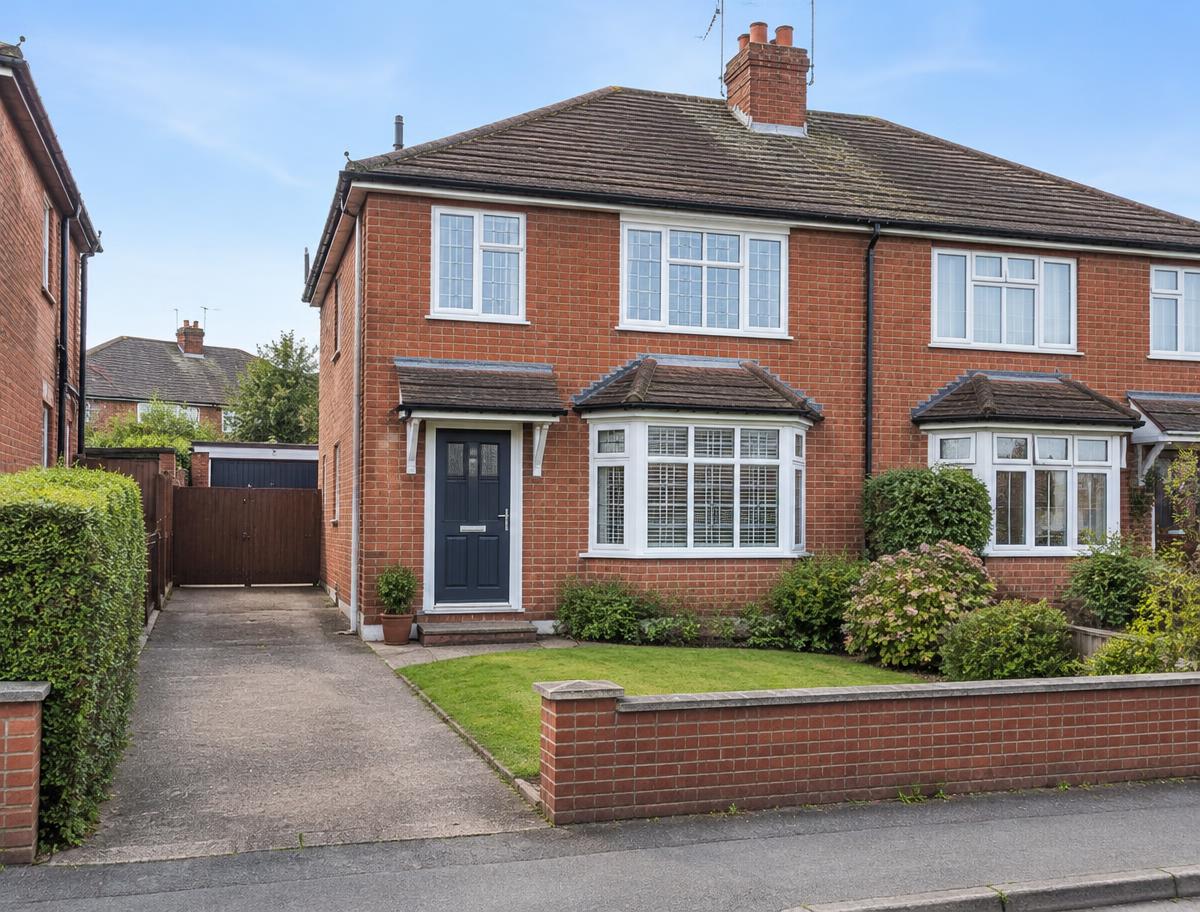
£35,000 second-charge finance for a British couple relocating to France
In this real client case, our sister brokerage, Clifton Private Finance, arranged £35,000 of second-charge finance secured on a British couple’s home in Rugby, Warwickshire to complete a Normandy property purchase before selling in the UK. One applicant was a self-employed designer working internationally. This is a relocation case, not evidence of acceptance of France-resident EUR income.
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
Clifton Private Finance reports a £1.2m buy-to-let remortgage for British expats living in Spain with euro salary income. Their six-bedroom former UK home with a detached annexe was retained as an investment, and the existing residential mortgage and bridging loan were refinanced before the bridge deadline. The supplied case identifies the location as Reading.
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
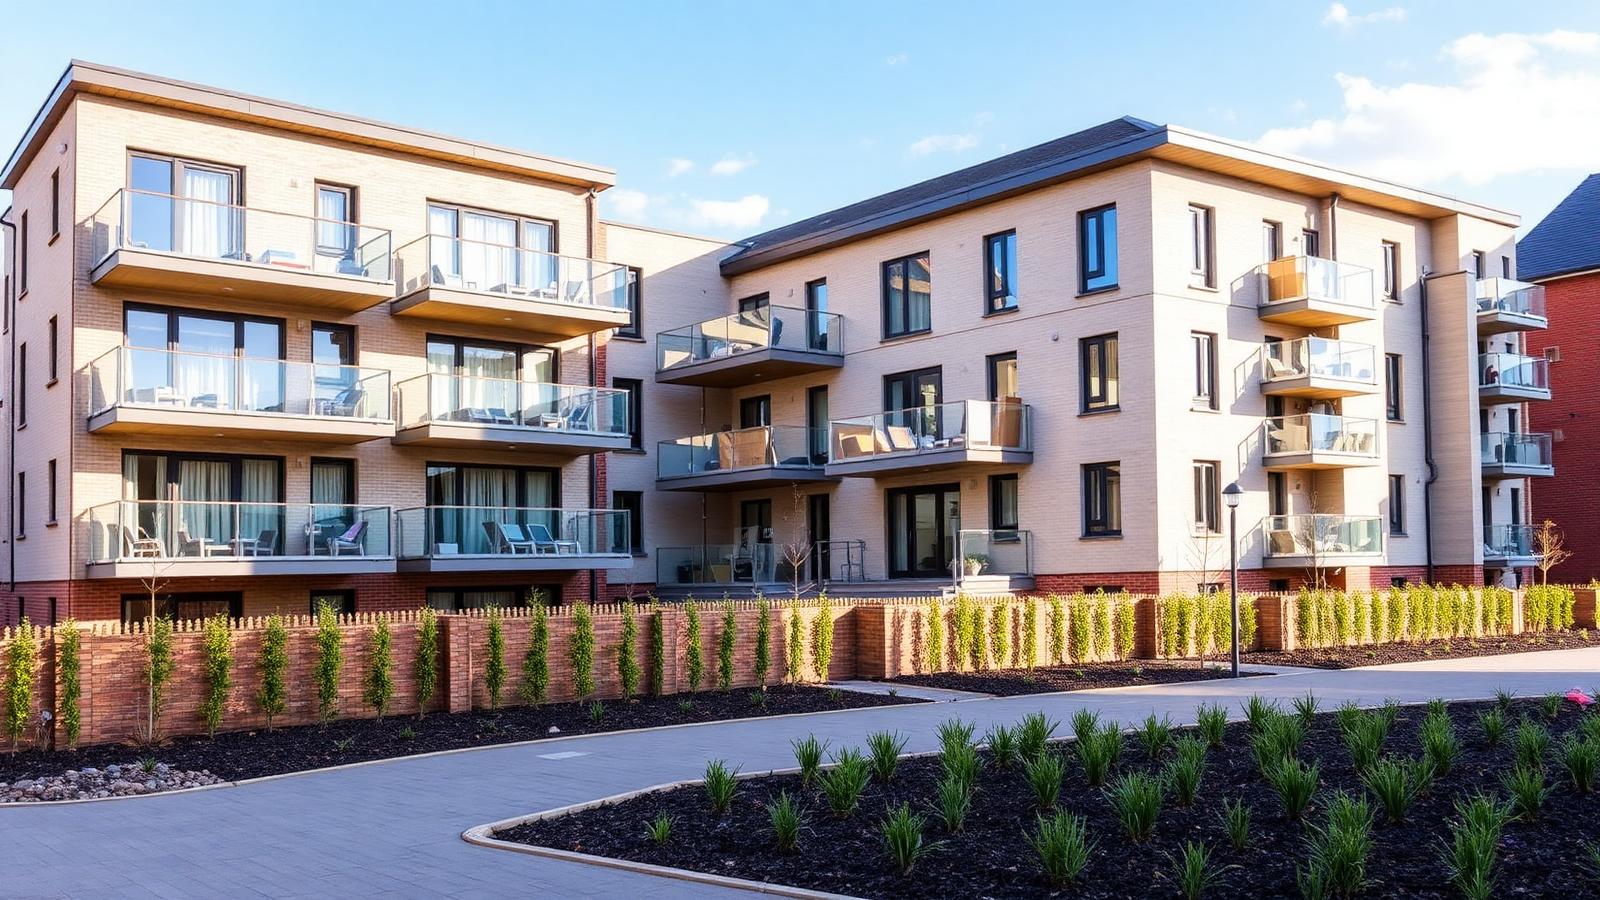
£1m+ development exit finance for an Essex residential scheme
Clifton PF International arranged a development exit facility of over £1 million for an experienced developer whose Essex residential scheme was approaching practical completion, refinancing a development loan nearing expiry and giving time to sell the units without a forced sale.
Over £1,000,000 development exit facility · existing development loan refinanced · orderly unit sales
Our process
A clear, considered path to completion.
- 01
Initial consultation
A confidential discussion to understand your objectives, timeline and profile.
- 02
Funding strategy
We prepare a bespoke strategy identifying the most suitable lenders and structures.
- 03
Lender negotiation
We approach lenders directly on your behalf and negotiate the sharpest terms available.
- 04
Offer & completion
We manage valuation, legal and drawdown through to funds released.
Common questions
UK property finance questions.
What UK property finance is available to residents and expats?
UK property finance includes residential and buy-to-let mortgages, short-term bridging loans, development finance and commercial mortgages. UK residents, British expats and foreign nationals can be considered, depending on the lender, property, income and deposit. Clifton International introduces clients to specialist intermediaries; we are not a lender.
Can expats get a UK mortgage?
Yes. British expats and foreign nationals borrow against UK property regularly, though the lender panel is narrower and most expect a larger deposit, typically 25% or more, plus evidence of foreign income.
How quickly can a UK bridging loan complete?
Straightforward bridging cases can complete in one to three weeks where valuation and legal work run in parallel and the exit is clearly evidenced. Complex security or title issues extend that timeline.
Will foreign currency income be accepted?
Specialist UK lenders may accept overseas income in USD, AED, EUR and other currencies. They assess the sterling equivalent, exchange-rate risk, income evidence and overseas commitments. Any currency adjustment depends on the lender and the case; there is no universal haircut.
Do you arrange development and commercial finance too?
Yes. We introduce clients to intermediaries arranging ground-up development, conversion and refurbishment funding, alongside owner-occupier and investment commercial mortgages across the UK.
Is there a fee for initial advice?
No. The first conversation and any indicative terms are free and carry no obligation. Any fee that becomes payable is disclosed to you in writing before you proceed.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.