Selected UK property & business finance transactions.
Real transactions arranged by our team across the UK — from regulated bridging and high-value mortgages to commercial finance, portfolio refinance and expat & foreign national lending. Select any case to read the full brief.
In short
What UK property finance has Clifton International arranged?
Clifton International arranges bridging loans, residential and expat mortgages, commercial and development finance on UK property. The case studies below are real completed transactions, from roughly GBP 230,000 to GBP 4m, covering chain breaks, time-critical purchases, portfolio refinance, complex income and overseas buyers purchasing in the United Kingdom.
Cases span bridging, mortgage, commercial, development and expat or foreign national lending.
Several bridging cases completed inside two weeks against a fixed contractual deadline.
Clients include UK residents, Dubai-based expats and international buyers with complex income.
Each case study sets out the challenge, the structure agreed and the outcome for the client.
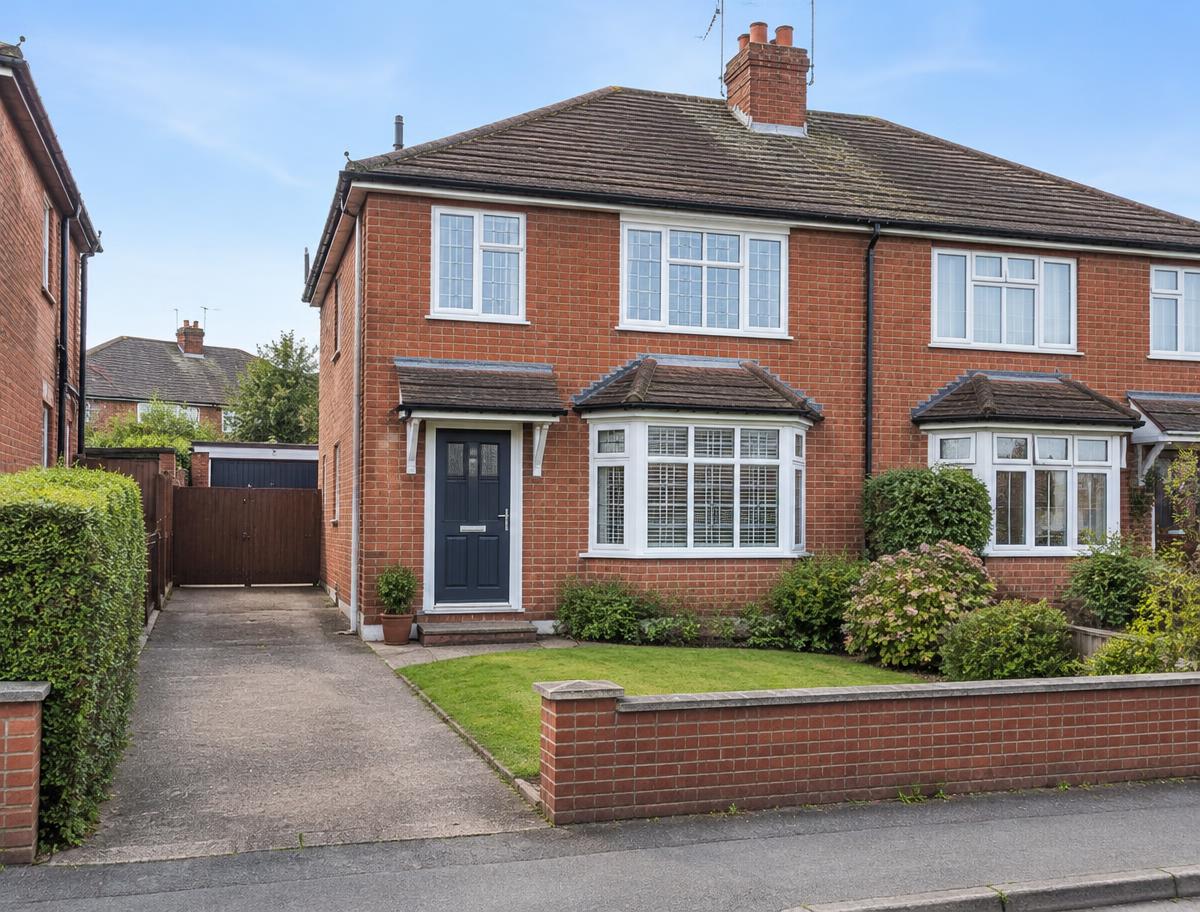
In this real client case, our sister brokerage, Clifton Private Finance, arranged £35,000 of second-charge finance secured on a British couple’s home in Rugby, Warwickshire to complete a Normandy property purchase before selling in the UK. One applicant was a self-employed designer working internationally. This is a relocation case, not evidence of acceptance of France-resident EUR income.
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
Clifton Private Finance reports a £1.2m buy-to-let remortgage for British expats living in Spain with euro salary income. Their six-bedroom former UK home with a detached annexe was retained as an investment, and the existing residential mortgage and bridging loan were refinanced before the bridge deadline. The supplied case identifies the location as Reading.
Over £1,000,000 development exit facility · existing development loan refinanced · orderly unit sales
Clifton PF International arranged a development exit facility of over £1 million for an experienced developer whose Essex residential scheme was approaching practical completion, refinancing a development loan nearing expiry and giving time to sell the units without a forced sale.
Reported £1.5m capital raised · £2.4m portfolio · share purchase
Clifton Private Finance’s March 2022 account reports £1.5m capital raised for a British national spending most of his time in Canada, buying shares in a company holding a Birmingham portfolio of shops, offices and retail showrooms valued at £2.4m.
£2m commercial mortgage · 15-year term · single charge on the London property
Clifton Private Finance’s January 2025 account reports a £2m owner-occupied commercial mortgage refinancing for a healthcare business operating from multiple UK sites: existing portfolio debt was consolidated into a single facility secured on the London property, leaving two offices unencumbered.
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
A married couple living in San Francisco, paid largely in US dollars, remortgaged their Oxford buy-to-let — valued at approximately £1.29 million — and raised £380,000 through a lender experienced in expat and foreign-currency income.
Reported £500k mortgage · ~£1.6m new-build Paddington apartment · about 31% LTV · US dollar income
Clifton Private Finance’s account reports a £500,000 UK mortgage for a married American couple buying a new-build second home in Paddington, London, valued at approximately £1.6 million, with both applicants employed in the US and paid in US dollars.
£490,000 mortgage · £611,000 Leeds home · offer within two weeks
A limited-company IT contractor paid in euros secured a £490,000 mortgage offer for a £611,000 detached family home in Leeds after previous applications were unsuccessful. Specialist assessment considered the underlying day-rate contract income rather than salary and dividends alone.
£1.1m facility · 12-month term · investment-property sale exit
A landlord used a £1.1 million bridging facility to redeem mortgages on Ealing and Plymouth buy-to-lets and purchase her rented Hertfordshire home before selling the investments, despite historic CCJs.
£120,000 bridge · ~£750,000 London BTL · completed in five weeks
An overseas-based owner used a £120,000 bridging loan secured on her London buy-to-let, valued at about £750,000, to fund the final stages of an overseas home purchase, managed fully remotely.
£250k capital release · Singapore-based couple · SGD income
A British couple living and working in Singapore remortgaged a well-performing Surrey buy-to-let and released £250,000 to restructure borrowing across their wider UK property portfolio.
£862k mortgage · £1.15m Ealing new-build · CAD income
A British couple living in Toronto — a consultant anaesthesiologist and a pharmaceutical executive — secured an £862,000 mortgage on a £1.15m West London new-build after a high street decline.
Reported £1.2m mortgage · ~£2.03m Ealing purchase · Saudi income with allowances and bonuses
Clifton Private Finance’s July 2023 account reports a £1.2m residential mortgage for a UK couple upsizing in Ealing, based on the husband’s Saudi Aramco package of salary, bonuses, housing, living and school-fee allowances.
Reported £570k mortgage · ~£815k Milton Keynes purchase · 70% LTV · BHD income · no early repayment charges
Clifton Private Finance’s account reports a £570,000 residential mortgage at about 70% loan-to-value for a British expat in Bahrain buying a Milton Keynes home, with income paid entirely in Bahraini dinar, limited recent UK credit and shipyard employment.
Reported £410k raised · mortgage-free London BTL valued ~£1.3m · ~£2,500/month rent · JPY income
Clifton Private Finance’s account reports £410,000 raised through a buy-to-let remortgage on a mortgage-free London rental valued at about £1.3 million, for a British national in Japan paid entirely in yen, to fund the deposit on a second UK property.
£500k mortgage · Clifton flat · AUD income via trust structure · approved within weeks
A British national returning to the UK after more than ten years in Australia secured a £500,000 residential mortgage on a flat in Clifton, Bristol, despite overseas income through a trust-owned business and a UK credit profile still being rebuilt.
An illustrative example of how a British couple teaching in Doha could buy their first UK home — a £290,000 Birmingham semi — with a 25% deposit, Qatari riyal income and first-time buyer Stamp Duty relief, plus the 2% non-resident surcharge.
£809k residential mortgage against a non-standard Hertfordshire countryside home — placed with a private bank willing to underwrite the unusual construction and refinance the existing bridge in full.
£4m portfolio refinance for a Midlands property investment group — improving margin, releasing capital and consolidating multiple facilities into a single lender relationship.
£2m interest-only expat remortgage on a prime UK residence for a HNW client with multi-currency income across three jurisdictions — placed with a private bank on preferential terms.
A Dubai-based investor secured a £2.2m buy-to-let mortgage on a prime London rental valued at approximately £4m — structured interest-only to preserve capital for wider investments.
£850k commercial bridge to acquire and renovate a Dronfield care home, with a clean exit onto long-term commercial investment finance once trading data was established.
A £160k regulated bridge secured against a Gillingham home after an onward sale collapsed, allowing the client to complete on a Valencia property and protect a 15% deposit.
€3m bridging loan secured against a residential property in Ibiza to complete significant development works on a London property, after further advances against the UK asset were not available.
A £500k regulated bridging loan helped an unmarried couple — one a UK national, the other an Australian working in Hong Kong — buy a renovated cottage in Painswick before selling their home near Swindon.
£840,000 raised · Surrey family home · purchase completed within four weeks
A family who had recently returned to Britain after living and working as expats in Asia used an £840,000 bridging loan to buy their Surrey family home without waiting to re-establish UK mortgage eligibility. The purchase completed within four weeks and the bridge was repaid a few months later once a mainstream mortgage was arranged.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.
 UK second charge