£500K Cotswolds bridging loan for a couple with an Australian national working in Hong Kong
£500k · 50% LTV · regulated bridge
Finance in place within weeks
In short
How was £500K Cotswolds bridging loan for a couple with an Australian national working in Hong Kong financed?
Clifton International arranged regulated bridging loan for this Painswick, Cotswolds transaction — £500k, 50% LTV, regulated bridge. £500k regulated bridging loan at around 50% LTV, covering the full purchase price and part of the stamp duty, repaid from the sale of the couple's home near Swindon.
- Location: Painswick, Cotswolds. Finance type: Regulated bridging loan.
- Time to funding: Finance in place within weeks.
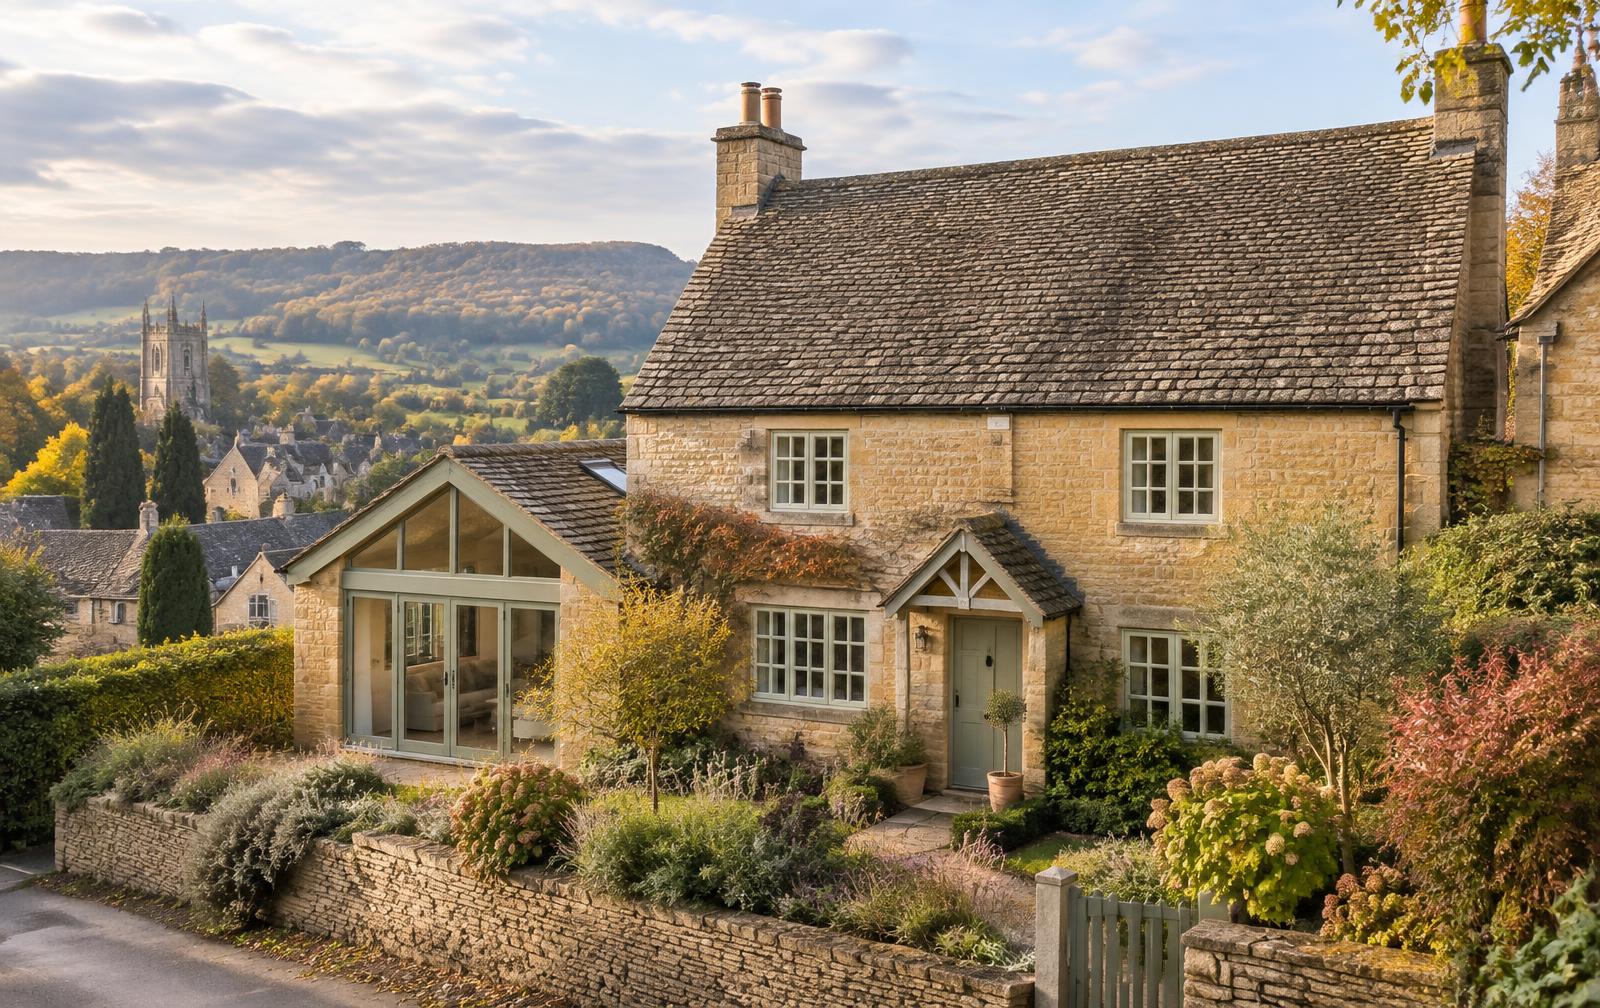
- A couple aged 60 and 70 wanted to move from their house outside Swindon to a newly renovated and extended cottage in Painswick, in the Cotswolds, without waiting for their sale. They needed to borrow the full purchase price plus part of the stamp duty. One partner is a UK national working in the UK; the other is an Australian national working in aircraft management in Hong Kong. Most regulated bridging lenders require both joint applicants to be UK nationals and UK residents, which ruled out the mainstream market.
- The lender offered a highly competitive rate and finance was in place within weeks, so the couple could make a firm, chain-free offer and secure the cottage.
- Loan amount
- £500,000
- LTV
- Approx. 50%
- Location
- Painswick, Cotswolds
- Applicants
- UK national + Australian national in Hong Kong
- Exit
- Sale of existing home near Swindon
- Challenge
- A couple aged 60 and 70 wanted to move from their house outside Swindon to a newly renovated and extended cottage in Painswick, in the Cotswolds, without waiting for their sale. They needed to borrow the full purchase price plus part of the stamp duty. One partner is a UK national working in the UK; the other is an Australian national working in aircraft management in Hong Kong. Most regulated bridging lenders require both joint applicants to be UK nationals and UK residents, which ruled out the mainstream market.
- Solution
- The case was taken to specialist lenders known to consider unusual residency and nationality profiles. The first lender declined; the second was persuaded by the quality and location of the Painswick cottage and by the low overall loan-to-value, with the couple's existing home also providing a clear exit.
- Funding structure
- £500k regulated bridging loan at around 50% LTV, covering the full purchase price and part of the stamp duty, repaid from the sale of the couple's home near Swindon.
- Outcome
- The lender offered a highly competitive rate and finance was in place within weeks, so the couple could make a firm, chain-free offer and secure the cottage.
More UK case studies
Related transactions
£1.3M bridging loan to support a significant upsize in Leeds
£1.3m · 65% LTV · 12-month regulated bridge
£230k bridging loan secured against UK property to buy a Malaga apartment
£230k · c.25% LTV · 36 days to completion
£1.2M bridging loan secured to complete dream home purchase in Oxfordshire
£1.2m · 60% LTV · chain-break bridge
FAQs
Questions on this case
- Can an Australian national living overseas get a UK regulated bridging loan?
- Yes, but the lender pool is small. Most regulated bridging lenders want every applicant to be a UK national and UK resident. In this case a specialist lender accepted a couple where one partner was an Australian national working in Hong Kong.
- Does a low LTV help foreign nationals get a bridging loan?
- Yes. A low loan-to-value — around 50% here — and a high-quality property reduce the lender's risk, which made the lender comfortable with the non-UK applicant and able to offer a competitive rate.
- Can a bridging loan cover stamp duty as well as the purchase price?
- It can, provided the total borrowing fits within the lender's LTV limit against the security. Here the loan covered the full purchase price and part of the stamp duty.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.