Real UK transactions and practical guidance for expats, foreign nationals and investors — bridging, high-value mortgages, development, commercial finance and remortgage.
In short
What guides are available on UK property finance for expats?
Our UK resource library explains how UK property finance works for expats, foreign nationals and overseas buyers. The guides cover how lenders assess foreign income, the non-resident stamp duty surcharge, document requirements for US and Gulf-based applicants, bridging loans, and limited-company buy-to-let structures, each with indicative costs and timelines.
Foreign income is usually accepted with a 20–30% affordability haircut.
Non-UK residents pay a 2% SDLT surcharge, sometimes reclaimable.
Document and certification standards vary by lender and country.
Limited-company structures are standard for expat buy-to-let.
Tools
Expat stamp duty surcharge calculator
Work out the full SDLT bill on a UK purchase as a non-resident — standard bands, the 5% additional-property surcharge and the 2% non-resident surcharge, with the surcharge cost shown separately so you know exactly what your residence status is costing.
Individual, joint or company/SPV purchases
Effective rate and full band breakdown
Shows what you could reclaim if you become UK resident
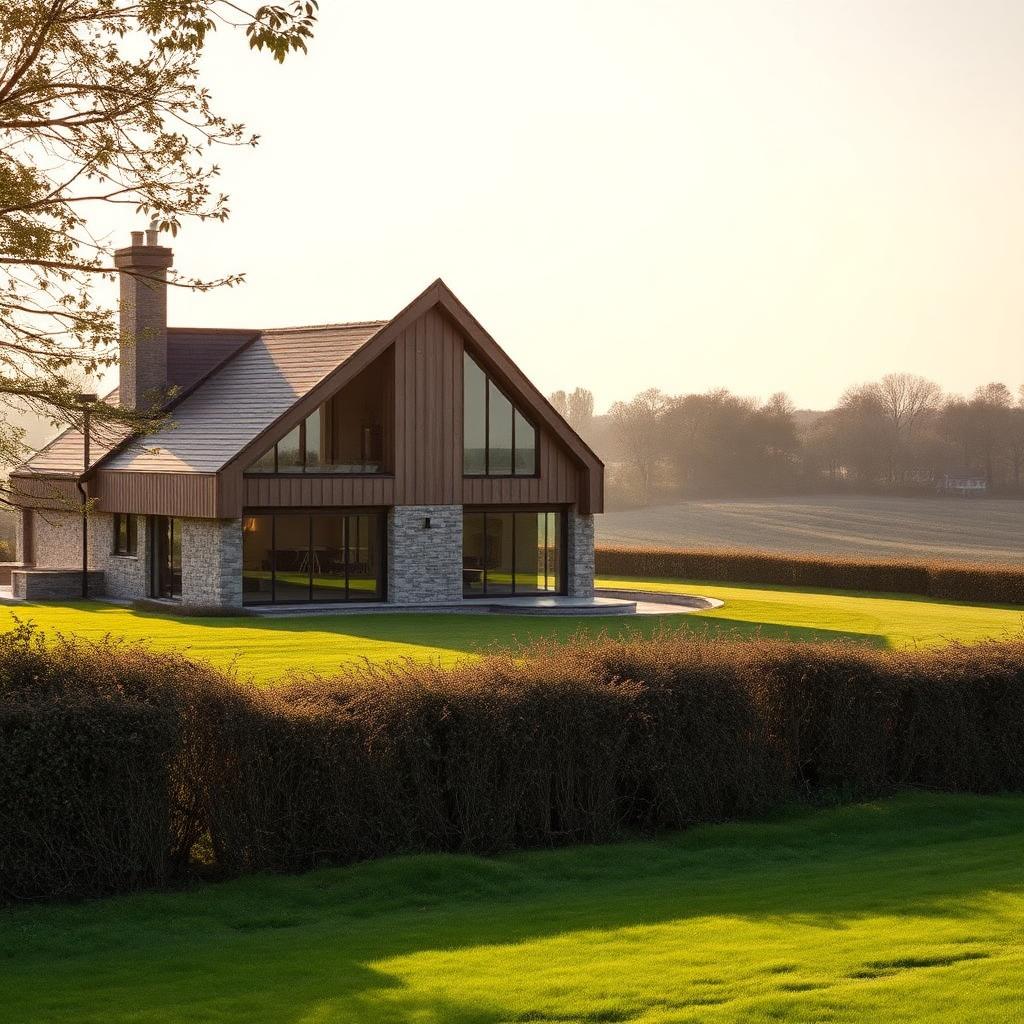
£809k residential mortgage against a non-standard Hertfordshire countryside home — placed with a private bank willing to underwrite the unusual construction and refinance the existing bridge in full.
£4m portfolio refinance for a Midlands property investment group — improving margin, releasing capital and consolidating multiple facilities into a single lender relationship.