
British expat arriving by London taxi at a Georgian townhouse UK mortgages for expats buying, remortgaging or returning to the UK

Expat Mortgages

UK expat mortgages.

In short: your residence, income currency and property use decide what lenders accept — check these before comparing rates.

Contributor and reviewer: James Caldwell

Get Your Finance Assessment

Two quick steps — a specialist will respond within one working day.

  • 40+ lendersWhole-of-market panel
  • 8–14 weeksTypical completion
  • Rated ExcellentClient reviews
  • No obligationFree initial review
£

An exact value lets us calculate your LTV straight away.

£

An exact figure lets us calculate LTV and indicative terms straight away.

Your figures

You're enquiring about a mortgage or remortgage for property in the United Kingdom, while living abroad.
Confidential — no obligation Rated 4.9 on Trustpilot

Last updated Reviewed by our Clifton International finance team.

In short

Can expats get a UK mortgage while living abroad?

Yes, a British expat can apply where their overseas residence, documented income and UK property plans meet lender criteria. Nationality alone does not establish eligibility. Explain whether you will return to occupy the home, let it to tenants or refinance an existing property, and disclose overseas borrowing and financial commitments.

  • Confirm country and income-currency eligibility before relying on a rate.
  • Prepare local tax, salary and residence evidence for the chosen lender.
  • Assess income in GBP; no universal currency haircut applies.
  • Check deposit transfers and UK purchase taxes separately from affordability.

At a glance

Key facts

Figures reviewed:

Loan size
£150k – £25m+
Loan-to-value
Up to 80% (case dependent)
Typical deposit
25% – 40%25% – 40% is typical; eligible 80% LTV products need a 20% deposit.
Term
Up to 30 years
Interest-only
Subject to criteria
Income currencies
Lender-specific
Typical timescale
8–14 weeksTime-critical purchase? Expat bridging can complete in around 3 – 5 weeks — see expat bridging finance.
Typical set-up costs
1.5% – 2.5% of loan (arrangement, valuation, legals)Excludes stamp duty; non-resident surcharges may apply.
Adviser response time
Within one working day

Indicative figures for guidance only, correct as at October 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.

Methodology and assumptions

  • Figures are compiled by Clifton International specialists from live lender term sheets, indicative quotes and completed transactions arranged over the preceding 12 months.
  • Rates and costs are stated as ranges rather than a single number because pricing is set case-by-case on borrower profile, residency, asset type, location and loan-to-value.
  • Timelines assume a complete document file from the outset; valuation, legal capacity and (in Spain) NIE and notary availability drive the critical path.
  • Costs exclude any lender, broker or third-party fees not stated on the page, and exclude currency movement between agreement and drawdown.
  • Figures are reviewed monthly and re-checked against lender pricing whenever a material market change occurs.

Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.

Start here

Which UK mortgage route fits you?

In short: your residence, the property’s use and whether you are returning to the UK decide the route — and the rates available.

Buying a UK home while living abroad
Usually suitsExpat residential mortgage
What lenders checkOverseas residence, income currency, deposit source, intended occupancy
Expat first-time buyer guide
Buying a UK rental property from abroad
Usually suitsExpat or limited company buy-to-let
What lenders checkExpected UK rent cover, tenancy, personal income and experience
Limited company buy-to-let for expats
Remortgaging UK property while abroad
Usually suitsExpat remortgage or product switch
What lenders checkExisting loan, property value, rental income or occupancy plans
Expat remortgage guide
Moving back to the UK
Usually suitsOften a UK resident mortgage
What lenders checkUK job offer or start date, return date, evidence of the move
Mortgages for returning expats
Foreign national living in the UK
Usually suitsUK resident mortgage subject to visa criteria
What lenders checkVisa or settled status, time in the UK, UK credit history
Australian nationals in the UK

Lenders vary. This is general guidance, not an offer of finance; the selected lender confirms its own criteria.

Coming home

Returning to the UK? Mortgages for returning expats

If you are moving back to the UK, you may not need an expat mortgage. We can often source mortgages at UK resident rates for returning expats — for example where you have a confirmed UK job offer or start date, a planned return date and evidence of the move. UK resident rates are usually lower than expat rates. Criteria vary by lender: some require a period of UK employment first, while others accept a contract signed before you return. Clifton International introduces applicants to lenders and brokers; it is not a lender.

  • Signed UK employment contract or offer letter with start date
  • Evidence of your return: flights, tenancy, school places or relocation letter
  • Recent overseas payslips and bank statements
  • Deposit source and transfer trail, including any foreign-currency savings

Lenders vary. This is general guidance, not an offer of finance; the selected lender confirms its own criteria.

Key figures

UK expat mortgage rates this month

Rates checked 2 November 2026 across 6 UK lenders that accept expat applicants. Based on a £300,000 loan, capital and interest.

Residential 2-year fixed, 75% LTV
from 5.64%*
typical 5.66%
Residential 5-year fixed, 75% LTV
from 5.63%*
typical 5.75%
Buy-to-let 2-year fixed, 75% LTV
from 5.69%*
typical 5.72%
Buy-to-let 5-year fixed, 75% LTV
from 5.54%*
typical 5.74%

Expat rate questions

What are UK expat mortgage rates this month?

As at 2 November 2026, 2-year fixed residential expat rates on our panel start from 5.54% at 60% LTV and 5.64% at 80% LTV, based on a £300,000 loan, capital and interest. Product fees may apply.

What is a typical expat buy-to-let rate?

For a 5-year fixed expat buy-to-let at 75% LTV, rates start from 5.54% with a typical rate of 5.74% across 5 lenders (2 November 2026).

Can expats get an interest-only mortgage?

Yes. Interest-only residential 2-year fixes at 75% LTV start from 5.85% as at 2 November 2026. You will need a credible plan to repay the balance at the end of the term.

*Product fees may apply. Indicative initial rates only; after the fixed term the rate reverts to the lender's variable rate. Source: published lender rate sheets for intermediaries, approved by Clifton International (2 November 2026). Not an offer of finance; your home may be repossessed if you do not keep up repayments on your mortgage.

Worked example

£300,000 expat mortgage on a £400,000 UK property

Example based on lender rates approved 2 November 2026. 75% LTV, £100,000 deposit, capital and interest over 25 years.

Monthly repayment on a £300,000 expat mortgage at approved rates
ProductLowest rate*Monthly repayment
Residential 2-year fixed5.64%£1,867
Residential 5-year fixed5.63%£1,866
Buy-to-let 2-year fixed5.69%£1,876
Buy-to-let 5-year fixed5.54%£1,849

As a buy-to-let on a 5-year fix, the rent needed would be approx. £1,731 per month — speak to our team to confirm.

*Product fees may apply. Indicative only, not a quote or offer. The rate reverts to the lender's variable rate after the initial fixed period. Your home may be repossessed if you do not keep up repayments on your mortgage.

Applying from overseas

Local documents. Sterling affordability.

In short: where you live sets the evidence you can supply; the selected lender decides what it accepts.

The mortgage is secured on UK property. Your country of residence determines which income, address and credit records you can supply; the selected lender decides what it accepts. These are preparation examples, not a universal checklist.

Applying from Australia? Start with UK mortgages for expats in Australia, then check AUD income and sterling affordability and the Australian mortgage documents checklist for ATO records, banking evidence and certification.

Paid in euros rather than pounds? UK mortgages with euro income covers euro-paid expats and UK residents, with income evidence by eurozone country.

Paid in US dollars? UK mortgages with US dollar income covers British expats in the US and UK residents paid in USD.

Evidence where you live and earn

Match payslips to salary credits and annual records: France’s avis d’impôt, Germany’s Lohnsteuerbescheinigung, Singapore’s IRAS assessment or Canada’s CRA Notice of Assessment. Keep address registration separate from residence permission and tax residence.

UK mortgages from France

Check the currency and pay components

Tell us your salary currency, not just where you hold savings. Separate Gulf basic pay from housing allowances and bonuses; show any Dutch expat-scheme benefit and its expiry. A dollar peg does not fix earnings in GBP, and there is no standard percentage income reduction.

Foreign-income and currency guidance

Trace the deposit and overseas commitments

Document savings, gifts, existing loans and the lawful transfer route. South African exchange-control checks and China’s remittance restrictions are separate from mortgage approval. Confirm lender-agreed translations and certification before ordering them.

South Africa income and deposit checks

Country guides below link to the relevant official authorities and document checklists. For UK purchase taxes, see HMRC’s non-resident SDLT guidance. Local tax guidance does not establish a lender’s acceptance policy.

Why clients choose us

Benefits at a glance

Country-specific preparation

Use the document checklist for your actual residence, from European tax records to Gulf salary certificates and Asian withholding statements.

Foreign-income checks

Confirm accepted currencies, sterling conversion and the treatment of salary, bonus and allowances for your individual application.

Approved indicative rates

Compare dated residential and personal buy-to-let products, with repayment and interest-only options subject to product eligibility.

Credit records explained

Present overseas borrowing and local credit evidence clearly where UK records are thin; no credit report guarantees approval.

Purchase or refinance

Separate residential occupancy, UK rental affordability and capital-raising needs so the proposed mortgage matches the property’s use.

Deposit planning

Prepare the origin-of-funds trail, transfer evidence and purchase-tax budget alongside the mortgage application.

Borrower eligibility

Who can qualify for a UK expat mortgage?

British expatriates living overseas, foreign nationals without UK residency, US persons, Gulf-based applicants and overseas landlords can each be introduced. What changes between them is the evidence a lender asks for, the deposit expected and the rate offered.

  • British expatriates living and working overseas
  • Foreign nationals purchasing UK property with no UK residency
  • US citizens and green card holders based in the UK or abroad
  • Expats based in the UAE, Saudi Arabia and the wider Gulf
  • Overseas landlords remortgaging or capital-raising on UK property
  • Borrowers purchasing through a UK limited company (SPV), subject to separate company and director checks

Typical lending criteria

UK expat mortgage deposits, loan sizes and terms

Most cases need a 25% to 40% deposit, with 80% loan-to-value available where the borrower qualifies. Loans typically run from £150,000 to £25m+ over terms up to 30 years, and accepted income currencies are lender-specific.

Loan size
£150k – £25m+
Loan-to-value
Up to 80% (case dependent)
Typical deposit
25% – 40%25% – 40% is typical; eligible 80% LTV products need a 20% deposit.
Term
Up to 30 years
Interest-only
Subject to criteria
Income currencies
Lender-specific
Typical timescale
8–14 weeksTime-critical purchase? Expat bridging can complete in around 3 – 5 weeks — see expat bridging finance.

Indicative only. Actual terms depend on borrower profile, asset and lender criteria.

Indicative expat mortgage rates

Market-leading fixed rates from our expat lender panel. The panel rate sheets were last checked and approved 2 November 2026; this article's content-review date is separate and shown with the reviewer credit. Choose your property type, fixed period, loan-to-value and loan size.

Property type
Fixed period
Repayment type
Loan-to-value

Residential · Capital & interest · 2-year fixed · up to 75% LTV

5.64% – 5.66%*

Lowest to typical rate available · 4 panel lenders qualify · property value approx. £666,667

After the 2-year initial product term ends, the rate reverts to the lender's variable rate unless you remortgage or switch to a new product.

Example monthly payment at the lowest rate: £3,112Capital and interest over 25 years.

How this rate comparison works

In short: for each combination you choose, we take the cheapest product from every panel lender that covers your loan size and loan-to-value. The lowest figure is the cheapest of those; the typical figure is the median across the qualifying lenders, so it reflects the middle of the panel rather than its best headline rate.

This comparison is supported by 4 qualifying panel lenders out of the 6 lenders on our expat panel.

Lender names are deliberately withheld: the underlying rate sheets are published for intermediaries, and named products are confirmed with you in a private recommendation, not in a public comparison. The date above is the rate-approval date — when the panel rate sheets were last checked and approved — and governs the figures only; this article's content-review date is checked separately and shown with the reviewer credit.

*Product fees may apply. Indicative only, based on published rates for international borrowers; not a quote, offer or recommendation. Eligibility, income currency, residency and property type affect the rate available.Your home may be repossessed if you do not keep up repayments on your mortgage.

Earning in euros? See UK mortgages with euro income — for eurozone expats and UK residents paid in EUR. Paid in dollars? See UK mortgages with US dollar income.

Send these details to a specialist — we'll confirm the best available rate within one working day.

Enquire with these details

Purchase versus remortgage for expats

In short: a purchase centres on deposit and affordability; a remortgage centres on the existing loan, current value and how the property is used now.

Main purpose
PurchaseFund a new UK home or rental
RemortgageReplace an expiring deal, switch lender or raise capital
Deposit / equity
PurchaseDeposit funds and source-of-funds trail
RemortgageEquity from current valuation and loan balance
Property use
PurchasePlanned occupancy or letting
RemortgageCurrent use — a former home now let may need a buy-to-let product
Purchase taxes
PurchaseSDLT, including any non-resident surcharge
RemortgageNo SDLT on a straight remortgage
Timing
Purchase8–14 weeks indicative, linked to the sale chain
RemortgageStart 3–6 months before your fixed rate ends

Lenders vary. This is general guidance, not an offer of finance; the selected lender confirms its own criteria.

Overseas income types and typical evidence

In short: basic salary is the most widely accepted; allowances, bonuses and self-employed income need stronger evidence and may be partly counted.

Basic salary
Typical evidenceContract, 3–6 months’ payslips, bank credits, local tax record
Lender treatmentUsually accepted, converted to GBP
Contractual allowances
Typical evidenceContract or salary certificate itemising housing and other allowances
Lender treatmentSometimes included where guaranteed
Bonus and commission
Typical evidenceTwo years’ history and payslips
Lender treatmentOften averaged or partly counted
Self-employed / company director
Typical evidenceTwo to three years’ accounts and local tax returns
Lender treatmentFewer lenders; longer trading history needed
UK rental income
Typical evidenceTenancy agreement and rent statements
Lender treatmentAssessed against rental cover for buy-to-let

Lenders vary. This is general guidance, not an offer of finance; the selected lender confirms its own criteria.

Foreign-currency income and sterling repayments

In short: if you earn in another currency, a weaker exchange rate raises the cost of each sterling repayment.

Lenders convert your income to GBP when assessing affordability and may apply their own adjustment. After completion, repayments stay in sterling, so currency movements change what you pay in your own currency. Plan a buffer and consider how you will transfer funds — see our currency exchange for UK property page and the UK currency hub.

Buying from overseas

Use bridging finance to secure the property, then exit onto an expat mortgage.

If a UK property cannot wait for a standard expat mortgage timescale, bridging finance may let an overseas buyer complete without making the purchase conditional on that mortgage. It can put you in a cash-buyer position for the transaction, although the purchase is still being funded by a secured loan.

1

Secure the property

A short-term bridge can fund the UK purchase before the longer expat mortgage process has completed, allowing you to proceed in a cash-buyer position.

2

Complete the expat mortgage

The longer-term application continues with the lender assessing overseas residency, foreign-currency income, documents and the property.

3

Repay the bridge

Once the expat mortgage completes, its proceeds repay the bridging loan and move the borrowing onto the intended longer-term arrangement.

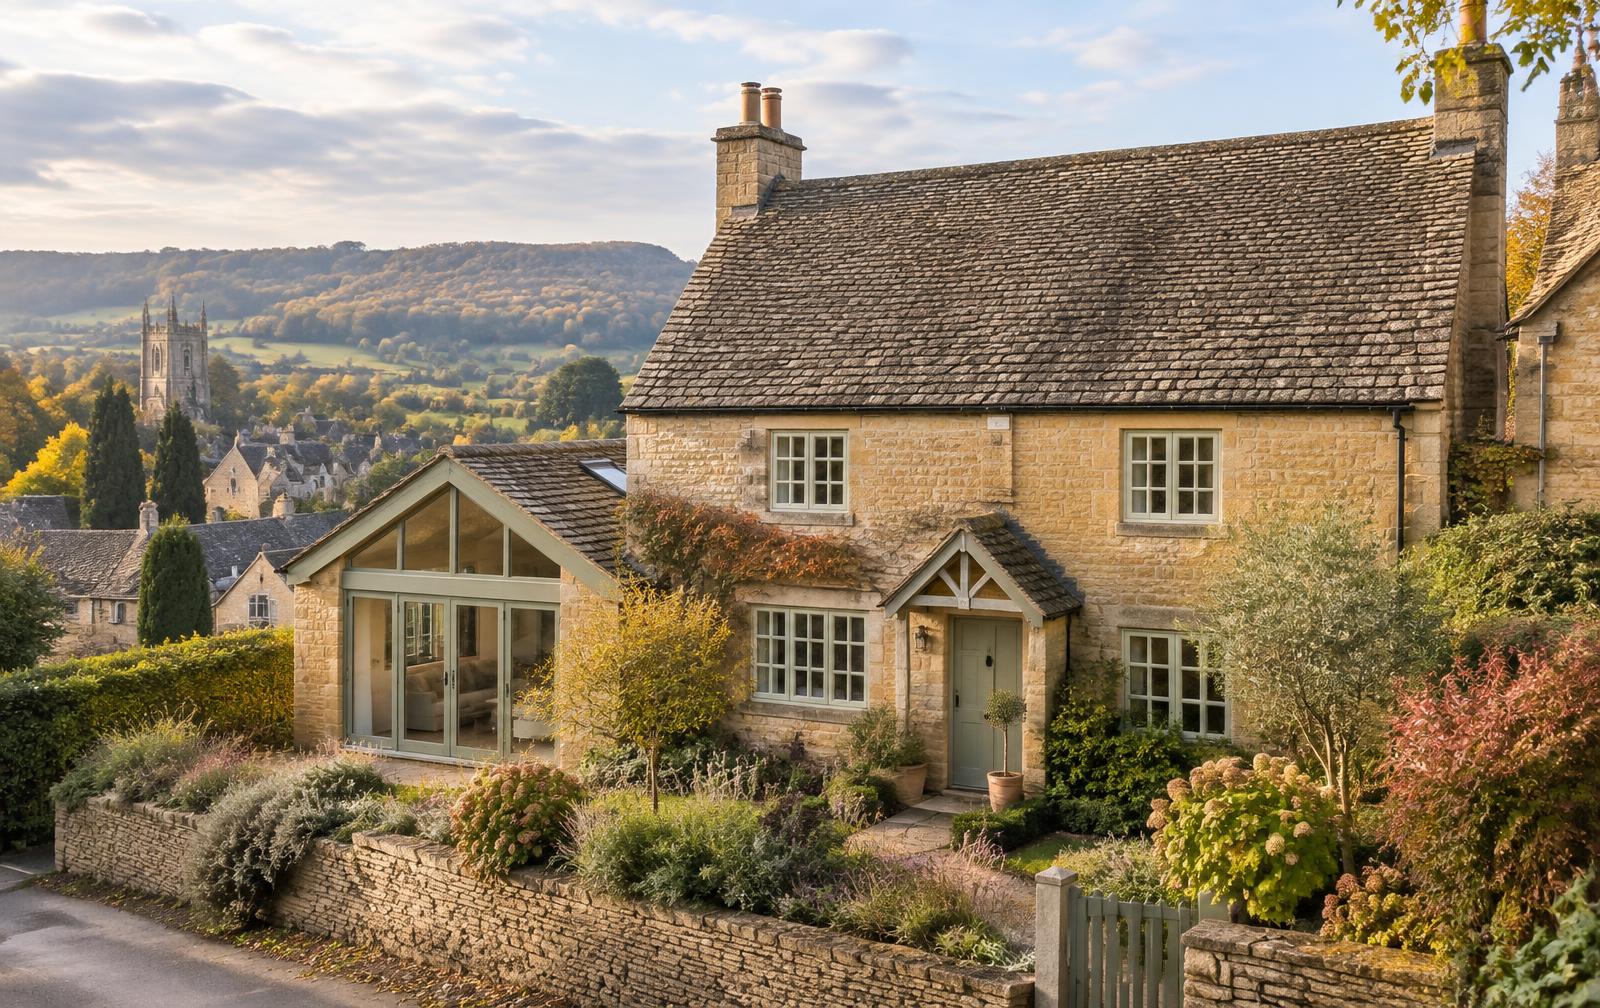
Cotswold stone cottage with a glass extension in Painswick, the property in the case studyCase study

A real example

£500k Cotswolds bridge for a couple based overseas

A UK national and an Australian national working in Hong Kong used a regulated bridge at around 50% LTV to secure a Painswick cottage before their existing home was sold.

Read the case study

The expat mortgage must be assessed as a credible exit before entering the bridge. Bridging finance is short term and normally more expensive than a mortgage; approval, timing and the eventual mortgage terms are not guaranteed. Clifton International is an introducer, not a lender or adviser, and does not handle client funds.

Recent transactions

Case studies from our files

Published transactions from our own case study library — select any to read the full brief.

Contributor

Portrait of James Caldwell

James Caldwell

Director

LinkedIn profile
  • Co-founder
  • 26+ years in business and finance
  • Property finance specialist

James co-founded Clifton and has spent more than a decade building a specialist property finance business covering residential mortgages, bridging, development finance and complex international cases.

Can I get a UK buy-to-let mortgage while living abroad?

Yes. Selected lenders consider overseas applicants buying or refinancing UK rental property. They assess the property’s expected rent against their rental stress test, alongside your circumstances, ownership structure and any required income evidence. Residential affordability examples on this site are not buy-to-let borrowing calculations; loan size needs a separate assessment.

Personal ownership or a UK limited company?

With personal ownership, you own the property and borrow as an individual or joint applicant. With a UK limited company, usually a special purpose vehicle (SPV), the company owns the property and borrows; lenders commonly require personal guarantees from directors. Company and non-resident director eligibility are assessed separately, so a personal-name option does not establish availability for a company.

A company is not automatically the better choice. Consider tax on rental profits and on money taken out of the company, accounting costs, future sale plans and the available mortgages. Moving a personally owned property into a company can create tax and transaction costs. Take coordinated UK and local tax advice first. Read our limited-company buy-to-let guide for expats and the official guide to setting up a UK limited company.

Managing a UK rental property from overseas

Agree who handles tenant checks, rent collection, inspections, repairs and emergencies while you are abroad. A UK managing agent provides local support but does not remove your responsibilities as landlord. Budget for management fees, maintenance, insurance, service charges and empty periods, and keep a GBP reserve. Check licensing, safety and deposit-protection rules for the property’s UK nation and council, starting with GOV.UK’s landlord responsibilities guidance.

How does the Non-resident Landlord Scheme work?

For an individual landlord whose usual place of abode is outside the UK, the Non-resident Landlord Scheme governs how tax is collected on UK rent. Its definition is separate from ordinary tax residence. Unless HMRC authorises payment without deduction, your letting agent—or a tenant where the scheme requires it—must deduct tax and pay it to HMRC. Approval to receive rent gross does not make the income tax-free; you still declare it. Company landlords have separate rules. See HMRC’s rental-income guidance for people living abroad and the Non-resident Landlord Scheme guidance and forms.

Remortgaging or raising money on a UK let you already own

Overseas landlords can review a remortgage before a fixed rate ends, or raise capital where rent and value support it. Lenders need the current balance, tenancy details and the purpose of any extra borrowing. See the expat remortgage guide.

General information, not tax, legal or investment advice. Your obligations in your country of residence depend on your circumstances; take advice in both countries.

Short-term option · indicative

Need to move quickly? Bridging finance for expats

A standard expat mortgage takes around eight to fourteen weeks. When a deadline won’t wait — an auction completion, a chain break, buying before an overseas sale settles, or refurbishing before letting — UK bridging finance can be faster. It is underwritten on the UK security and a documented exit rather than monthly affordability.

  • Speed: around 3–5 weeks from application to completion.
  • Indicative cost: around 0.65%–1.00% per month, plus fees.
  • Loan-to-value: usually up to about 70% of the UK property’s value.
  • Exit: planned from day one — usually a refinance onto a term expat mortgage, or a sale.

Bridging is short-term lending, not a replacement for a mortgage, and needs its own suitability and exit assessment. Read UK bridging loans for expats and non-residents for criteria and documents.

Published expat case studies

The example structures shown above are illustrative scenarios. For published cases with their source and limitations stated, read:

Where do the figures on this page come from?

  • Loan sizes, loan-to-value, deposits, terms and timescales are Clifton International’s approved indicative ranges, not live lender offers. See our key facts methodology.
  • Mortgage rates in the rate tool are approved indicative figures with their own approval date, not quotes.
  • Bridging figures are the approved indicative ranges on our expat bridging page.
  • Stamp duty follows HMRC’s SDLT guidance for non-UK residents, checked 30 October 2026.
  • Rental tax follows HMRC’s Non-resident Landlord Scheme guidance linked in the buy-to-let section.
  • Example structures are illustrative scenarios, not specific client transactions or quotes.

Frequently asked

Questions from clients

What is an expat mortgage?

An expat mortgage is a mortgage secured on UK property for an applicant living abroad. It can fund a residential purchase, a UK buy-to-let or a remortgage, subject to the lender accepting your country of residence, income currency and intended property use. It is not a mortgage on your overseas home. Clifton International introduces applicants to lenders and brokers; it is not a lender.

Can an expat get a UK mortgage while living abroad?

Yes, a British expat can apply where their overseas residence, documented income and UK property plans meet lender criteria. Nationality alone does not establish eligibility. Explain whether you will return to occupy the home, let it to tenants or refinance an existing property, and disclose overseas borrowing and financial commitments.

Which UK banks offer expat mortgages?

Possible routes include international banking divisions, specialist building societies and private banks. Their country, currency, loan-size and property criteria differ, so the lowest advertised rate is not necessarily available to you. Our lender-types comparison explains these routes; the approved rate tool shows lender-anonymous indicative products, not a promise of acceptance.

How much deposit do I need for a UK expat mortgage?

A 25–40% deposit is an indicative starting point, not a universal minimum. Some eligible products reach 80% loan-to-value, meaning a 20% deposit, but residence, currency, repayment method, loan size and property criteria can reduce the maximum. Budget separately for purchase taxes, legal costs and product fees. A gifted or overseas deposit also needs a documented source and transfer trail.

Can I get a UK mortgage with foreign-currency income?

Potentially. Lenders must accept both your residence and the currency in which you earn, then assess income and commitments in GBP. EUR, USD, AUD, CAD, NZD, CHF, SGD, HKD and Gulf currencies need individual checks; no currency is accepted by every lender. There is no universal 10–25% income haircut: the conversion rate, any adjustment and treatment of bonus or allowances depend on the selected lender. GBP savings do not change your salary currency.

What documents do I need to apply for a UK expat mortgage?

Prepare identity, current overseas address and residence-status evidence, an employment contract and payslips or self-employed accounts, relevant local tax records, bank statements showing income credits, existing-debt statements and a source-of-deposit trail. Examples include Australian ATO records, Canadian CRA Notices of Assessment, Singapore IRAS Notices of Assessment and French avis d’impôt. The lender confirms the document list and periods; a passport or tax number alone does not prove every aspect of residence.

What local documents do lenders ask for in Europe?

Examples include Spanish Modelo 100 returns and address evidence, French avis d’impôt and justificatif de domicile, Irish Revenue Employment Detail Summaries or Form 11, German Lohnsteuerbescheinigung and Steuerbescheid, Dutch jaaropgaaf and BRP registration, and Swiss Lohnausweis salary certificates with actual permit evidence. Tax records, address registration and immigration status are different checks. Local credit reports may be requested, but do not replace the lender’s UK assessment.

How do UK expat mortgages work for Gulf-based applicants?

For applicants in Dubai, Doha, Riyadh, Kuwait, Bahrain or Muscat, lenders may ask for a salary certificate, employment contract, payslips, bank credits and current residence evidence such as a Qatar ID, Kuwait Civil ID or Oman resident card. Separate basic pay, contractual housing allowances and discretionary bonuses. Where employment income is not subject to local personal income tax, explain the evidence available rather than inventing a tax return. A dollar peg does not eliminate GBP currency risk; Kuwait’s dinar uses a currency basket rather than a dollar-only peg.

What additional checks apply to applicants in Japan, China and South Africa?

Japan-based applicants may need a gensen chōshūhyō withholding certificate reconciled with current JPY pay and lender-agreed translations. For mainland China, CNY/RMB affordability and a lawful deposit-remittance route are separate checks; the US$50,000 facilitation allowance is not general permission to fund an overseas property purchase. South Africa-based applicants should confirm applicable SARB and SARS requirements with their bank or Authorised Dealer and tax adviser. Transfer permission never guarantees UK mortgage eligibility.

Do overseas documents need certified translations or an apostille?

Ask the selected lender which originals, certified copies, certifiers and English translations it accepts before paying for them. An apostille authenticates a public document’s origin; it is not a translation and is not required for every mortgage application. Local authentication procedures differ. Use the country checklist and the lender’s instructions rather than assuming a British embassy will certify mortgage documents.

Can I get a UK mortgage without a UK credit history?

A thin or inactive UK credit file does not automatically rule out a mortgage, but it can narrow the options. A lender may request local credit evidence, banking references and current borrowing statements alongside income and assets. For example, SCHUFA in Germany, BKR in the Netherlands and Ireland’s Central Credit Register are local records, not substitutes for UK underwriting. Disclose adverse credit and overseas debts.

Can expats get a UK buy-to-let mortgage or remortgage?

Both may be possible subject to overseas-residence and lender criteria. Buy-to-let assessment considers expected UK rent, the property and tenancy, with personal-income requirements checked separately. A remortgage also needs the existing mortgage balance and any capital-raising purpose. UK limited-company buy-to-let has separate company, director and ownership checks; personal-name rates are not company mortgage quotes.

Does living abroad affect Stamp Duty on a UK purchase?

It can. HMRC charges an extra 2% Stamp Duty Land Tax on residential purchases in England and Northern Ireland when any buyer is non-UK resident for the purchase. An individual is non-UK resident for this test if they were not in the UK at the end of at least 183 days in the 12 months before the purchase; days anywhere in the UK count, and the test is separate from nationality and ordinary tax residence. Married couples and civil partners buying together, and not separated, are both treated as UK resident if either meets the test. If you later spend at least 183 days in the UK in a continuous 365-day period between 364 days before and 365 days after the purchase date, you may be able to claim a refund within two years of the purchase; with joint buyers, every buyer must meet this rule. The surcharge does not apply in Scotland or Wales, which have their own property taxes. Higher rates for additional properties may apply separately if you already own residential property anywhere. Your solicitor should confirm the position.

Can returning expats get UK resident mortgage rates?

If you are moving back to the UK, you may not need an expat mortgage. We can often source mortgages at UK resident rates for returning expats — for example where you have a confirmed UK job offer or start date, a planned return date and evidence of the move. UK resident rates are usually lower than expat rates. Criteria vary by lender: some require a period of UK employment first, while others accept a contract signed before you return. Clifton International introduces applicants to lenders and brokers; it is not a lender.

Can foreign nationals and US citizens get a UK mortgage?

Some lenders consider foreign nationals and US persons, but the panel depends on nationality, actual residence, income currency, UK property use and compliance requirements. FATCA-related checks can narrow options for US citizens or green card holders. A larger deposit or private-bank relationship does not guarantee approval; confirm a suitable lender route before committing to a purchase.

How long does a UK expat mortgage take?

Eight to fourteen weeks is an indicative planning range, not a completion promise. The lender, valuation, legal work, overseas identity checks and document preparation determine the timetable. Confirm translation and certification instructions early and reconcile income with bank credits before applying. Short-term bridging finance requires a separate suitability and exit assessment; it is not an automatic solution to a mortgage delay.

Currency exchange

Earning overseas? Your deposit is exposed until it’s in sterling.

Expat buyers moving dollars, dirhams, riyals or euros into the UK can lose thousands to bank margins and rate moves. We introduce you to an FCA-authorised currency specialist who plans your transfer around exchange and completion.

  • Forward contracts to fix your sterling deposit before completion
  • Better-than-bank rates on large one-off and regular transfers
  • Flexible contact across time zones with a dedicated specialist

Clifton introduces clients to a specialist currency partner and does not hold, convert or transfer client funds.

Guides by country of residence

In short: criteria, deposits and documentation differ by where you live, so start with your jurisdiction before comparing rates.

Criteria, deposits and documentation differ by where you live. Start with your jurisdiction. For the basics, read our UK expat finance FAQs — currency conversion, deposit rules and residency evidence in one place — or the longer UK expat finance guide, which covers the same ground in more depth. For lender routes and current panel rates, see our which UK banks lend to expats comparison. Already own UK property? Read the expat remortgage guide or limited company buy-to-let for expats. Buying your first home? Expat first-time buyer guide. Need short-term finance secured on UK property? See bridging loans for expats and non-residents.

Ready to explore your options?

Speak to a UK property finance specialist.

A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.