American flag hanging outside a period UK townhouse UK mortgages for US citizens and expats living in the United States

Expat Mortgages

UK mortgages for US citizens and expats.

In short: British expats living in the US and US citizens can be considered for UK mortgages on verified USD income, with borrowing up to 75% LTV; acceptance depends on nationality, residency and lender checks.

Contributor and reviewer: James Caldwell

Get Your Finance Assessment

Two quick steps — a specialist will respond within one working day.

  • 40+ lendersWhole-of-market panel
  • 8–14 weeksTypical completion
  • Rated ExcellentClient reviews
  • No obligationFree initial review
£

An exact value lets us calculate your LTV straight away.

£

An exact figure lets us calculate LTV and indicative terms straight away.

Your figures

You're enquiring about a mortgage or remortgage for property in the United Kingdom, while living abroad.
Confidential — no obligation Rated 4.9 on Trustpilot

Last updated Reviewed by our Clifton International finance team.

In short

Can British expats living in the US and US citizens get a UK mortgage?

Yes. UK mortgage options are available for British expats living in the US and for US citizens, subject to lender eligibility. Specialist lenders can consider USD income, with borrowing up to 75% of the property's value within our approved indicative criteria. Nationality, residency and financial circumstances affect the options available; a well-documented application typically takes 8–14 weeks.

  • Salary, bonus and RSU income in USD can be included in affordability.
  • Buy-to-let and residential purchases are both available.
  • Limited-company and SPV buy-to-let structures are commonly considered.
  • US tax reporting does not prevent a UK mortgage with lenders that accept US persons.
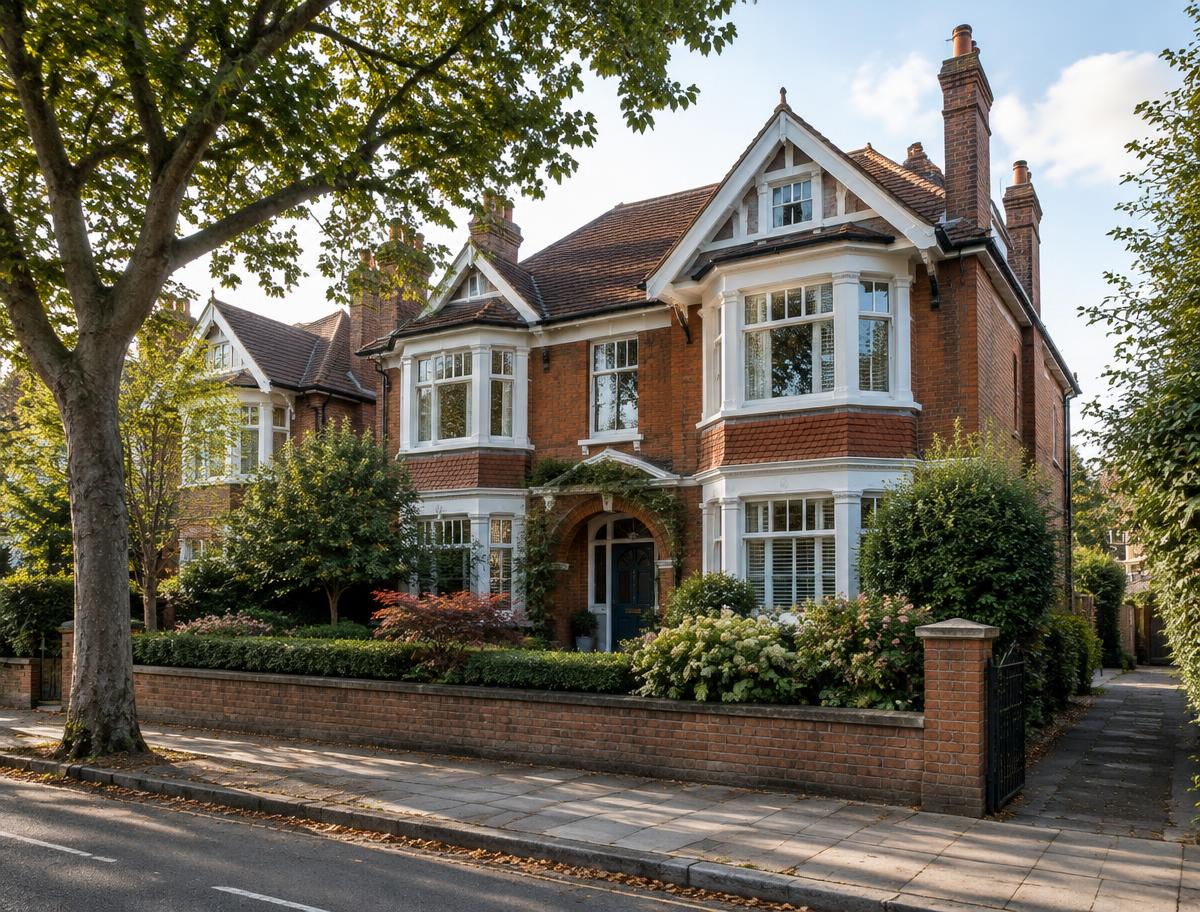
Illustrative Victorian red-brick townhouse on a leafy Oxford street — UK buy-to-let remortgage for expats in the US paid in dollars; not the clients' actual property

British expat route · Oxford · US-based expats

£380,000 buy-to-let remortgage for UK expats in the US paid in dollars

A married couple living in San Francisco, paid largely in US dollars, remortgaged their Oxford buy-to-let — valued at approximately £1.29 million — and raised £380,000 through a lender experienced in expat and foreign-currency income.

This case shows British expats in the US with dollar income; it does not by itself establish lender acceptance of US citizens or green card holders. Source: the anonymised case-study account supplied by Clifton Private Finance. Figures and outcomes are reported case facts, not independently audited market data. Clifton International presents the account as an introducer, not as lender or mortgage adviser.

Photo: illustrative, not the clients' actual property. A reported outcome, not a promise of comparable terms.

Read the full case study
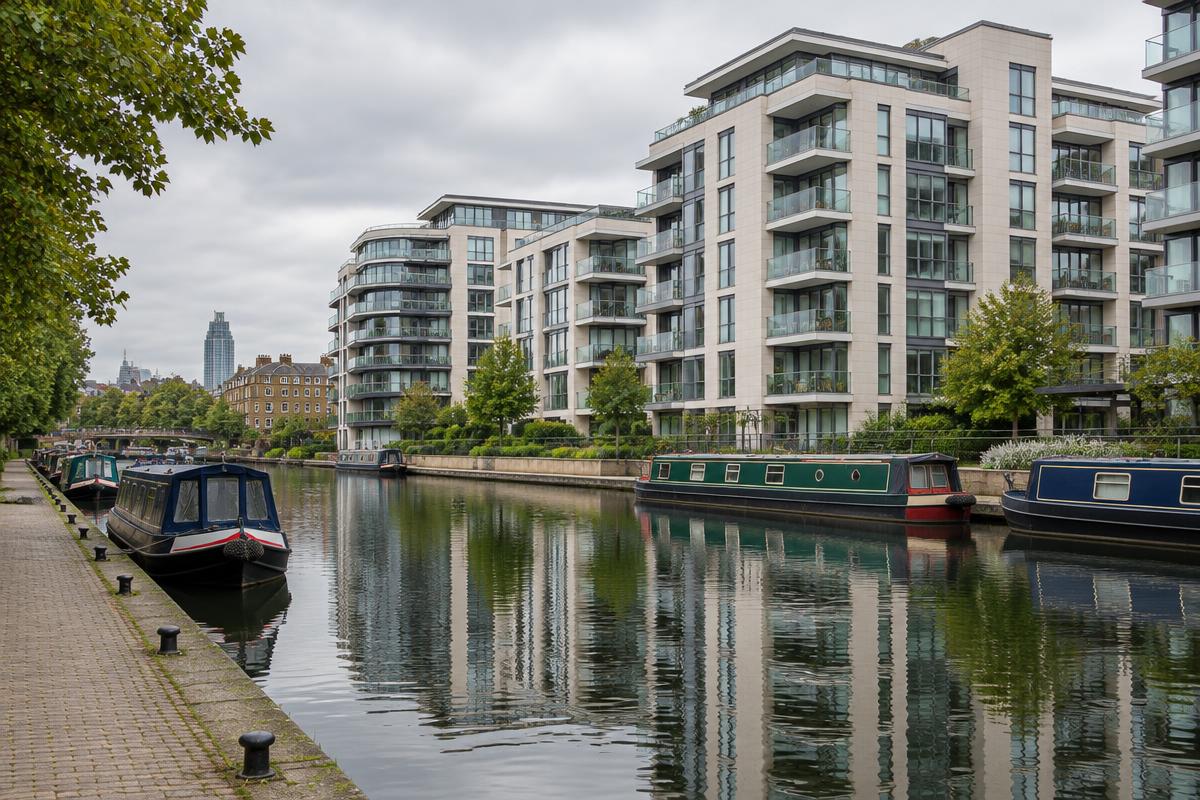
Illustrative modern canal-side apartment buildings at Paddington Basin, London — not the clients' actual property

US citizen route · Paddington · US citizens

£500,000 mortgage for US citizens buying a second home in Paddington, London

Clifton Private Finance’s account reports a £500,000 UK mortgage for a married American couple buying a new-build second home in Paddington, London, valued at approximately £1.6 million, with both applicants employed in the US and paid in US dollars.

This case shows US citizens buying a London second home with dollar income; substantial equity supported the reported outcome and it does not by itself establish deposit or eligibility requirements for every American buyer. Source: Clifton Private Finance, ‘Mortgage Secured for US Nationals Purchasing Second Home in the UK’. Clifton Private Finance is the arranging team named in the account. Clifton International publishes an attributed, adapted summary only and did not arrange this transaction. Figures are reported case facts, not independently audited data.

Photo: illustrative, not the clients' actual property. A reported outcome, not a promise of comparable terms.

Read the full case study
UK mortgages for British expats living in the US

If you are British and live in the United States, specialist expat mortgage options may help you buy a UK home, invest in buy-to-let property or remortgage a property you already own. Lenders assess your overseas residence, USD income, employment arrangements, deposit and the UK property. British nationality alone does not guarantee eligibility.

Living in the US does not make you a US citizen, although green-card status or US tax residence can bring US-person reporting requirements. Your adviser needs to establish both your nationality and your residency or tax status before selecting suitable lenders.

The Oxford remortgage case above illustrates this British-expat route: British expats living in San Francisco and paid in US dollars raised finance against their UK property. It is not evidence of eligibility for US citizens or green card holders.

UK mortgages for US citizens buying UK property

If you are a US citizen, UK residential, buy-to-let and remortgage options may be available with lenders that accept US persons. Some lenders decline these applications because of FATCA reporting requirements, so the choice of lender can differ from the British-expat route. US citizenship and where you live must both be considered; acceptance is lender-specific.

A specialist adviser can check lender eligibility before an application and explain how your USD income, US documents, deposit and proposed property ownership will be assessed. US citizens and green card holders should also coordinate UK and US tax advice. The Paddington second-home case above is a reported US-citizen purchase with dollar income; the purchase examples further down this page are illustrative, not completed client transactions.

At a glance

Key facts

Figures reviewed:

Loan size
£200k – £25m+
Maximum loan-to-value
Up to 75%Planning range; typical deposits are 25%–35% for residential and 25%–40% for buy-to-let. Budget separately for taxes and fees.
Income considered
USD, GBP, EURAcceptance and any sterling conversion adjustment depend on the selected lender.
Purposes
Purchase, buy-to-let, remortgage
Indicative timescale
8–14 weeksFrom a complete application; valuation, legal work, FATCA onboarding and certified US documents can affect completion.
Mortgage pricing
See the approved monthly rates belowDated indicative products, not a US-specific offer or an individual quote.
Fees and purchase costs
Confirm for your transactionBudget separately for product fees, valuation, legal costs, SDLT and currency transfers; no generic all-in percentage applies.

Indicative figures for guidance only, correct as at October 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.

Methodology and assumptions

  • Loan size, deposit, LTV and completion figures are approved indicative preparation assumptions, not official statistics, guaranteed eligibility or live lender offers.
  • Mortgage pricing comes only from the published, approved monthly snapshot below, with its own reference and approval dates; it is not a whole-market comparison or confirmation that each product accepts a US-based applicant or US person.
  • HMRC guidance supports UK SDLT, the non-resident surcharge and landlord-tax rules; IRS FATCA guidance explains reporting obligations. Neither source sets finance terms or lender acceptance.
  • Editorial review dates are separate from the monthly financial approval dates.

Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.

Key figures

UK expat mortgage rates this month

Rates checked 2 November 2026 across 6 UK lenders that accept expat applicants. Based on a £300,000 loan, capital and interest.

Residential 2-year fixed, 75% LTV
from 5.64%*
typical 5.66%
Residential 5-year fixed, 75% LTV
from 5.63%*
typical 5.75%
Buy-to-let 2-year fixed, 75% LTV
from 5.69%*
typical 5.72%
Buy-to-let 5-year fixed, 75% LTV
from 5.54%*
typical 5.74%

Expat rate questions

What are UK expat mortgage rates this month?

As at 2 November 2026, 2-year fixed residential expat rates on our panel start from 5.54% at 60% LTV and 5.64% at 80% LTV, based on a £300,000 loan, capital and interest. Product fees may apply.

What is a typical expat buy-to-let rate?

For a 5-year fixed expat buy-to-let at 75% LTV, rates start from 5.54% with a typical rate of 5.74% across 5 lenders (2 November 2026).

Can expats get an interest-only mortgage?

Yes. Interest-only residential 2-year fixes at 75% LTV start from 5.85% as at 2 November 2026. You will need a credible plan to repay the balance at the end of the term.

*Product fees may apply. Indicative initial rates only; after the fixed term the rate reverts to the lender's variable rate. Source: published lender rate sheets for intermediaries, approved by Clifton International (2 November 2026). Not an offer of finance; your home may be repossessed if you do not keep up repayments on your mortgage.

Worked example

£300,000 expat mortgage on a £400,000 UK property

Example based on lender rates approved 2 November 2026. 75% LTV, £100,000 deposit, capital and interest over 25 years.

Monthly repayment on a £300,000 expat mortgage at approved rates
ProductLowest rate*Monthly repayment
Residential 2-year fixed5.64%£1,867
Residential 5-year fixed5.63%£1,866
Buy-to-let 2-year fixed5.69%£1,876
Buy-to-let 5-year fixed5.54%£1,849

As a buy-to-let on a 5-year fix, the rent needed would be approx. £1,731 per month — speak to our team to confirm.

*Product fees may apply. Indicative only, not a quote or offer. The rate reverts to the lender's variable rate after the initial fixed period. Your home may be repossessed if you do not keep up repayments on your mortgage.

Indicative expat mortgage rates

Market-leading fixed rates from our expat lender panel. The panel rate sheets were last checked and approved 2 November 2026; this article's content-review date is separate and shown with the reviewer credit. Choose your property type, fixed period, loan-to-value and loan size.

Property type
Fixed period
Repayment type
Loan-to-value

Residential · Capital & interest · 2-year fixed · up to 75% LTV

5.64% – 5.66%*

Lowest to typical rate available · 4 panel lenders qualify · property value approx. £666,667

After the 2-year initial product term ends, the rate reverts to the lender's variable rate unless you remortgage or switch to a new product.

Example monthly payment at the lowest rate: £3,112Capital and interest over 25 years.

How this rate comparison works

In short: for each combination you choose, we take the cheapest product from every panel lender that covers your loan size and loan-to-value. The lowest figure is the cheapest of those; the typical figure is the median across the qualifying lenders, so it reflects the middle of the panel rather than its best headline rate.

This comparison is supported by 4 qualifying panel lenders out of the 6 lenders on our expat panel.

Lender names are deliberately withheld: the underlying rate sheets are published for intermediaries, and named products are confirmed with you in a private recommendation, not in a public comparison. The date above is the rate-approval date — when the panel rate sheets were last checked and approved — and governs the figures only; this article's content-review date is checked separately and shown with the reviewer credit.

*Product fees may apply. Indicative only, based on published rates for international borrowers; not a quote, offer or recommendation. Eligibility, income currency, residency and property type affect the rate available.Your home may be repossessed if you do not keep up repayments on your mortgage.

Earning in euros? See UK mortgages with euro income — for eurozone expats and UK residents paid in EUR. Paid in dollars? See UK mortgages with US dollar income.

Send these details to a specialist — we'll confirm the best available rate within one working day.

Enquire with these details

Why clients choose us

Benefits at a glance

FATCA-ready lenders

A working panel of UK private banks and specialist lenders that accept US citizens and green card holders as a matter of course.

USD income considered

Salary, bonus, RSU and partnership income in US dollars can be considered. Whether it is accepted, and any sterling conversion adjustment, depends on the lender.

Options with limited UK credit history

Some lenders may consider documented income, assets and US banking references where there is little or no UK credit footprint. Acceptance depends on the lender and your full circumstances.

US structures understood

LLCs, revocable trusts and family partnerships placed with lenders that already review US beneficial-ownership documentation.

SDLT surcharge planning

Clear guidance on the 2% non-resident and 5% additional-property surcharges before you commit to an offer.

US time-zone service

Advisers available across Eastern and Pacific hours, with scheduled calls and document handling that fits your working day.

Borrower eligibility

Who we can help

  • US citizens and green card holders purchasing UK property
  • British expatriates living and working in the United States
  • US-based landlords remortgaging or capital raising on UK property
  • Self-employed US applicants filing Schedule C or K-1 income
  • Buyers purchasing through a UK SPV, US LLC or family trust
  • US buyers needing short-term bridging ahead of a term mortgage

Typical lending criteria

Indicative parameters

Loan size
£200k – £25m+
Loan-to-value
Up to 75%
Typical deposit
25% – 35%
Term
Up to 30 years
Interest-only
Available
Income considered
USD, GBP, EUR
Typical timescale
8–14 weeksTime-critical purchase? Expat bridging can complete in around 3 – 5 weeks — see expat bridging finance.

Indicative only. Actual terms depend on borrower profile, asset and lender criteria.

How many UK homes are owned from the US?

In 2024, 12,405 homes in England and Wales were registered to owners with a US address — up 5.5% on the year before. That made the United States the third-largest overseas group, behind Hong Kong and Singapore, with 6.5% of the 189,793 homes held from overseas addresses.

Homes with a US address
12,405
Change on previous year
+5.5%
Share of overseas-held homes
6.5% (ranked 3)

These figures count titles in England and Wales registered to individuals with a US correspondence address. They are not a count of US citizens: they include British expats living in the US and exclude US citizens with a UK address. Source: Benham and Reeves, ‘Hong Kongers still most dominant foreign nation in the property market’, published 17 January 2025, based on a freedom of information request to HM Land Registry. Not official statistics and not an indication of finance availability in any area.

Which official sources explain these rules?

These sources explain tax and reporting rules; they do not set lender criteria or finance terms.

Do I need a specialist mortgage adviser or broker as a US citizen or US-based expat?

Yes. We strongly recommend independent, specialist advice. Many UK lenders decline US citizens and green card holders because of FATCA reporting. Others treat US dollar income, RSUs or K-1 partnership income differently, or do not offer mortgages to applicants living abroad. A specialist expat mortgage broker understands which lenders accept US persons and how each assesses dollar income, helping you avoid unsuitable applications and unnecessary credit searches.

Clifton International is an introducer, not a lender or mortgage adviser. We introduce you to Clifton Private Finance, an independent, whole-of-market mortgage adviser with access to 40+ lenders. They review your circumstances, compare lenders that accept US-based applicants, and recommend the most suitable option in writing. Clifton Private Finance's published terms state that it is an appointed representative of Fair Investment Company Limited, which is authorised and regulated by the Financial Conduct Authority, and give Clifton Private Finance's FCA registration number as 766063. Check its current status on the FCA Register.

Your home may be repossessed if you do not keep up repayments on your mortgage.

Sources: Clifton Private Finance terms of business · FCA Register.

Paid in dollars but not a US citizen, or living in the UK on USD income? See UK mortgages with US dollar income.

Buying from overseas

Use bridging finance to secure the property, then exit onto an expat mortgage.

If a UK property cannot wait for a standard expat mortgage timescale, bridging finance may let an overseas buyer complete without making the purchase conditional on that mortgage. It can put you in a cash-buyer position for the transaction, although the purchase is still being funded by a secured loan.

1

Secure the property

A short-term bridge can fund the UK purchase before the longer expat mortgage process has completed, allowing you to proceed in a cash-buyer position.

2

Complete the expat mortgage

The longer-term application continues with the lender assessing overseas residency, foreign-currency income, documents and the property.

3

Repay the bridge

Once the expat mortgage completes, its proceeds repay the bridging loan and move the borrowing onto the intended longer-term arrangement.

Cotswold stone cottage with a glass extension in Painswick, the property in the case studyCase study

A real example

£500k Cotswolds bridge for a couple based overseas

A UK national and an Australian national working in Hong Kong used a regulated bridge at around 50% LTV to secure a Painswick cottage before their existing home was sold.

Read the case study

The expat mortgage must be assessed as a credible exit before entering the bridge. Bridging finance is short term and normally more expensive than a mortgage; approval, timing and the eventual mortgage terms are not guaranteed. Clifton International is an introducer, not a lender or adviser, and does not handle client funds.

Recent transactions

More expat cases from other countries

These additional cases involve applicants in other countries; they do not establish eligibility for applicants on this page.

Contributor

Portrait of James Caldwell

James Caldwell

Director

LinkedIn profile
  • Co-founder
  • 26+ years in business and finance
  • Property finance specialist

James co-founded Clifton and has spent more than a decade building a specialist property finance business covering residential mortgages, bridging, development finance and complex international cases.

Frequently asked

Questions from clients

Do I need a specialist mortgage adviser or broker as a US citizen or US-based expat?

Yes. We strongly recommend independent, specialist advice. Many UK lenders decline US citizens and green card holders because of FATCA reporting. Others treat US dollar income, RSUs or K-1 partnership income differently, or do not offer mortgages to applicants living abroad. A specialist expat mortgage broker understands which lenders accept US persons and how each assesses dollar income, helping you avoid unsuitable applications and unnecessary credit searches. Clifton International is an introducer, not a lender or mortgage adviser. We introduce you to Clifton Private Finance, an independent, whole-of-market mortgage adviser with access to 40+ lenders. They review your circumstances, compare lenders that accept US-based applicants, and recommend the most suitable option in writing. Clifton Private Finance's published terms state that it is an appointed representative of Fair Investment Company Limited, which is authorised and regulated by the Financial Conduct Authority, and give Clifton Private Finance's FCA registration number as 766063. Check its current status on the FCA Register. Your home may be repossessed if you do not keep up repayments on your mortgage.

Can a US citizen get a UK mortgage?

Yes. US citizens, green card holders and US-resident British expats can arrange UK residential and buy-to-let mortgages. The panel is narrower than for UK residents because some lenders decline US persons on FATCA grounds, but several UK private banks and specialist lenders onboard US clients routinely.

Why do some UK lenders refuse US persons?

Under FATCA, financial institutions must report accounts held by US persons to the IRS. Some UK lenders have chosen not to build that reporting capability, so they decline US citizens and green card holders outright. It is a policy decision, not a credit judgement — the answer is to approach lenders that already report.

What deposit does a US buyer need for UK property?

Plan on a deposit of at least 25%, as the maximum is up to 75% loan-to-value for US-based applicants. Typical planning ranges are 25%–35% for a residential purchase and 25%–40% for buy-to-let. Any lower-deposit arrangement is exceptional, lender-specific and not part of our approved ranges; budget separately for stamp duty, fees and currency transfers.

Will USD income be accepted?

Often, yes. USD is widely considered by UK lenders that accept foreign-currency income, but acceptance is not universal. Many lenders reduce the converted sterling figure to allow for exchange-rate movement; the size of any reduction depends on the lender and affects how much you can borrow rather than guaranteeing eligibility.

Do I need a UK credit history?

Not always. Mainstream lenders usually rely on UK credit files, but some international and private-bank lenders may consider documented income, assets and US banking references instead. Options with limited UK credit history depend on the lender and your full circumstances.

Can I buy UK property through a US LLC or trust?

It is possible but adds complexity and cost. A UK SPV limited company is usually the cleaner route for investment property. US LLCs, revocable trusts and family partnerships can be accommodated by private banks with full beneficial-ownership disclosure, at higher pricing.

How does UK stamp duty work for US buyers?

Stamp Duty Land Tax (SDLT) applies in England and Northern Ireland; Scotland and Wales have their own taxes. Non-UK residents pay a 2% surcharge on top of standard rates. Under HMRC's test you are usually non-resident if you were not in the UK for at least 183 days in the 12 months before completion; for joint buyers, the surcharge generally applies if any buyer is non-resident, although married couples and civil partners are treated together. If you later spend 183 days in the UK within 12 months after completion, you may be able to claim a refund of the surcharge. A further 5% higher-rate charge can apply if you already own residential property anywhere in the world. Rules change, so check HMRC guidance and take tax advice before exchange.

Are there US tax consequences to owning UK property?

Possibly. US citizens and green card holders are generally taxed by the US on worldwide income wherever they live, while US-resident non-citizens may also have US reporting duties. UK rental income and gains must usually be reported in both countries; relief for UK tax under the US–UK treaty or foreign tax credits is not automatic and depends on your circumstances. Currency movements on a sterling mortgage can create US tax effects. Non-resident landlords also need to consider HMRC's Non-resident Landlord Scheme. We do not give tax advice — coordinate UK and US tax advisers before buying.

Can I remortgage a UK property I own while living in the US?

Yes. Expat remortgages and capital raising against existing UK property are routine, whether you moved to the US after buying, want to release equity, or are coming off an expiring fixed rate onto a better product.

How long does a UK mortgage take for a US-based applicant?

Typically eight to fourteen weeks from a complete application. The extra time versus a domestic case comes from certified identity documents, US-format bank statements and time-zone coordination. Where a deadline is tight, bridging finance can sometimes complete in around 3–5 weeks; timing is not guaranteed, the bridge needs a credible exit, and any later mortgage is subject to separate approval.

What documents will I need?

US passport, proof of US address, three to six months of US bank statements, the last two years of federal tax returns (Form 1040) plus W-2s or K-1s, employment contract or CPA-prepared accounts if self-employed, and source-of-deposit evidence. Most lenders require certified or notarised ID copies.

Can US buyers use bridging finance in the UK?

Yes. Short-term bridging is sometimes used by US buyers for auction purchases, chain-free acquisitions and refurbishment projects, and can sometimes complete in around 3–5 weeks. Lenders focus on the property and a credible exit, such as a sale or refinance onto a term mortgage, but that refinance is not guaranteed. Your property may be at risk if the bridge is not repaid.

Currency exchange

Earning overseas? Your deposit is exposed until it’s in sterling.

Expat buyers moving dollars, dirhams, riyals or euros into the UK can lose thousands to bank margins and rate moves. We introduce you to an FCA-authorised currency specialist who plans your transfer around exchange and completion.

  • Forward contracts to fix your sterling deposit before completion
  • Better-than-bank rates on large one-off and regular transfers
  • Flexible contact across time zones with a dedicated specialist

Clifton introduces clients to a specialist currency partner and does not hold, convert or transfer client funds.

UK expat finance

Ready to explore your options?

Speak to a UK property finance specialist.

A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.