£809K mortgage for unique countryside property to exit bridging loan
£809k · 60% LTV · 25-year term
In short
How was £809K mortgage for unique countryside property to exit bridging loan financed?
Clifton International arranged high-value residential mortgage for this Hertfordshire transaction — £809k, 60% LTV, 25-year term. We approached a private bank comfortable with the property's construction and countryside setting, submitted a full income and asset profile, and arranged a specialist valuation. £809k residential mortgage, 60% LTV, 25-year term, capital & interest.
- Location: Hertfordshire. Finance type: High-value residential mortgage.
- Headline terms: £809k · 60% LTV · 25-year term.
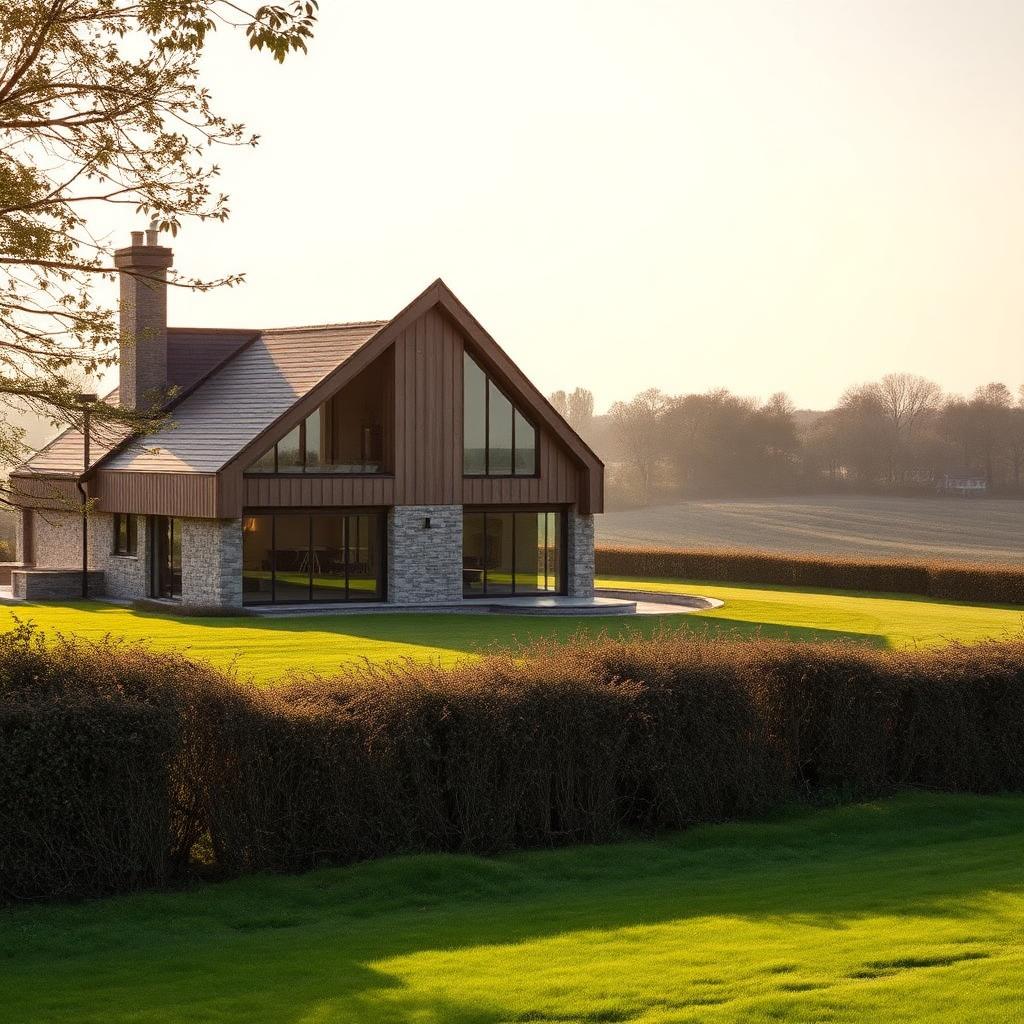
- Clients had used a short-term bridging loan to secure a unique countryside property with non-standard construction. Mainstream lenders declined the refinance on property-type grounds despite strong income and equity.
- Bridging loan repaid in full and clients settled into their long-term home on affordable monthly repayments.
- Loan amount
- £809,000
- LTV
- 60%
- Term
- 25 years
- Repayment
- Capital & interest
- Purpose
- Bridge exit
- Location
- Hertfordshire
- Challenge
- Clients had used a short-term bridging loan to secure a unique countryside property with non-standard construction. Mainstream lenders declined the refinance on property-type grounds despite strong income and equity.
- Solution
- We approached a private bank comfortable with the property's construction and countryside setting, submitted a full income and asset profile, and arranged a specialist valuation.
- Funding structure
- £809k residential mortgage, 60% LTV, 25-year term, capital & interest.
- Outcome
- Bridging loan repaid in full and clients settled into their long-term home on affordable monthly repayments.
More UK case studies
Related transactions
£1.3M bridging loan to support a significant upsize in Leeds
£1.3m · 65% LTV · 12-month regulated bridge
£230k bridging loan secured against UK property to buy a Malaga apartment
£230k · c.25% LTV · 36 days to completion
£1.2M bridging loan secured to complete dream home purchase in Oxfordshire
£1.2m · 60% LTV · chain-break bridge
FAQs
Questions on this case
- Can you get a mortgage on a non-standard construction property?
- Yes, but usually not from a mainstream lender. High street lenders frequently decline unique or non-standard construction on policy grounds, as in this case. Private banks and specialist lenders assess each property on its merits, and placed this Hertfordshire countryside home at 60% LTV on a 25-year capital & interest basis.
- Can I use a residential mortgage to repay a bridging loan?
- Yes — exiting a bridge onto a long-term residential mortgage is one of the most common exit strategies. The key requirements are a property valuation that supports the loan, demonstrated affordability for the long-term repayments, and a lender comfortable with the property itself. In this case, the £809k mortgage repaid the bridging loan in full.
- Why did mainstream lenders decline this refinance?
- The property's non-standard construction and unique countryside setting fell outside mainstream lending policy, even though the clients had strong income and equity. Specialist valuations and private bank underwriting allowed the case to be approved where volume lenders could not.
- What loan size suits a private bank mortgage?
- Private banks typically become competitive for larger or more complex loans — often from around £500k upwards, and particularly for high-value homes, unusual property types or complex income. This £809k bridge-exit mortgage was placed with a private bank willing to underwrite the property's construction.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.