Purchase, buy-to-let and remortgage finance for British expatriates and foreign nationals based in Dubai, Abu Dhabi and the wider Emirates — with AED income, contractual allowances and Gulf banking references fully understood.
In short: UAE residents can be considered for UK property finance on verified overseas income; returning expats may qualify for UK resident mortgage rates instead.
Two quick steps — a specialist will respond within one working day.
Step 1 of 2
40+ lendersWhole-of-market panel
8–14 weeksTypical completion
Rated ExcellentClient reviews
No obligationFree initial review
Last updated Reviewed by our Clifton International finance team.
In short
Can expats in the UAE get a UK mortgage?
Yes. UAE-based expats can be considered for UK residential and buy-to-let mortgages using verified AED income. The dirham is fixed to the US dollar at AED 3.6725 per USD, which may support more favourable income treatment than volatile currencies, depending on the lender. Eligible products can reach 80% loan-to-value, requiring a 20% deposit; 25%–40% is a typical planning range. Purchases and remortgages normally take 8–14 weeks from a complete application, subject to valuation, legal work and lender criteria.
Dubai and Abu Dhabi salary, allowances and bonus income are assessed separately.
Residential and buy-to-let property use have different criteria.
UK SPV and offshore structures require separate lender checks.
Returning UAE expats may qualify for UK resident rates for a home they will occupy.
London · Expat buy-to-let
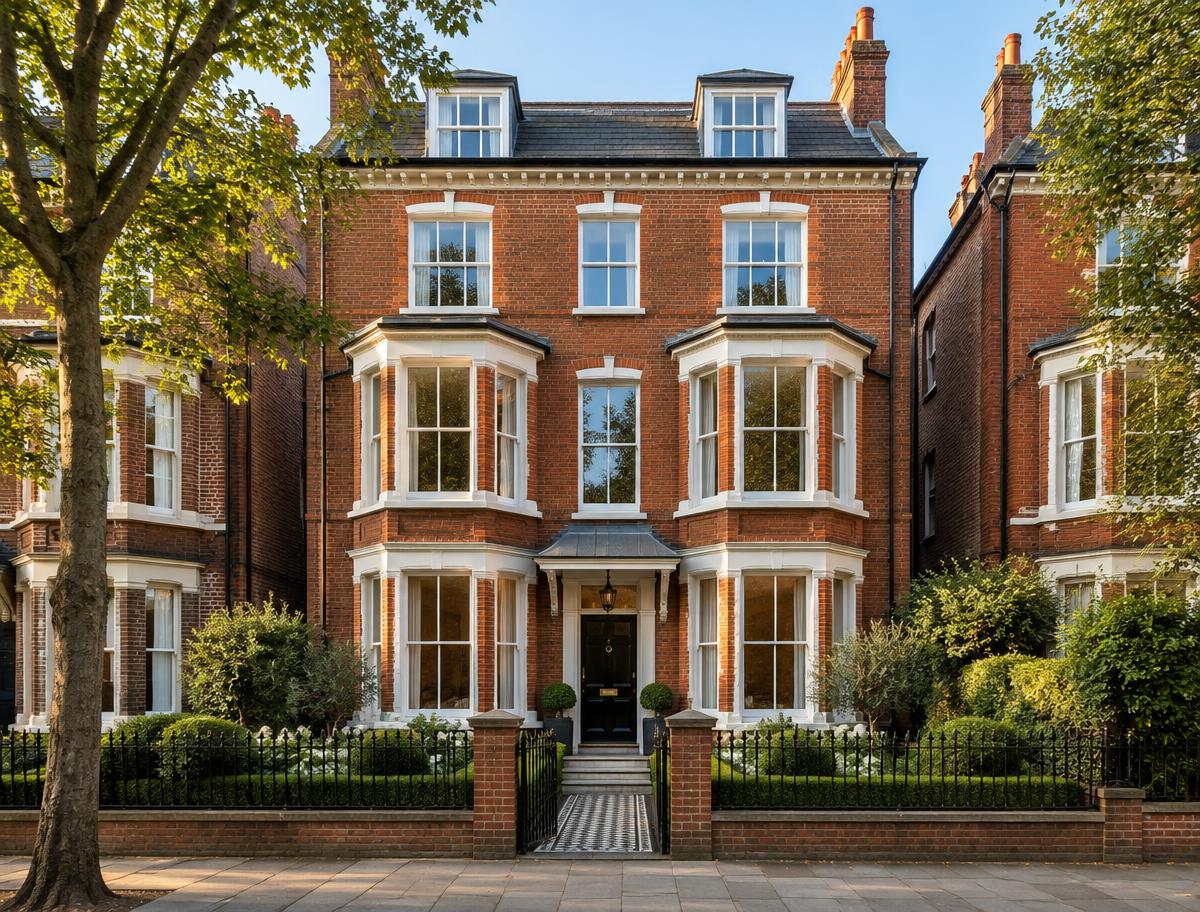
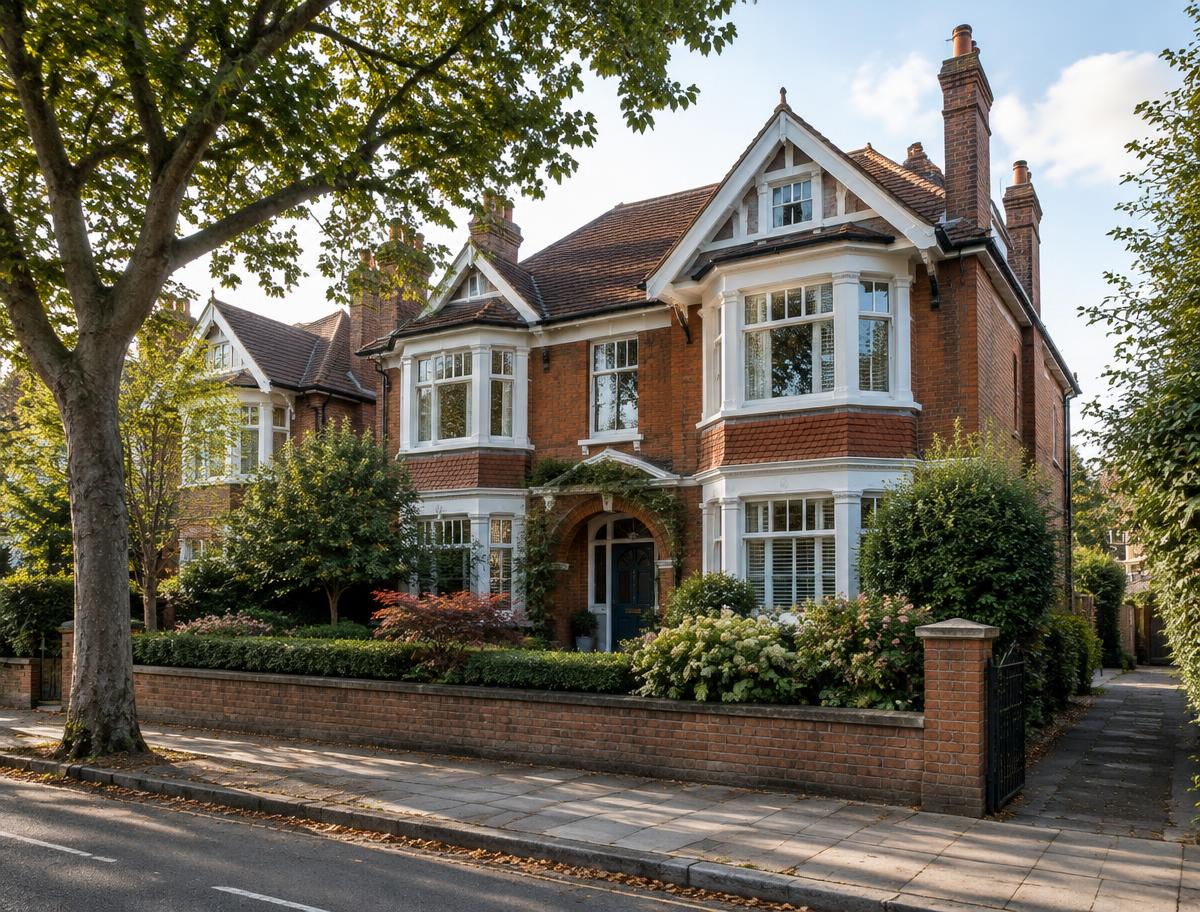
£2.2m buy-to-let for a Dubai-based investor
A UAE-resident investor secured a £2.2m buy-to-let mortgage on a prime London rental valued at around £4m — an assumed approximate value giving about 55% indicative loan-to-value — structured interest-only so capital stayed free for other investments.
Source: Clifton International's supplied case-study account of an anonymised completed transaction for a Dubai-based investor acquiring UK buy-to-let property. Clifton International facilitates introductions to specialist property finance teams and was not the lender or mortgage adviser. Figures and outcomes are reported case facts, not independently audited market statistics.
Photo: illustrative, not the client’s actual property. The approximately £4m value is an assumption, not an independently verified valuation. Rate, fees and lender identity are not disclosed; this outcome does not establish current terms or guarantee approval.
25% – 40%Planning range; eligible 80% LTV products need 20%. Budget separately for taxes and fees.
Income considered
AED, USD, GBP, EURAcceptance and any sterling conversion adjustment depend on the selected lender.
Purposes
Purchase, buy-to-let, remortgage
Indicative timescale
8–14 weeksFrom a complete application; valuation, legal work, overseas checks and attestation can affect completion.
Mortgage pricing
See the approved monthly rates belowDated indicative products, not a UAE-specific offer or an individual quote.
Fees and purchase costs
Confirm for your transactionBudget separately for product fees, valuation, legal costs, property taxes and currency transfers; no generic all-in percentage applies.
Indicative figures for guidance only, correct as at October 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.
Methodology and assumptions
Loan size, deposit and completion figures are approved indicative preparation assumptions, not official statistics, guaranteed eligibility or live lender offers.
Mortgage pricing comes only from the published, approved monthly snapshot below, with its own reference and approval dates; it is not a whole-market comparison or confirmation that each product accepts a UAE-based applicant.
Central Bank of the UAE sources support the AED–USD peg, not sterling affordability or lender acceptance. HMRC guidance supports UK SDLT and landlord-tax rules, not finance terms.
The Dubai buy-to-let case is a published Clifton Private Finance account, not evidence of current rates or terms. Editorial review dates are separate from financial approvals.
Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.
Last updated Content review only — approved mortgage-rate dates appear separately in the rates panels.
Based in Dubai? Our dedicated UK mortgages for Dubai expats guide covers Dubai salary packaging, dollar-pegged income and a published Dubai buy-to-let case study.
Borrower eligibility
Who can qualify for a UK mortgage from the UAE?
In short: British expats and eligible foreign nationals living in the UAE can be considered for UK home purchases, buy-to-let and remortgages. Lenders assess residence, nationality, verified income, credit evidence and property use individually.
British expatriates resident in the UAE
Foreign nationals in Dubai or Abu Dhabi buying UK property
Gulf-based landlords building a UK buy-to-let portfolio
Business owners with UAE trade licences and audited accounts
Buyers using a UK SPV, DIFC, ADGM or offshore structure
Expats remortgaging or capital raising on existing UK property
Typical lending criteria
UK mortgages from the UAE: deposits, loan sizes and terms
In short: 25%–40% is a typical deposit planning range; eligible 80% LTV products need 20%. The broad introduction-service loan range below is not the same as the limits of each approved product in the rate comparison. Terms, currencies and interest-only options depend on lender checks.
Loan size
£150k – £25m+
Loan-to-value
Up to 80%Eligible products only; borrower, property and lender restrictions apply.
Typical deposit
25% – 40%Typical planning range; eligible 80% LTV products need 20%, plus separate funds for taxes and fees.
Term
Up to 30 years
Interest-only
Available
Accepted income
AED, USD, GBP, EUR
Typical timescale
8–14 weeks from a complete applicationTime-critical purchase? Expat bridging may complete in around 3–5 weeks, subject to checks — see UAE bridging finance.
Indicative only. Actual terms depend on borrower profile, asset and lender criteria.
Key figures
UK expat mortgage rates this month
Rates checked 2 November 2026 across 6 UK lenders that accept expat applicants. Based on a £300,000 loan, capital and interest.
Residential 2-year fixed, 75% LTV
from 5.64%*
typical 5.66%
Residential 5-year fixed, 75% LTV
from 5.63%*
typical 5.75%
Buy-to-let 2-year fixed, 75% LTV
from 5.69%*
typical 5.72%
Buy-to-let 5-year fixed, 75% LTV
from 5.54%*
typical 5.74%
Expat rate questions
What are UK expat mortgage rates this month?
As at 2 November 2026, 2-year fixed residential expat rates on our panel start from 5.54% at 60% LTV and 5.64% at 80% LTV, based on a £300,000 loan, capital and interest. Product fees may apply.
What is a typical expat buy-to-let rate?
For a 5-year fixed expat buy-to-let at 75% LTV, rates start from 5.54% with a typical rate of 5.74% across 5 lenders (2 November 2026).
Can expats get an interest-only mortgage?
Yes. Interest-only residential 2-year fixes at 75% LTV start from 5.85% as at 2 November 2026. You will need a credible plan to repay the balance at the end of the term.
*Product fees may apply. Indicative initial rates only; after the fixed term the rate reverts to the lender's variable rate. Source: published lender rate sheets for intermediaries, approved by Clifton International (2 November 2026). Not an offer of finance; your home may be repossessed if you do not keep up repayments on your mortgage.
Indicative expat mortgage rates
Market-leading fixed rates from our expat lender panel. The panel rate sheets were last checked and approved 2 November 2026; this article's content-review date is separate and shown with the reviewer credit. Choose your property type, fixed period, loan-to-value and loan size.
Residential · Capital & interest · 2-year fixed · up to 75% LTV
Lowest to typical rate available · 4 panel lenders qualify · property value approx. £666,667
After the 2-year initial product term ends, the rate reverts to the lender's variable rate unless you remortgage or switch to a new product.
Example monthly payment at the lowest rate: £3,112Capital and interest over 25 years.
How this rate comparison works
In short: for each combination you choose, we take the cheapest product from every panel lender that covers your loan size and loan-to-value. The lowest figure is the cheapest of those; the typical figure is the median across the qualifying lenders, so it reflects the middle of the panel rather than its best headline rate.
This comparison is supported by 4 qualifying panel lenders out of the 6 lenders on our expat panel.
Lender names are deliberately withheld: the underlying rate sheets are published for intermediaries, and named products are confirmed with you in a private recommendation, not in a public comparison. The date above is the rate-approval date — when the panel rate sheets were last checked and approved — and governs the figures only; this article's content-review date is checked separately and shown with the reviewer credit.
*Product fees may apply. Indicative only, based on published rates for international borrowers; not a quote, offer or recommendation. Eligibility, income currency, residency and property type affect the rate available.Your home may be repossessed if you do not keep up repayments on your mortgage.
Which UAE income types can UK mortgage lenders consider?
In short: separate basic salary, contractual allowances, variable pay and assets; a lender does not necessarily count your full UAE package as recurring income.
UAE income types and typical UK mortgage evidence
Income type
Evidence usually requested
How it may be assessed
Basic salary (AED)
Employment contract, salary certificate or payslips and matching personal bank credits.
A core affordability input, converted to GBP with any lender-specific currency adjustment.
Housing allowance
Contract or employer letter itemising the allowance, plus pay records.
May count where contractual and sustainable; benefits ending on return to the UK need separate treatment.
Transport and schooling allowances
Employer confirmation of the terms, payment records and any reimbursement conditions.
Guaranteed cash allowances may count; reimbursements and benefits in kind may not.
Bonus and commission
Historic award letters, payslips and bank credits over the period requested by the lender.
May be averaged or partly counted; a one-off bonus is not normally sustainable income.
Business-owner income
Trade licence, company accounts, business bank statements and evidence of personal salary or dividends.
Trading history, ownership and sustainable profits require individual assessment; company turnover is not personal income.
End-of-service gratuity
Employer entitlement statement and payment record if received.
Usually an asset, not recurring income. Deposit use needs evidence of payment and source of funds.
Basic salary (AED)
Evidence usually requested
Employment contract, salary certificate or payslips and matching personal bank credits.
How it may be assessed
A core affordability input, converted to GBP with any lender-specific currency adjustment.
Housing allowance
Evidence usually requested
Contract or employer letter itemising the allowance, plus pay records.
How it may be assessed
May count where contractual and sustainable; benefits ending on return to the UK need separate treatment.
Transport and schooling allowances
Evidence usually requested
Employer confirmation of the terms, payment records and any reimbursement conditions.
How it may be assessed
Guaranteed cash allowances may count; reimbursements and benefits in kind may not.
Bonus and commission
Evidence usually requested
Historic award letters, payslips and bank credits over the period requested by the lender.
How it may be assessed
May be averaged or partly counted; a one-off bonus is not normally sustainable income.
Business-owner income
Evidence usually requested
Trade licence, company accounts, business bank statements and evidence of personal salary or dividends.
How it may be assessed
Trading history, ownership and sustainable profits require individual assessment; company turnover is not personal income.
End-of-service gratuity
Evidence usually requested
Employer entitlement statement and payment record if received.
How it may be assessed
Usually an asset, not recurring income. Deposit use needs evidence of payment and source of funds.
Lenders vary. Evidence, income acceptance, residency requirements and terms depend on the lender and your circumstances. This is general preparation guidance, not an offer of finance.
Which documents do UAE expats need for a UK mortgage?
In short: prepare UAE identity and residence evidence, income records, bank statements and your deposit trail; remortgages also need existing-loan and property-use details.
Identity and residence: passport, Emirates ID, UAE residence evidence and recent proof of address.
Employed income: contract, salary certificate or payslips itemising salary and contractual allowances.
Banking and deposit: commonly three to six months of personal bank statements, deposit-source records and an AED-to-GBP transfer trail.
Business owners: trade licence, accounts, business statements and evidence of personal income.
Remortgages: latest mortgage statement, deal end date, early-repayment charge and tenancy or occupancy information.
Certification: check the chosen lender's requirements before paying for translations, notarisation or attestation.
Lenders vary. Evidence, income acceptance, residency requirements and terms depend on the lender and your circumstances. This is general preparation guidance, not an offer of finance.
In short: UAE-based buyers may apply for UK rental-property finance in personal names or through a UK limited company. Lenders assess the property, rental cover, deposit and applicant circumstances; some also require personal income.
Personal ownership or a UK limited company?
With personal ownership, you own the property and apply individually or jointly. With a UK limited company, often a special purpose vehicle (SPV), the company owns the property and borrows. Company, shareholder and overseas-director eligibility require separate checks, and lenders may ask for personal guarantees. A UK company is not automatically more tax-efficient: compare UK and applicable UAE tax obligations, running costs, extracting profits and eventual sale plans with qualified advisers. Transferring an existing property into a company can create tax and transaction costs.
UAE, DIFC, ADGM and other offshore entities are not interchangeable with a UK SPV; lender appetite, legal security and ownership checks differ. Read our limited-company buy-to-let guide for expats.
Managing a UK rental property from the UAE
Agree a UK managing agent’s responsibilities for tenants, repairs, emergencies and communication across the time difference.
Budget in sterling for insurance, safety checks, deposit protection, applicable licensing, repairs and periods without rent. Requirements vary across the UK.
Before letting a former home, check consent to let or a buy-to-let remortgage with the existing lender.
HMRC’s Non-resident Landlord Scheme
Living in the UAE does not remove UK tax obligations on UK rental income. Under HMRC’s Non-resident Landlord Scheme, a letting agent normally deducts basic-rate tax unless HMRC approves payment without deduction. Without an agent, a tenant paying more than £100 a week normally has withholding duties unless HMRC authorises gross payment. Receiving rent without deduction does not make it tax-free; reporting and any tax due remain your responsibility. Individuals can apply using form NRL1; companies use a separate application.
General preparation guidance, not tax advice or an offer of finance. Ownership, tax treatment and finance eligibility depend on your circumstances.
Returning from the UAE: can you buy or remortgage at UK resident rates?
In short: If you are returning from the UAE to live in the UK, we can often source mortgages based on UK resident rates rather than expat rates, for a purchase or remortgage. This is not automatic: the lender checks your return date, intended UK home, employment or other sustainable income, and when that income starts. Tell us whether you will occupy the property yourself or continue letting it; a rental property may still need a buy-to-let mortgage.
Start the conversation before moving. Useful preparation may include a signed UK employment contract or offer with its start date, evidence of your intended return and UK address, recent UAE pay records, any gap between jobs and the source of your deposit or savings. A visa cancellation or flight booking alone does not establish mortgage eligibility. Lenders assess whether income remains sustainable after relocation; UAE allowances may stop when you leave.
For a former UK home, explain whether you will move back in, retain a tenancy or buy a different home. These are different applications, and a UK resident rate is not guaranteed simply because you plan to return. See the UK mortgage guidance for returning expats.
Lenders vary. Evidence, income acceptance, residency requirements and terms depend on the lender and your circumstances. This is general preparation guidance, not an offer of finance.
How can you remortgage UK property while living in the UAE?
In short: compare your existing lender's product-switch options with a new expat mortgage, using your current balance, property value, deal end date and occupancy plans.
UK remortgage scenarios for UAE expats
Scenario
What to consider
Information to prepare
Expiring fixed rate
Check whether your existing lender offers a product switch to UAE residents. If not, compare a new expat mortgage before the existing deal ends.
Current lender, balance, deal end date, current rate, early-repayment charge and estimated UK property value.
Switching lenders
A new lender reassesses your overseas residence, AED income, affordability and property; a fresh valuation and legal work may be needed.
Passport, Emirates ID and residence evidence, employment records, bank statements and latest mortgage statement.
Capital raising
Additional borrowing is subject to available equity, an acceptable use of funds and affordability or rental-cover checks. It is not an automatic entitlement.
Amount requested, reason for the funds, existing balance, property value and evidence supporting the higher borrowing.
Former UK home now let
A residential mortgage may no longer fit the property use. Check existing consent to let and whether a buy-to-let remortgage is needed.
Tenancy agreement, rent evidence, consent-to-let position and whether you intend to return to live there.
Expiring fixed rate
What to consider
Check whether your existing lender offers a product switch to UAE residents. If not, compare a new expat mortgage before the existing deal ends.
Information to prepare
Current lender, balance, deal end date, current rate, early-repayment charge and estimated UK property value.
Switching lenders
What to consider
A new lender reassesses your overseas residence, AED income, affordability and property; a fresh valuation and legal work may be needed.
Information to prepare
Passport, Emirates ID and residence evidence, employment records, bank statements and latest mortgage statement.
Capital raising
What to consider
Additional borrowing is subject to available equity, an acceptable use of funds and affordability or rental-cover checks. It is not an automatic entitlement.
Information to prepare
Amount requested, reason for the funds, existing balance, property value and evidence supporting the higher borrowing.
Former UK home now let
What to consider
A residential mortgage may no longer fit the property use. Check existing consent to let and whether a buy-to-let remortgage is needed.
Information to prepare
Tenancy agreement, rent evidence, consent-to-let position and whether you intend to return to live there.
Plan for 8–14 weeks from a complete remortgage application. Valuation, legal work and overseas document checks affect completion; complex capital raising can take longer. A product switch can be quicker. Compare the total cost, including early-repayment charges and fees, rather than only the headline rate. Read our guide to remortgaging UK property as an expat.
Lenders vary. Evidence, income acceptance, residency requirements and terms depend on the lender and your circumstances. This is general preparation guidance, not an offer of finance.
Buying versus remortgaging UK property from the UAE
In short: a purchase focuses on your deposit and intended property use; a remortgage starts with your existing debt, equity and current occupancy.
UK purchase versus remortgage for UAE-based expats
Topic
UK purchase
UK remortgage
Main purpose
Buy a UK home or rental property while living in the UAE, or ahead of returning.
Replace an existing UK mortgage, switch lender or raise capital.
Deposit or equity
Evidence of cash deposit, how it accumulated and the transfer trail into sterling.
Current valuation less the mortgage balance determines available equity; early-repayment charges matter.
Income and affordability
Verified AED salary and eligible allowances, or rental-cover checks for buy-to-let.
Income is reassessed by a new lender; a returning expat's future UK income may be considered separately.
Property use
Confirm who will live in the property, or whether it will be let.
Declare current letting, consent to let and your plans to occupy or keep renting it.
Costs
Budget for purchase taxes, legal and valuation costs, product fees and currency transfers.
Budget for product, legal and valuation fees and any early-repayment charge. A straight remortgage without an ownership change is not normally a property-tax transaction.
Documents
UAE identity, residence, income and deposit evidence plus UK property details.
The same personal evidence, plus a mortgage statement, fixed-rate end date and tenancy details if let.
Planning timeframe
8–14 weeks from a complete application; chains and certification can delay completion.
8–14 weeks from a complete application; product switches may be quicker and complex capital raising longer.
Main purpose
UK purchase
Buy a UK home or rental property while living in the UAE, or ahead of returning.
UK remortgage
Replace an existing UK mortgage, switch lender or raise capital.
Deposit or equity
UK purchase
Evidence of cash deposit, how it accumulated and the transfer trail into sterling.
UK remortgage
Current valuation less the mortgage balance determines available equity; early-repayment charges matter.
Income and affordability
UK purchase
Verified AED salary and eligible allowances, or rental-cover checks for buy-to-let.
UK remortgage
Income is reassessed by a new lender; a returning expat's future UK income may be considered separately.
Property use
UK purchase
Confirm who will live in the property, or whether it will be let.
UK remortgage
Declare current letting, consent to let and your plans to occupy or keep renting it.
Costs
UK purchase
Budget for purchase taxes, legal and valuation costs, product fees and currency transfers.
UK remortgage
Budget for product, legal and valuation fees and any early-repayment charge. A straight remortgage without an ownership change is not normally a property-tax transaction.
Documents
UK purchase
UAE identity, residence, income and deposit evidence plus UK property details.
UK remortgage
The same personal evidence, plus a mortgage statement, fixed-rate end date and tenancy details if let.
Planning timeframe
UK purchase
8–14 weeks from a complete application; chains and certification can delay completion.
UK remortgage
8–14 weeks from a complete application; product switches may be quicker and complex capital raising longer.
Lenders vary. Evidence, income acceptance, residency requirements and terms depend on the lender and your circumstances. This is general preparation guidance, not an offer of finance.
UAE dirham and currency risk
In short: the dirham is pegged to the US dollar, not the pound, so the sterling cost of your UK mortgage moves with the US dollar rather than with the United Arab Emirates.
The Central Bank of the UAE (CBUAE) maintains the fixed peg at 3.6725 dirhams to the US dollar and intervenes in the foreign exchange market to keep it there, describing the peg as the overriding objective of its monetary policy. The UAE dirham is fixed to the US dollar at AED 3.6725 per USD. This provides stability against the dollar and may support more favourable income-conversion treatment than some more volatile currencies, depending on the lender. Any affordability reduction (a “haircut”) is lender-dependent, and the peg does not remove sterling exchange-rate risk. In practice the dirham–pound rate you see is largely the US dollar–pound rate in disguise: if the pound strengthens against the dollar, your dirham salary converts into fewer pounds and your UK mortgage costs more each month, even though nothing has changed for you locally.
When you apply: lenders usually convert AED income at the day's rate and may reduce it for currency risk, so a stronger pound can mean a smaller loan offer rather than a declined application.
While you repay: a fixed interest rate is fixed in sterling, so the dirham cost of each monthly payment still rises and falls as the exchange rate moves.
How to prepare: holding a sterling buffer, transferring in stages, or fixing an agreed rate for a deposit transfer can reduce the risk of a shortfall at completion.
Example based on lender rates approved 2 November 2026. 75% LTV, £100,000 deposit, capital and interest over 25 years.
Monthly repayment on a £300,000 expat mortgage at approved rates
Product
Lowest rate*
Monthly repayment
Residential 2-year fixed
5.64%
£1,867
Residential 5-year fixed
5.63%
£1,866
Buy-to-let 2-year fixed
5.69%
£1,876
Buy-to-let 5-year fixed
5.54%
£1,849
As a buy-to-let on a 5-year fix, the rent needed would be approx. £1,731 per month — speak to our team to confirm.
*Product fees may apply. Indicative only, not a quote or offer. The rate reverts to the lender's variable rate after the initial fixed period. Your home may be repossessed if you do not keep up repayments on your mortgage.
Illustrative UAE expat mortgage scenarios
These are hypothetical preparation examples, not completed client transactions, quotes or confirmed lender terms. Published case studies are shown separately below.
Illustrative — not a completed transaction
£1.85m London purchase — Dubai-based expat
An AED-paid buyer with a thin UK credit file could prepare international banking records, deposit evidence and intended occupancy details for an individual affordability assessment.
Illustrative — not a completed transaction
£1.3m Surrey purchase — Abu Dhabi executive
An employed buyer could separate basic salary from housing and schooling allowances, so a lender can determine which payments are contractual and sustainable.
Illustrative — not a completed transaction
£950k portfolio remortgage — Dubai landlord
An overseas landlord could prepare balances, valuations, tenancy and rental records for UK properties, with separate checks for any SPV ownership or capital raising.
Recent transactions
More expat cases from other countries
These additional cases involve applicants in other countries; they do not establish eligibility for applicants on this page.
The UAE dirham is fixed to the US dollar at AED 3.6725 per USD. This provides stability against the dollar and may support more favourable income-conversion treatment than some more volatile currencies, depending on the lender. Any affordability reduction (a “haircut”) is lender-dependent, and the peg does not remove sterling exchange-rate risk. Any lender-specific adjustment is explained before you apply.
Contractual allowances
Housing, transport and schooling payments assessed according to their terms, evidence and whether they remain sustainable.
Gulf banking evidence
UAE banking history may help support applications with a thin UK credit file, subject to lender checks.
SPV & offshore structures
Separate eligibility and ownership checks for UK SPV and offshore buy-to-let structures.
Attestation handled
Practical guidance on notarisation, attestation and courier timelines so overseas paperwork does not stall the case.
Returning to the UK
Purchase and remortgage options may include UK resident rates where your return and future income meet the selected lender's criteria.
James co-founded Clifton and has spent more than a decade building a specialist property finance business covering residential mortgages, bridging, development finance and complex international cases.
Short-term finance · indicative
Need to move quickly? Bridging finance from the UAE
An auction, chain break or purchase deadline may make UK bridging finance an option for a UAE-based buyer. Lenders assess the UK property, borrower circumstances, overseas identity and source-of-funds evidence, and a credible repayment exit. Income, affordability where relevant, residence and regulatory requirements still affect eligibility. Completion depends on valuation, legal work and a complete document pack; speed is not guaranteed.
Indicative completion
3–5 weeks
Indicative monthly cost
0.65%–1.00%
Per month, plus fees
Loan-to-value
Up to about 70%
Plan the exit before committing: usually a property sale or refinancing onto a term expat mortgage. A future mortgage is not guaranteed; assess eligibility and affordability first and allow for delays. Bridging is short-term, can cost more than a mortgage, and puts the secured property at risk if it cannot be repaid.
Yes. British expatriates and other eligible foreign nationals resident in Dubai, Abu Dhabi and the wider UAE can be considered for UK residential and buy-to-let mortgages without returning to the UK. Residence, nationality, income, property use and lender criteria are assessed individually.
Specialist lenders can accept AED income. They convert it into sterling for affordability and may reduce the converted figure for currency risk. The dirham is linked to the US dollar, not sterling; the adjustment and the income accepted vary by lender.
25% – 40% is a typical planning range. Eligible products at 80% loan-to-value require a 20% deposit, but are not available to every applicant or property. Buy-to-let, company purchases and private-bank arrangements have separate criteria. Taxes, fees and currency-transfer costs need a separate cash budget.
Lenders familiar with UAE employment can assess salary without a UAE personal income-tax return. They normally need a consistent employment contract, salary certificate or payslips, and bank statements showing the credits. Do not assume that the whole gross package will count as disposable income.
Contractual housing, transport and schooling allowances may be accepted where an employer confirms them and they are evidenced in the pay records. Discretionary payments, reimbursements and benefits that stop when you return to the UK may be excluded or only partly counted. Lenders vary.
End-of-service gratuity is generally an asset rather than recurring income. A paid benefit may support a deposit if its source is documented. Recurring bonuses need an evidenced history and may be averaged or partly counted; neither is guaranteed to increase affordability.
Some specialist and private-bank routes can consider company ownership, but a UK SPV is often more straightforward for buy-to-let. UAE and offshore structures require separate checks on ownership, source of wealth, legal setup and lender appetite. Obtain independent legal and tax advice before choosing a structure.
A UK credit file can help but is not always required. Some specialist lenders consider verified UAE income, international banking history and credit evidence instead. A thin UK file is not the same as adverse credit, which must still be disclosed.
For residential purchases in England and Northern Ireland, the 2% non-resident SDLT surcharge may apply under its own residence test, separate from general tax residence. Higher rates for additional dwellings may also apply. Scotland and Wales have different property taxes. Ask your conveyancer to confirm the rules, any refund eligibility and your budget before exchange.
Yes, subject to lender criteria. Options can include a product switch with your existing lender, refinancing to another expat lender or capital raising. Provide your current mortgage balance, estimated property value, fixed-rate end date, any early-repayment charge, property use and UAE income evidence.
If you are returning from the UAE to live in the UK, we can often source mortgages based on UK resident rates rather than expat rates, for a purchase or remortgage. This is not automatic: the lender checks your return date, intended UK home, employment or other sustainable income, and when that income starts. Tell us whether you will occupy the property yourself or continue letting it; a rental property may still need a buy-to-let mortgage.
Plan for 8–14 weeks from a complete mortgage application to completion, for a purchase or remortgage. Valuation, legal work, overseas identity checks and document certification affect timing; complex ownership or income can take longer. A product switch may be quicker. Bridging finance has a separate timetable and suitability assessment.
Typically a passport, UAE residence evidence and Emirates ID, employment contract and salary certificate or payslips, three to six months of personal bank statements, and source-of-deposit evidence. Remortgages also need a current mortgage statement and details of occupancy or letting. Business owners may need a trade licence, accounts and evidence of salary or dividends. Certification and translation requirements vary by lender.
Currency exchange
Earning overseas? Your deposit is exposed until it’s in sterling.
Expat buyers moving dollars, dirhams, riyals or euros into the UK can lose thousands to bank margins and rate moves. We introduce you to an FCA-authorised currency specialist who plans your transfer around exchange and completion.
Forward contracts to fix your sterling deposit before completion
Better-than-bank rates on large one-off and regular transfers
Flexible contact across time zones with a dedicated specialist
Clifton introduces clients to a specialist currency partner and does not hold, convert or transfer client funds.
Moving from UAE to Saudi Arabia, or comparing UK property options across the Gulf? Our guide to UK property purchases and remortgages for expats in Saudi Arabia covers Saudi salary and allowances, Iqama and document preparation, buy-to-let property use and refinancing an existing UK home. Your country of residence and income evidence need reassessment; lender criteria vary.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.