Illustrative — not a completed transaction
£980k SPV buy-to-let — Riyadh-based landlord
British expat adding two Manchester units to a UK SPV portfolio, underwritten on rental cover at 75% LTV with no reliance on UK credit history.
Two quick steps — a specialist will respond within one working day.
Last updated Reviewed by our Clifton International finance team.
In short
Yes. Expats living in Saudi Arabia can borrow up to 80% of value on eligible products on UK property, with SAR income accepted by specialist lenders. Applications are income assessed on documented salary and allowances, and normally complete within eight to fourteen weeks.
Saudi case study · Ealing
A UK couple upsizing to a house of about £2.03m in Ealing raised a reported £1.2m mortgage based on the husband's Saudi Aramco income — salary plus bonuses and housing, living and school-fee allowances — while deciding whether to sell or let their existing home.
Source: Clifton Private Finance account, July 2023 — not a Clifton International transaction. Historical rates and fees omitted. Photo: illustrative, not the clients' property.
Read the full case studyAt a glance
Figures reviewed:
Indicative figures for guidance only, correct as at October 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.
Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.
Borrower eligibility
Typical lending criteria
Indicative only. Actual terms depend on borrower profile, asset and lender criteria.
Key figures
Rates checked 2 November 2026 across 6 UK lenders that accept expat applicants. Based on a £300,000 loan, capital and interest.
What are UK expat mortgage rates this month?
As at 2 November 2026, 2-year fixed residential expat rates on our panel start from 5.54% at 60% LTV and 5.64% at 80% LTV, based on a £300,000 loan, capital and interest. Product fees may apply.
What is a typical expat buy-to-let rate?
For a 5-year fixed expat buy-to-let at 75% LTV, rates start from 5.54% with a typical rate of 5.74% across 5 lenders (2 November 2026).
Can expats get an interest-only mortgage?
Yes. Interest-only residential 2-year fixes at 75% LTV start from 5.85% as at 2 November 2026. You will need a credible plan to repay the balance at the end of the term.
*Product fees may apply. Indicative initial rates only; after the fixed term the rate reverts to the lender's variable rate. Source: published lender rate sheets for intermediaries, approved by Clifton International (2 November 2026). Not an offer of finance; your home may be repossessed if you do not keep up repayments on your mortgage.
Market-leading fixed rates from our expat lender panel. The panel rate sheets were last checked and approved 2 November 2026; this article's content-review date is separate and shown with the reviewer credit. Choose your property type, fixed period, loan-to-value and loan size.
Residential · Capital & interest · 2-year fixed · up to 75% LTV
5.64% – 5.66%*
Lowest to typical rate available · 4 panel lenders qualify · property value approx. £666,667
After the 2-year initial product term ends, the rate reverts to the lender's variable rate unless you remortgage or switch to a new product.
Example monthly payment at the lowest rate: £3,112Capital and interest over 25 years.
In short: for each combination you choose, we take the cheapest product from every panel lender that covers your loan size and loan-to-value. The lowest figure is the cheapest of those; the typical figure is the median across the qualifying lenders, so it reflects the middle of the panel rather than its best headline rate.
This comparison is supported by 4 qualifying panel lenders out of the 6 lenders on our expat panel.
Lender names are deliberately withheld: the underlying rate sheets are published for intermediaries, and named products are confirmed with you in a private recommendation, not in a public comparison. The date above is the rate-approval date — when the panel rate sheets were last checked and approved — and governs the figures only; this article's content-review date is checked separately and shown with the reviewer credit.
*Product fees may apply. Indicative only, based on published rates for international borrowers; not a quote, offer or recommendation. Eligibility, income currency, residency and property type affect the rate available.Your home may be repossessed if you do not keep up repayments on your mortgage.
Earning in euros? See UK mortgages with euro income — for eurozone expats and UK residents paid in EUR. Paid in dollars? See UK mortgages with US dollar income.
Send these details to a specialist — we'll confirm the best available rate within one working day.
Enquire with these detailsIn short: Saudi pay packages are usually made up of several parts, and lenders treat each one differently. The table below sets out the evidence commonly requested for each element and how it tends to be counted.
Basic salary (SAR)
Contractual allowances (housing, transport, schooling)
Bonuses and incentives
Business-owner income
End-of-service benefit
Lenders vary. What counts, and how much of it counts, depends on the lender, your residency status, the loan-to-value and the wider profile — one lender may include a full housing allowance while another excludes it, and a second lender may average a bonus across three years where the first used only the last year. These are common approaches seen across the market, not guaranteed terms, and we confirm the position with each lender before you apply.
Saudi salary certificates and employment contracts usually need attestation by the Ministry of Foreign Affairs and the UK embassy, so it is worth starting that early. The full pack is set out in our UK mortgage documents guide for US & Gulf expats.
Check which income counts for youDocuments checklist
Saudi applications are usually delayed by paperwork rather than credit. Lenders commonly ask for your passport and Iqama, a salary certificate on employer letterhead, three to six months of Saudi bank statements and documented evidence of where the deposit came from — with ID and supporting papers attested before you apply.
Lenders vary. Some accept a smaller pack, others ask for certified translations or a fresh attestation. The full pack, including US and UAE requirements and how certification works, is set out in our UK mortgage documents guide for US & Gulf expats.
See the full document guideIn short: many Saudi-based owners remortgage a UK property when a fixed rate ends, to release equity or after letting out a former home. Your current lender may not offer a new deal to overseas residents, and a remortgage is underwritten like a new application, with SAR income reassessed.
Expiring fixed rate
Switching lenders
Capital raising
Refinancing a former UK home
Saudi documents add attestation steps (Ministry of Foreign Affairs and the UK embassy), so start certification early — most remortgages complete within the same eight to fourteen weeks as a purchase.
Discuss remortgaging UK property from Saudi ArabiaIn short: a purchase turns on your deposit and where the money comes from; a remortgage turns on the existing loan, the current value of the property and how it is used. Both are underwritten on your Saudi package, and both usually need the same attested documents.
Main evidence
Affordability
Stamp duty
Valuation
Structure
Documents and attestation
Typical timing
Lenders vary. Which route is available to you, and on what terms, depends on the lender, your residency status, the loan-to-value and whether the property is occupied or let — one lender may fund a purchase on a 25% deposit where another asks for 35%, and some will not lend to applicants whose Iqama or contract has only months left to run. These are the common patterns we see, not guaranteed terms, and we confirm the position with each lender before you apply.
Compare buying and remortgaging optionsIn short: the riyal is pegged to the US dollar, not the pound, so the sterling cost of your UK mortgage moves with the US dollar rather than with Saudi Arabia.
The Saudi Central Bank (SAMA) maintains the official rate at 3.75 riyals to the US dollar and describes the peg as a strategic choice that has underpinned monetary and financial stability for more than three decades. In practice that means the riyal–pound rate you see is largely the US dollar–pound rate in disguise: if the pound strengthens against the dollar, your riyal salary converts into fewer pounds and your UK mortgage costs more each month, even though nothing has changed for you locally.
Because the riyal is fixed to the dollar, the riyal cost of a sterling payment moves one-for-one with the pound–dollar rate. Suppose a fixed monthly mortgage payment costs SAR 10,000 to cover today.
Illustrative arithmetic only, not an exchange rate or quote. The sterling payment itself is unchanged; only its riyal cost moves.
Official source: Saudi Central Bank (SAMA) — exchange rates. General information, not advice or a currency quote. For transfer options see our currency exchange for UK property and the UK currency hub.
In short: Saudi-based buyers can own UK rental property personally or through a UK limited company; lenders mainly assess expected rent, plus your income, deposit and experience.
With personal ownership you apply as an individual or joint applicant. With a UK limited company, usually a special purpose vehicle (SPV), the company owns the property and borrows; lenders commonly require personal guarantees from directors, and company and non-resident director eligibility are assessed separately. A company is not automatically better: consider tax on rental profits and on money taken out, running costs and future sale plans. Moving an existing property into a company can create tax and transaction costs. Offshore ownership structures (for example Jersey, Guernsey or BVI companies) are a specialist area with fewer lenders and need case-by-case review. Read our limited-company buy-to-let guide for expats.
Lenders vary. Evidence, income acceptance, residency requirements and terms depend on the lender and your circumstances. General preparation guidance, not an offer of finance.
Discuss a UK buy-to-let from Saudi ArabiaWorked example
Example based on lender rates approved 2 November 2026. 75% LTV, £100,000 deposit, capital and interest over 25 years.
| Product | Lowest rate* | Monthly repayment |
|---|---|---|
| Residential 2-year fixed | 5.64% | £1,867 |
| Residential 5-year fixed | 5.63% | £1,866 |
| Buy-to-let 2-year fixed | 5.69% | £1,876 |
| Buy-to-let 5-year fixed | 5.54% | £1,849 |
As a buy-to-let on a 5-year fix, the rent needed would be approx. £1,731 per month — speak to our team to confirm.
*Product fees may apply. Indicative only, not a quote or offer. The rate reverts to the lender's variable rate after the initial fixed period. Your home may be repossessed if you do not keep up repayments on your mortgage.
Hypothetical preparation examples, not completed client transactions, quotes or confirmed lender terms. The published Ealing case is shown near the top of this page.
Illustrative — not a completed transaction
British expat adding two Manchester units to a UK SPV portfolio, underwritten on rental cover at 75% LTV with no reliance on UK credit history.
Illustrative — not a completed transaction
SAR salary plus contractual housing allowance accepted; funded at 70% LTV interest-only through a lender's international division.
Illustrative — not a completed transaction
Non-British national resident in Dhahran refinancing an existing flat and releasing £180k at 65% LTV, supported by Saudi banking references and source-of-wealth evidence.
Recent transactions
Published transactions from our own case study library — select any to read the full brief.
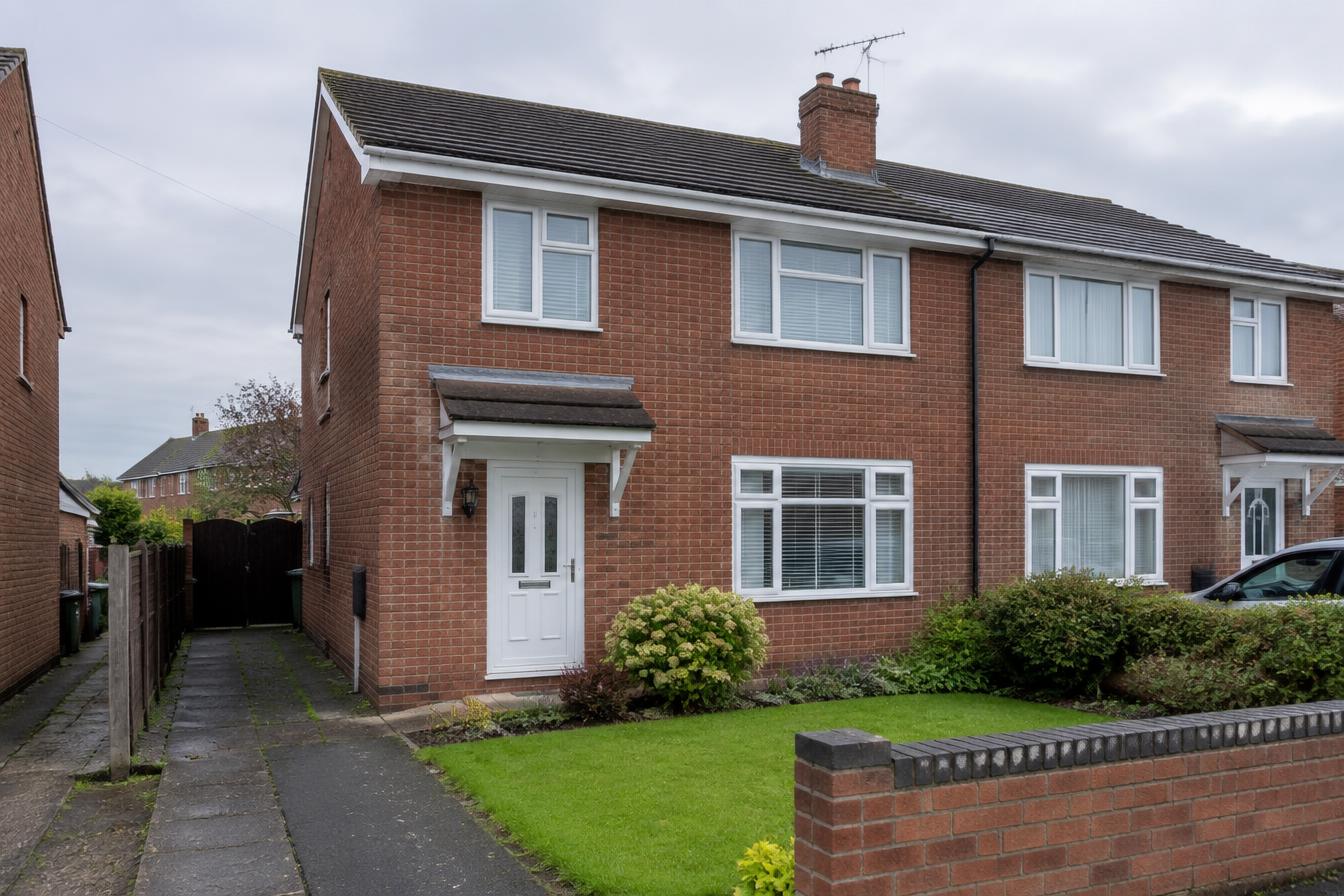
Birmingham · Expat first purchase
£290k purchase · 25% deposit · QAR income · first-time buyers
An illustrative example of how a British couple teaching in Doha could buy their first UK home — a £290,000 Birmingham semi — with a 25% deposit, Qatari riyal income and first-time buyer Stamp Duty relief, plus the 2% non-resident surcharge.
London · Expat BTL
£2.2m · 55% LTV · 25-year expat BTL
A Dubai-based investor secured a £2.2m buy-to-let mortgage on a prime London rental valued at approximately £4m — structured interest-only to preserve capital for wider investments.
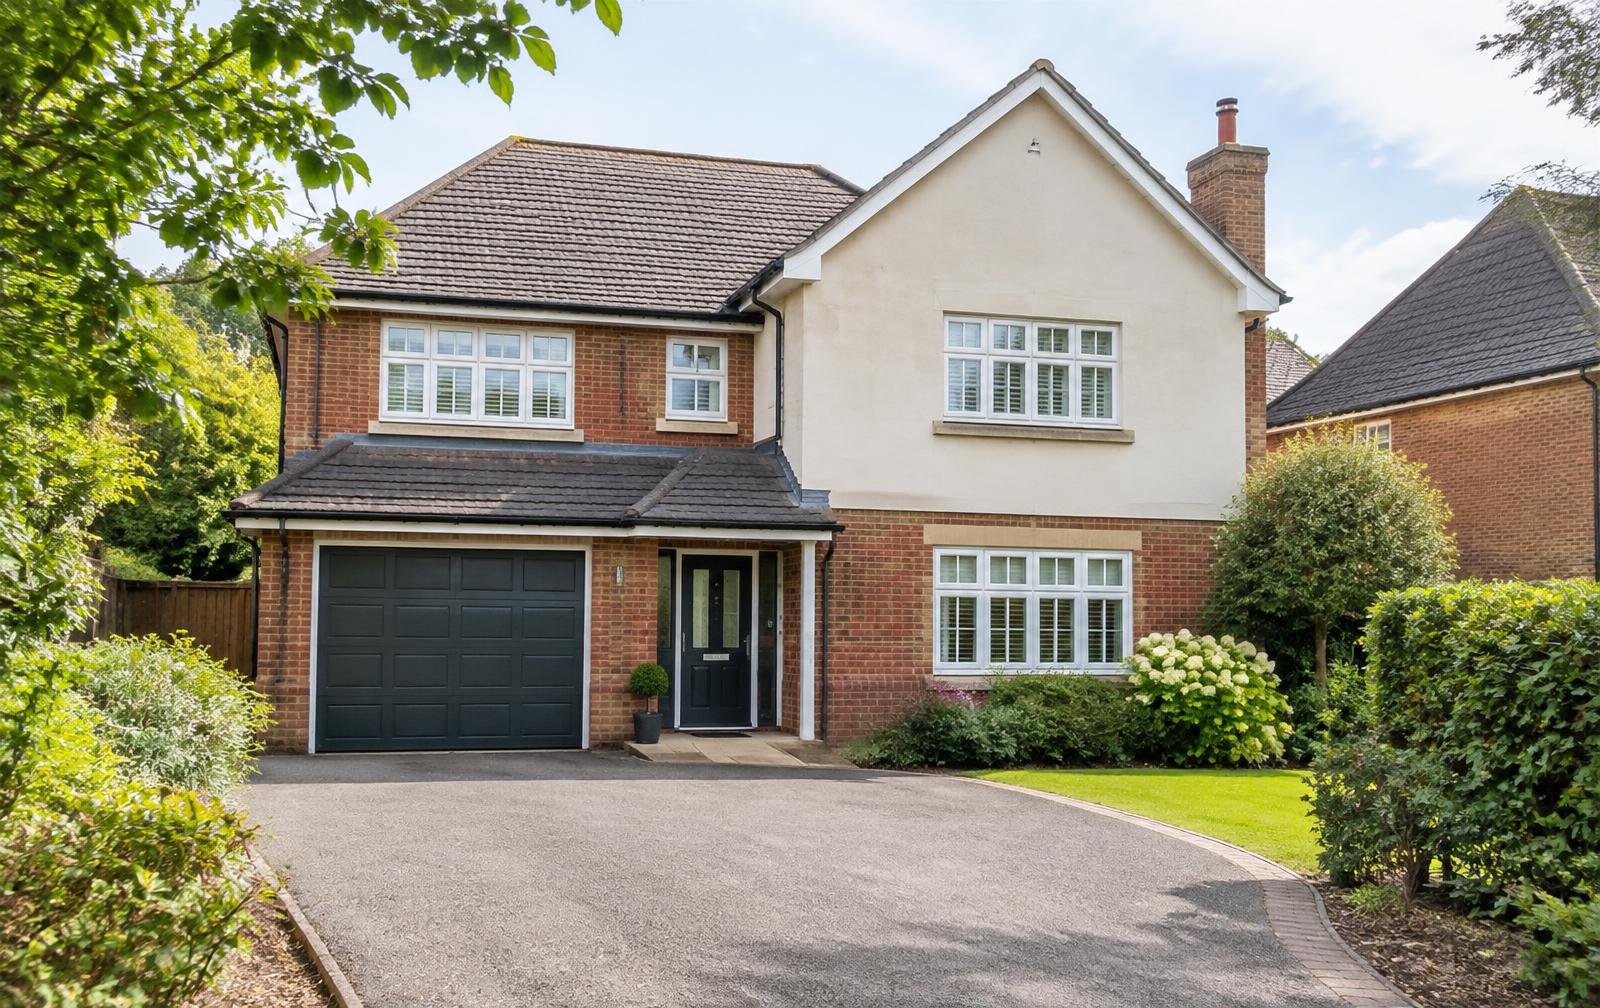
Milton Keynes · Bahrain-based expat
Reported £570k mortgage · ~£815k Milton Keynes purchase · 70% LTV · BHD income · no early repayment charges
Clifton Private Finance’s account reports a £570,000 residential mortgage at about 70% loan-to-value for a British expat in Bahrain buying a Milton Keynes home, with income paid entirely in Bahraini dinar, limited recent UK credit and shipyard employment.
Why clients choose us
Dollar-pegged riyal income considered by lenders active across the Gulf, converted to sterling with any currency adjustment set by the lender.
Housing, transport and schooling allowances included where contractual — frequently decisive on affordability.
Foreign nationals resident in the Kingdom on an Iqama, not just British passport holders, placed with the right lenders.
Al Rajhi, SNB, Riyad Bank and SAB references used in place of a UK credit footprint.
Practical support with MoFA and embassy attestation so certification does not delay your offer.
Advisers who work to Saudi hours and the Gulf working week, with WhatsApp and scheduled calls.
Contributor
James co-founded Clifton and has spent more than a decade building a specialist property finance business covering residential mortgages, bridging, development finance and complex international cases.
Short-term option · indicative
A standard expat mortgage takes around 8–14 weeks, and Saudi document attestation can add time. When a deadline won't wait — an auction completion, a chain break, or buying before funds arrive from Saudi Arabia — UK bridging finance is the faster route. It is underwritten on the UK property and a documented exit rather than monthly affordability.
Bridging is short-term and costs more than a mortgage. See UK bridging loans for expats and non-residents. Indicative ranges, not live lender pricing.
Ask whether bridging fits your timescaleFrequently asked
Yes. Expats living and working in Riyadh, Jeddah, Dhahran, KAUST and NEOM can arrange UK residential and buy-to-let mortgages. Saudi Arabia is an accepted jurisdiction for the international divisions and private banks we work with, and no UK residency is required.
Yes. The riyal is pegged to the US dollar, so lenders treat SAR much like AED and USD, Lenders convert SAR income into sterling for affordability and may reduce the converted figure to allow for currency risk; how much varies by lender.
Plan on 25–40%. Eligible products can go up to 80% loan-to-value, which means a possible 20% deposit, but most Saudi-based buyers should budget for 25–40%. A larger deposit can give you more lender choice; the exact requirement depends on the lender and your profile.
Gross salary is effectively net, and lenders assess it directly. What matters is documentation: an employment contract, salary certificate and matching credits into a Saudi bank account such as Al Rajhi, SNB, Riyad Bank or SAB.
Usually yes. Saudi packages routinely include housing, transport and schooling allowances; lenders accept these at 50–100% where they are contractual and appear on payslips.
End-of-service benefit is generally viewed as an accrued asset supporting the overall profile rather than as recurring income. It can help demonstrate liquidity and source of deposit.
No. Lenders active with Gulf clients underwrite documented income, assets and Saudi banking references. Thin UK files are normal in this segment and are not a barrier with the right lender.
Yes. A UK SPV limited company is the standard route for buy-to-let. Offshore structures, such as Jersey, Guernsey or BVI companies, are a specialist area with fewer lenders and are reviewed case by case, with full beneficial-ownership and source-of-wealth checks.
In England and Northern Ireland, the 2% non-resident surcharge applies when any buyer was not in the UK at the end of at least 183 days in the 12 months before the purchase (days anywhere in the UK count). If either spouse or civil partner buying together meets the test, both are treated as UK resident. If you later spend 183 days in the UK within a continuous 365-day period between 364 days before and 365 days after the purchase, you may be able to claim a refund within two years. The surcharge sits on top of standard rates and any additional-property surcharge. Scotland (LBTT) and Wales (LTT) have separate rules. See HMRC's SDLT guidance for non-UK residents.
Often, yes. Expat bridging can complete in around 3–5 weeks, at an indicative 0.65%–1.00% per month and usually up to about 70% loan-to-value, with a planned exit such as refinancing onto a term mortgage. Indicative ranges, not live pricing.
Because the riyal is pegged to the dollar, a fixed sterling payment that costs SAR 10,000 today would cost about SAR 11,000 — a 10% rise. If the pound fell 10%, it would cost about SAR 9,000. Illustrative arithmetic, not a quote.
Yes. Expat remortgages and capital raising are common for Saudi-based clients — releasing equity for a further purchase, restructuring a portfolio, or moving off an expiring product onto better expat terms.
Typically eight to fourteen weeks. Saudi document attestation via the Ministry of Foreign Affairs and the UK embassy adds time, so we start ID and income certification early. Bridging can complete much faster where a deadline is fixed.
Passport, Iqama (residence permit), employment contract and salary certificate, three to six months of Saudi bank statements, source-of-deposit evidence, and attested or notarised ID copies. Business owners should add commercial registration and audited accounts.
Currency exchange
Expat buyers moving dollars, dirhams, riyals or euros into the UK can lose thousands to bank margins and rate moves. We introduce you to an FCA-authorised currency specialist who plans your transfer around exchange and completion.
Clifton introduces clients to a specialist currency partner and does not hold, convert or transfer client funds.
Explore the currency service
Request a live quoteUK expat finance
Related UK services
Residential, buy-to-let and high-value mortgages for UK and international clients.
Learn moreFast short-term funding for auctions, chain-breaks, refurbishments and exits.
Learn moreSenior debt and stretched-senior facilities for residential and mixed-use schemes.
Learn moreInvestment and owner-occupier funding for offices, hospitality, retail and logistics.
Learn moreImproved terms, capital raising and exit refinance for maturing UK facilities.
Learn moreReady to explore your options?
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.