£1.2m Ealing home mortgage for a UK expat working in Saudi Arabia
Reported £1.2m mortgage · ~£2.03m Ealing purchase · Saudi income with allowances and bonuses
In short
Can a UK expat working in Saudi Arabia get a £1.2m London mortgage?
Yes. Clifton Private Finance’s July 2023 account reports a £1.2m residential mortgage for a UK couple buying a larger Ealing home for about £2.03m, assessed on the husband’s Saudi Aramco income including bonuses and housing, living and school-fee allowances. This is an attributed external case, not a Clifton International deal.
- Location: Ealing, West London. Finance type: Expat residential mortgage for a UK national working in Saudi Arabia.
- Headline terms: Reported £1.2m mortgage · ~£2.03m Ealing purchase · Saudi income with allowances and bonuses.
- According to Clifton Private Finance’s July 2023 account, a married couple, both UK nationals, wanted to move from their Ealing home to a larger house nearby on the market for about £2.03m. The wife lived in the family home while the husband worked in Saudi Arabia for Saudi Aramco, and the mortgage was to be based on his income alone. His package combined basic salary with performance bonuses, accommodation and living allowances and an allowance for children’s school fees. The couple had not decided whether to sell their existing home or let it out.
- The lender took a holistic view of the overseas earnings and the family’s position, and the couple proceeded with the purchase of their larger Ealing home. This is a historical, case-specific account dated July 2023, not evidence of current terms or a guarantee that another Saudi-based applicant will qualify.
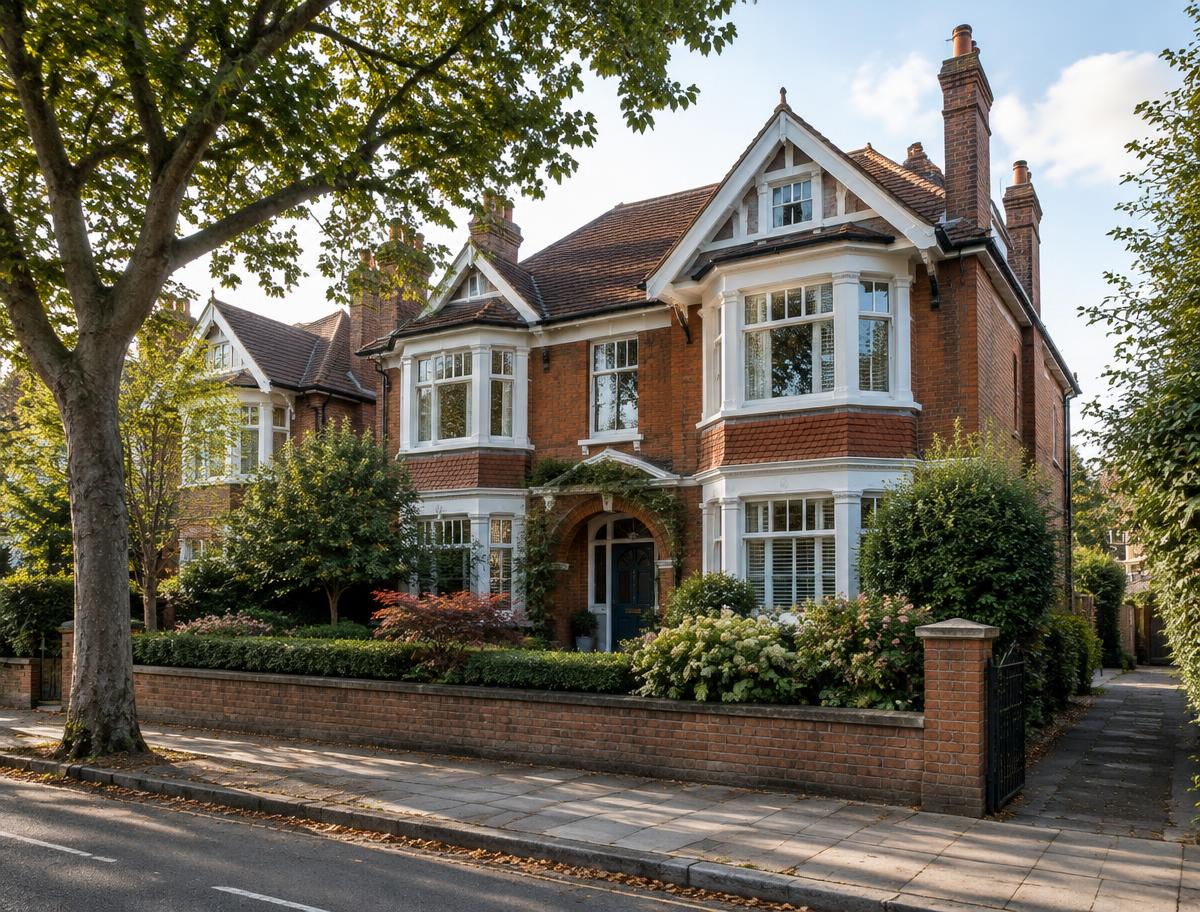
Illustrative property image — not the clients’ actual property.
- Reported mortgage
- £1,200,000
- Purchase price reported
- About £2,030,000
- Source account date
- July 2023
- Income
- Saudi-based salary, bonuses and allowances
- Borrowers
- UK nationals; husband working in Saudi Arabia
- Location
- Ealing, West London
- Challenge
- According to Clifton Private Finance’s July 2023 account, a married couple, both UK nationals, wanted to move from their Ealing home to a larger house nearby on the market for about £2.03m. The wife lived in the family home while the husband worked in Saudi Arabia for Saudi Aramco, and the mortgage was to be based on his income alone. His package combined basic salary with performance bonuses, accommodation and living allowances and an allowance for children’s school fees. The couple had not decided whether to sell their existing home or let it out.
- Solution
- Clifton Private Finance, the arranging team named in the original account, approached lenders experienced with expatriates in Saudi Arabia and the wider Middle East, presenting the strength of the employment, the full remuneration package and the plan for the existing Ealing home — to be sold or let — so lenders could assess ongoing commitments. Clifton International publishes an attributed summary of that external account; this is not a Clifton International transaction.
- Funding structure
- The source reports £1.2m raised as a residential mortgage towards a purchase of about £2.03m in West London, assessed on the husband’s sole Saudi-based income. Historical rates and fees are intentionally not reproduced; the lender, term and exact loan-to-value are not published.
- Outcome
- The lender took a holistic view of the overseas earnings and the family’s position, and the couple proceeded with the purchase of their larger Ealing home. This is a historical, case-specific account dated July 2023, not evidence of current terms or a guarantee that another Saudi-based applicant will qualify.
Case evidence, sources and limitations
Source: Clifton Private Finance, ‘London Residential Mortgage For UK Expat in Saudi Arabia’, dated July 2023. Clifton Private Finance is the arranging team named in the account. Clifton International publishes an attributed summary only and did not arrange this transaction. Figures are reported case facts, not independently audited data.
Historical interest rates and fees are intentionally omitted and must not be treated as current pricing. The source does not identify the lender, term, repayment basis or exact loan-to-value. The image is illustrative, not the clients’ property. Eligibility and terms require individual assessment; your home may be repossessed if you do not keep up repayments.
Case narrative updated . This is an editorial date, not the completion date.
- Clifton Private Finance — original Saudi expat Ealing case (July 2023)
Original published account, including the reported £1.2m raised, the ~£2.03m purchase and the Saudi income package. Its historical pricing is not reproduced here.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£380,000 buy-to-let remortgage for UK expats in the US paid in dollars
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
FAQs
Questions on this case
- Can Saudi allowances count towards a UK mortgage?
- They can. In this case the lender considered a package including bonuses and housing, living and school-fee allowances, not just basic salary. How much of each allowance counts varies by lender.
- Does it matter whether I sell or let my existing UK home?
- Yes. Lenders need to know your ongoing commitments, so the plan to sell or let the existing Ealing home was set out clearly in the application.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.