£380,000 buy-to-let remortgage for UK expats in the US paid in dollars
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
In short
Can UK expats living in the US and paid in dollars remortgage a UK buy-to-let?
A married couple living in San Francisco and paid largely in US dollars remortgaged their Oxford buy-to-let, valued at approximately £1.29 million, raising £380,000. A lender experienced in expat cases assessed their dollar income, and alternative documents replaced a traditional employer reference.
- Capital raised: £380,000 against an Oxford buy-to-let valued at approximately £1.29 million.
- Clients: UK expat couple in San Francisco; senior US employment plus a UK consultancy run remotely.
- Income: largely paid in US dollars.
- Lender, rate, term, total loan and LTV not disclosed.
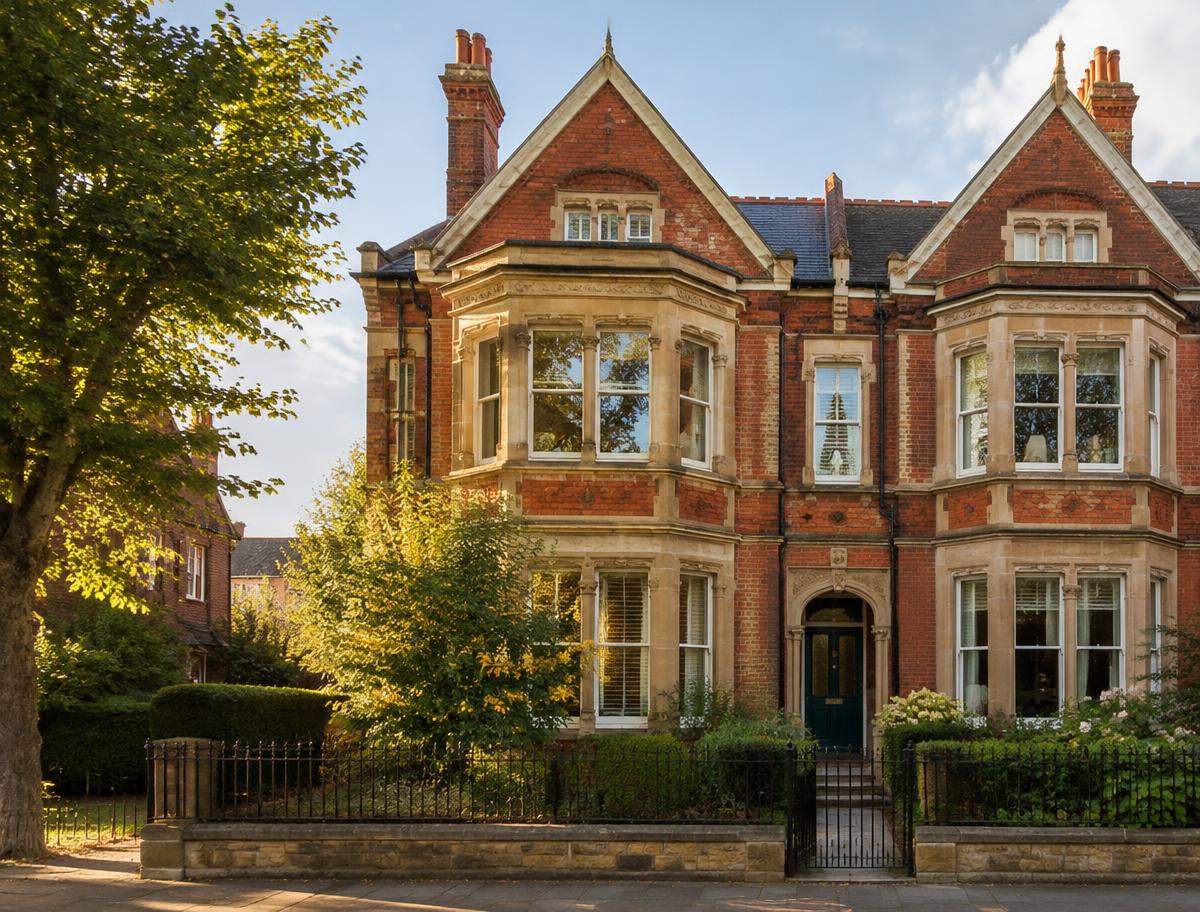
Illustrative property image — not the clients’ actual property.
- Capital raised
- £380,000
- Property value
- Approx. £1.29m
- Income currency
- US dollars (USD)
- Property type
- Buy-to-let
- Clients based in
- San Francisco, US
- Location
- Oxford
- Challenge
- A married couple who had moved to California several years earlier wanted to remortgage their Oxford property, let out since their move, and raise additional capital. One applicant held a senior role with a major American media company; the other ran a UK consultancy remotely from the US. Household income was strong but largely paid in US dollars, and the combination of non-UK residence, overseas employment and foreign-currency income sat outside many mainstream lenders' criteria. Existing borrowing was modest relative to the property's value of approximately £1.29 million.
- Solution
- Clifton International facilitates introductions to specialist property finance teams, rather than acting as lender or mortgage adviser. In the supplied account, the specialist team reviewed residency, employment and income sources, then approached lenders experienced with expat cases able to take a bespoke view of US dollar income. When the US employer could not provide a traditional employment reference because records were held electronically, alternative supporting documentation satisfied the lender. Identity checks were coordinated while the clients were visiting the UK.
- Funding structure
- A buy-to-let remortgage of the Oxford property, valued at approximately £1.29 million, raising £380,000 of additional capital, assessed on US dollar household income from employment and a UK consultancy run from the US. The account does not specify the total new loan, loan-to-value, rental income, interest rate, fees, term or repayment basis.
- Outcome
- The remortgage completed, raising £380,000 while the clients kept ownership of their Oxford investment property. This is a reported case-specific outcome, not a guarantee of approval, borrowing capacity or timing for other applicants.
Case evidence, sources and limitations
Source: the anonymised case-study account supplied by Clifton Private Finance. Figures and outcomes are reported case facts, not independently audited market data. Clifton International presents the account as an introducer, not as lender or mortgage adviser.
The total new loan, loan-to-value, rental income, lender identity, currency adjustment, interest rate, fees, term, repayment basis and timescale are not supplied. £380,000 is the capital raised, not the total mortgage. The property value is approximate. The photo is illustrative, not the clients' actual property. Lender criteria and affordability vary. Your property may be repossessed if you do not keep up repayments on your mortgage.
Case narrative updated . This is an editorial date, not the completion date.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£500,000 mortgage for US citizens buying a second home in Paddington, London
Reported £500k mortgage · ~£1.6m new-build Paddington apartment · about 31% LTV · US dollar income
FAQs
Questions on this case
- Can UK expats in the US raise capital on a UK buy-to-let?
- Some lenders experienced in expat cases will consider it. In this reported Oxford case, a couple in San Francisco paid in US dollars raised £380,000 against a buy-to-let valued at approximately £1.29 million. Each application is assessed individually.
- Was £380,000 the total mortgage?
- No. £380,000 was the additional capital raised. The total new loan and loan-to-value are not disclosed in the supplied account.
- What if a US employer will not give a traditional employment reference?
- In this case the employer held records electronically and did not provide a traditional reference, so alternative supporting documentation was provided and accepted by the lender. Requirements vary by lender.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.