£500,000 mortgage for US citizens buying a second home in Paddington, London
Reported £500k mortgage · ~£1.6m new-build Paddington apartment · about 31% LTV · US dollar income
In short
Can US citizens get a UK mortgage for a second home in London?
Yes. Clifton Private Finance reports a £500,000 mortgage on an approximately £1.6 million new-build apartment in Paddington, London, for a married American couple paid in US dollars — about 31% loan-to-value, derived from the reported figures. This is an attributed external case, not a Clifton International deal.
- Borrowers: married American couple, late forties, employed with US-based salaries.
- Purchase: new-build apartment in Paddington, London, valued at about £1.6 million, bought as a second home.
- Reported mortgage: £500,000 — about 31% loan-to-value, derived from the reported figures.
- Hurdles: US citizenship, US dollar income, non-UK residence and a second-home purchase.
- Source: attributed Clifton Private Finance account; lender, rate and fees not published.
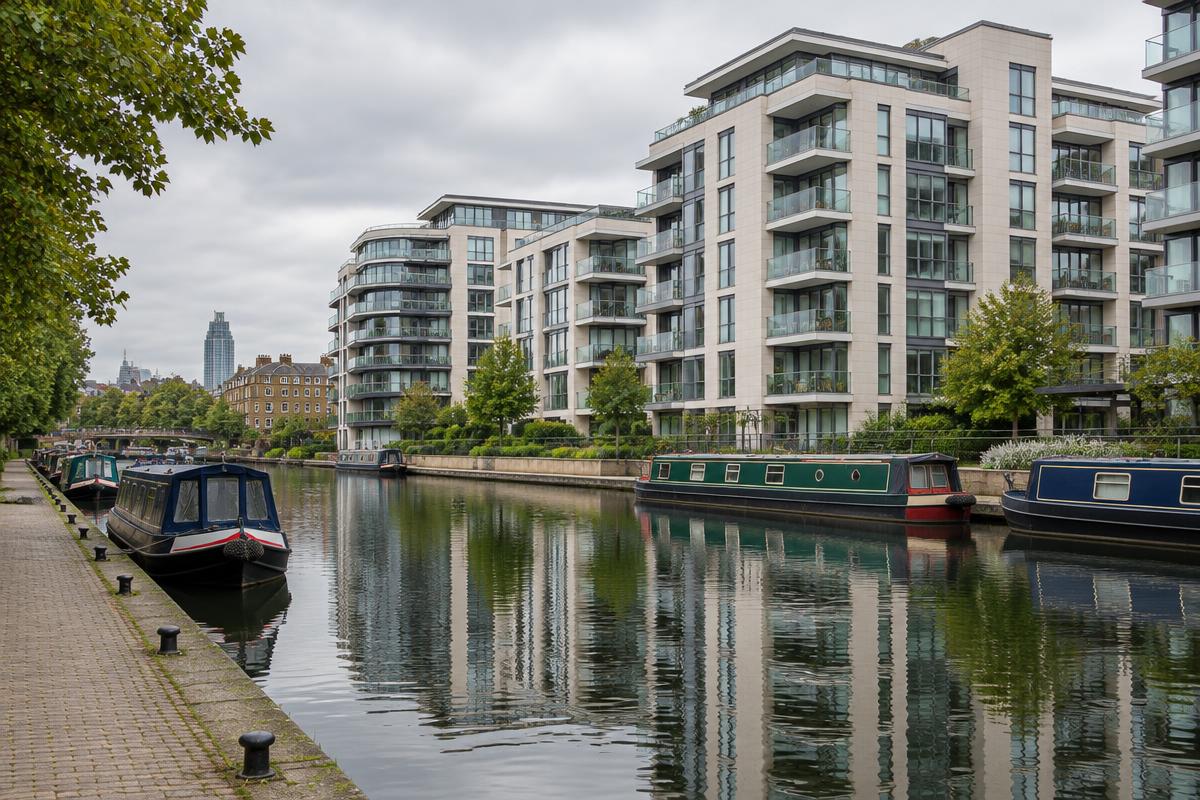
Illustrative property image — not the clients’ actual property.
- Reported mortgage
- £500,000
- Property value reported
- About £1.6m
- Loan-to-value
- About 31% (derived)
- Income currency
- US dollars (USD)
- Borrower
- Married American couple, employed in the US
- Property type
- New-build second home
- Location
- Paddington, London
- Challenge
- According to Clifton Private Finance’s account, a married American couple in their late forties, employed with US-based salaries, wanted a second home in London. They had identified a new-build apartment in Paddington with a purchase price of approximately £1.6 million and needed a £500,000 mortgage to complete the purchase. The property was still under development, adding time pressure. Their profile sat outside standard criteria for several lenders: US citizenship, income earned in US dollars, non-UK residence, verification of overseas income and a second-home rather than main-residence purchase.
- Solution
- Clifton Private Finance, the arranging team named in the original account, structured the application around the clients’ strengths: strong US-based incomes, significant personal wealth, a clear intention to establish a London base and a modest loan relative to the property value. An international lender experienced with overseas borrowers was identified and accepted the couple’s US citizenship, US dollar income, non-UK residency and second-home ownership. Clifton International publishes an attributed summary of that external account; this is not a Clifton International transaction.
- Funding structure
- The source reports a £500,000 residential mortgage against a new-build Paddington apartment purchased for approximately £1.6 million — a loan-to-value of about 31%, derived from those reported figures. Affordability was assessed on US dollar employment income. The lender, interest rate, fees, term, repayment basis and completion timescale are not published.
- Outcome
- The mortgage completed and the couple established a London base while keeping their primary residence and careers in the United States. This is a reported case-specific outcome, not evidence of current terms or a guarantee of approval for other US-citizen applicants.
Case evidence, sources and limitations
Source: Clifton Private Finance, ‘Mortgage Secured for US Nationals Purchasing Second Home in the UK’. Clifton Private Finance is the arranging team named in the account. Clifton International publishes an attributed, adapted summary only and did not arrange this transaction. Figures are reported case facts, not independently audited data.
The source does not identify the lender, interest rate, fees, term, repayment basis or completion timescale, and no rate is implied here. The loan-to-value is derived from the reported £500,000 mortgage and approximate £1.6 million purchase price. The image is illustrative, not the clients’ property. Eligibility and terms require individual assessment; your home may be repossessed if you do not keep up repayments.
Case narrative updated . This is an editorial date, not the completion date.
- Clifton Private Finance — original US nationals second-home case
Original published account, including the reported £500,000 mortgage, the ~£1.6 million new-build Paddington apartment, US dollar salaries and the second-home purchase.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£380,000 buy-to-let remortgage for UK expats in the US paid in dollars
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
FAQs
Questions on this case
- Can US citizens get a UK mortgage?
- Yes. Specialist lenders and international banks can consider US citizens purchasing UK property, subject to affordability, deposit and underwriting. In this reported case a married American couple secured £500,000 towards a London second home.
- Do UK lenders accept US dollar income?
- Some do. Criteria vary significantly between lenders, and foreign-currency income is usually assessed with a lender-specific conversion adjustment. In this case both applicants were employed in the US and paid in US dollars.
- Can Americans buy a second home in the UK?
- Yes. Specialist lenders can consider second-home purchases by non-UK residents, as in this reported Paddington case. The 2% non-resident SDLT surcharge and any additional-property surcharge may apply.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.