How did a British couple use UK property equity to fund a move to France?
In this real client case, our sister brokerage, Clifton Private Finance, arranged £35,000 of second-charge finance on a Rugby, Warwickshire home valued at approximately £365,000, funding a Normandy purchase before an intended UK sale. One applicant was a self-employed designer. This historical relocation case is not a France-resident euro-income mortgage approval.
Location: Rugby, Warwickshire → Normandy, France. Finance type: Second-charge finance secured on a UK home for relocation to France.
The couple found a home in rural Normandy sooner than expected and needed a further £35,000 to complete the purchase. Much of their capital was tied up in their UK home, which had a small existing mortgage. The husband was a self-employed designer working internationally and planned to continue his business after relocating. They needed to buy before the eventual UK sale released their equity.
The finance supplied the additional funds needed for the Normandy purchase. Sale of the UK home was the intended repayment route; the account does not establish that the later sale or repayment had completed. This outcome does not guarantee finance for another relocating or France-resident applicant. Property offered as security is at risk if repayments are not maintained.
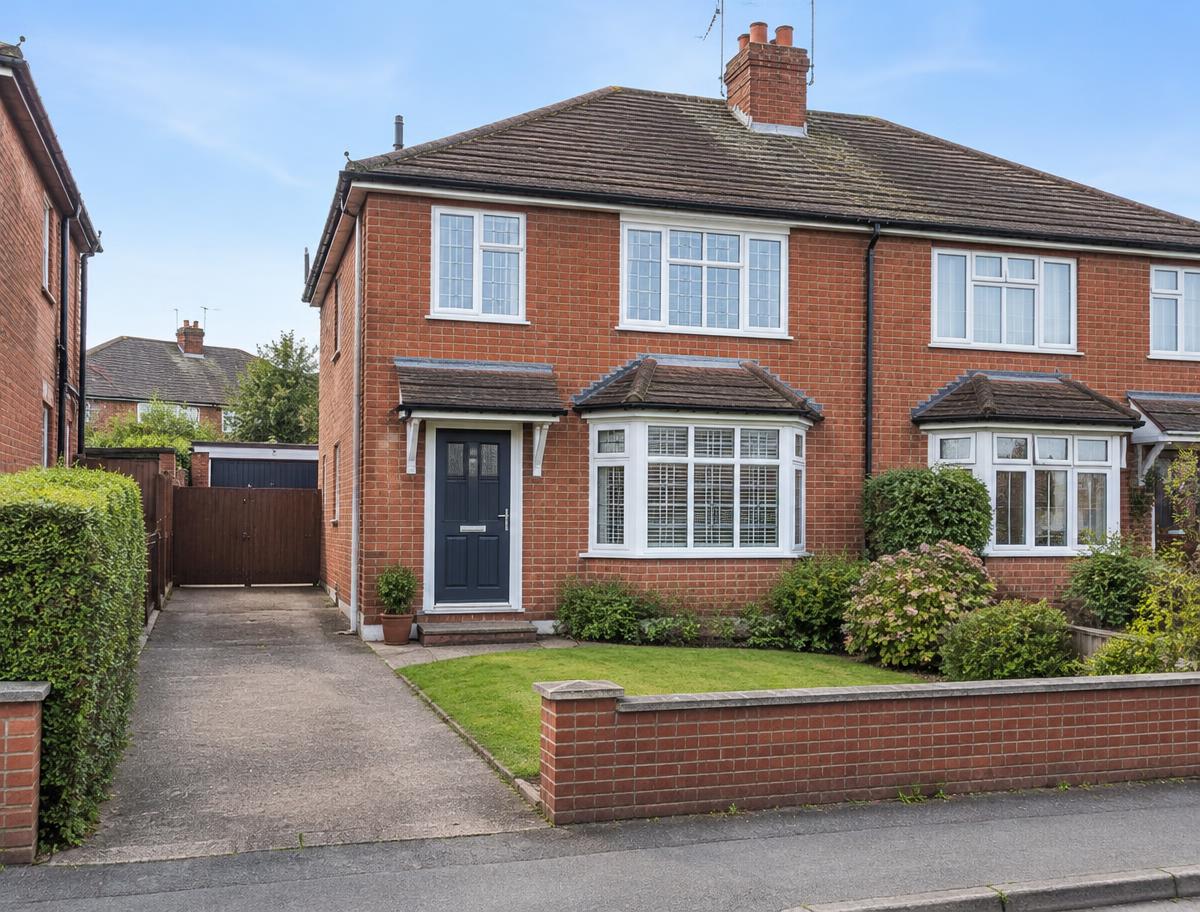
Illustrative property image — not the clients’ actual property.
Finance raised
£35,000
UK home valuation
Approximately £365,000
UK property location
Rugby, Warwickshire
Destination
Normandy, France
Applicant work
Self-employed designer
Security
Second charge on UK home
Planned repayment
Sale of UK home
Challenge
The couple found a home in rural Normandy sooner than expected and needed a further £35,000 to complete the purchase. Much of their capital was tied up in their UK home, which had a small existing mortgage. The husband was a self-employed designer working internationally and planned to continue his business after relocating. They needed to buy before the eventual UK sale released their equity.
Solution
Our sister brokerage, Clifton Private Finance, arranged second-charge finance against the existing Rugby home without replacing the first mortgage. A desktop automated valuation, simplified underwriting and joint legal representation supported the process in this case. These were case-specific arrangements, not standard eligibility promises. This is an attributed summary, not a Clifton International transaction.
Funding structure
The reported finance raised was £35,000 against a UK home assessed at approximately £365,000. The UK home is in Rugby, Warwickshire, as confirmed by James Caldwell. The original calls the facility a second-charge bridging loan. The existing first-mortgage balance is not specified, so combined LTV cannot be calculated. No lender, rate, fees, term or exact completion duration is published here.
Outcome
The finance supplied the additional funds needed for the Normandy purchase. Sale of the UK home was the intended repayment route; the account does not establish that the later sale or repayment had completed. This outcome does not guarantee finance for another relocating or France-resident applicant. Property offered as security is at risk if repayments are not maintained.
Source: Clifton Private Finance, ‘Quick desktop property valuation on 2nd charge mortgage secures dream home for a relocation to France’, October 2020. This is a real client case arranged by our sister brokerage, Clifton Private Finance. Clifton International publishes an attributed summary and did not arrange this transaction. James Caldwell confirms the UK property location as Rugby, Warwickshire. Our publication dates are editorial dates, not transaction dates.
This concerns clients preparing to relocate, not established French residents applying on EUR income. The original describes a second-charge bridging loan. Combined LTV, lender, rate, fees, term and exact completion duration are not inferred. The UK sale was a planned repayment route, not a verified completed repayment. The property photo is illustrative.
Case narrative updated . This is an editorial date, not the completion date.
Original account supporting £35,000 raised, approximately £365,000 UK valuation, self-employed designer, desktop valuation, Normandy purchase and planned UK-sale repayment. UK property location confirmed by James Caldwell as Rugby, Warwickshire; historical pricing is omitted.
Oliver is a co-founder and Director, called to the Bar at Lincoln's Inn, a Chartered Financial Planner and a member of the Society of Trust & Estate Practitioners.
No. It concerns a couple preparing to relocate, including a self-employed designer working internationally. It does not establish eligibility for a France-resident applicant paid in euros.
The couple intended to repay the finance from a later sale of their UK home. The account does not verify that the sale or repayment subsequently completed.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.