£840,000 bridging loan for a family returning to the UK from Asia
£840,000 raised · Surrey family home · purchase completed within four weeks
In short
How did a family returning to the UK from Asia buy their Surrey home before a mortgage was possible?
A family who had recently returned to the UK after living in Asia used an £840,000 bridging loan to buy their Surrey family home, completing within approximately four weeks. The bridge was repaid a few months later once a mainstream residential mortgage was arranged.
Location: Surrey. Finance type: Bridging finance to buy a UK family home before a residential mortgage was possible.
Headline terms: £840,000 raised · Surrey family home · purchase completed within four weeks.
After an extended period living and working overseas in Asia, the family identified a Surrey home that met their long-term needs. Despite strong finances, they had only recently returned to the UK and did not yet satisfy mainstream lenders' requirements on UK residency history, recent banking activity and credit footprint. Waiting for a conventional mortgage application to become viable risked losing the property to another buyer.
The purchase completed within approximately four weeks, as reported in the source, and the family moved in. Once settled with sufficient time back in the UK, a residential mortgage was arranged through a mainstream lender and the bridge was repaid a few months later. This case-specific outcome is not a guarantee of another applicant's eligibility, completion timing or mortgage exit.
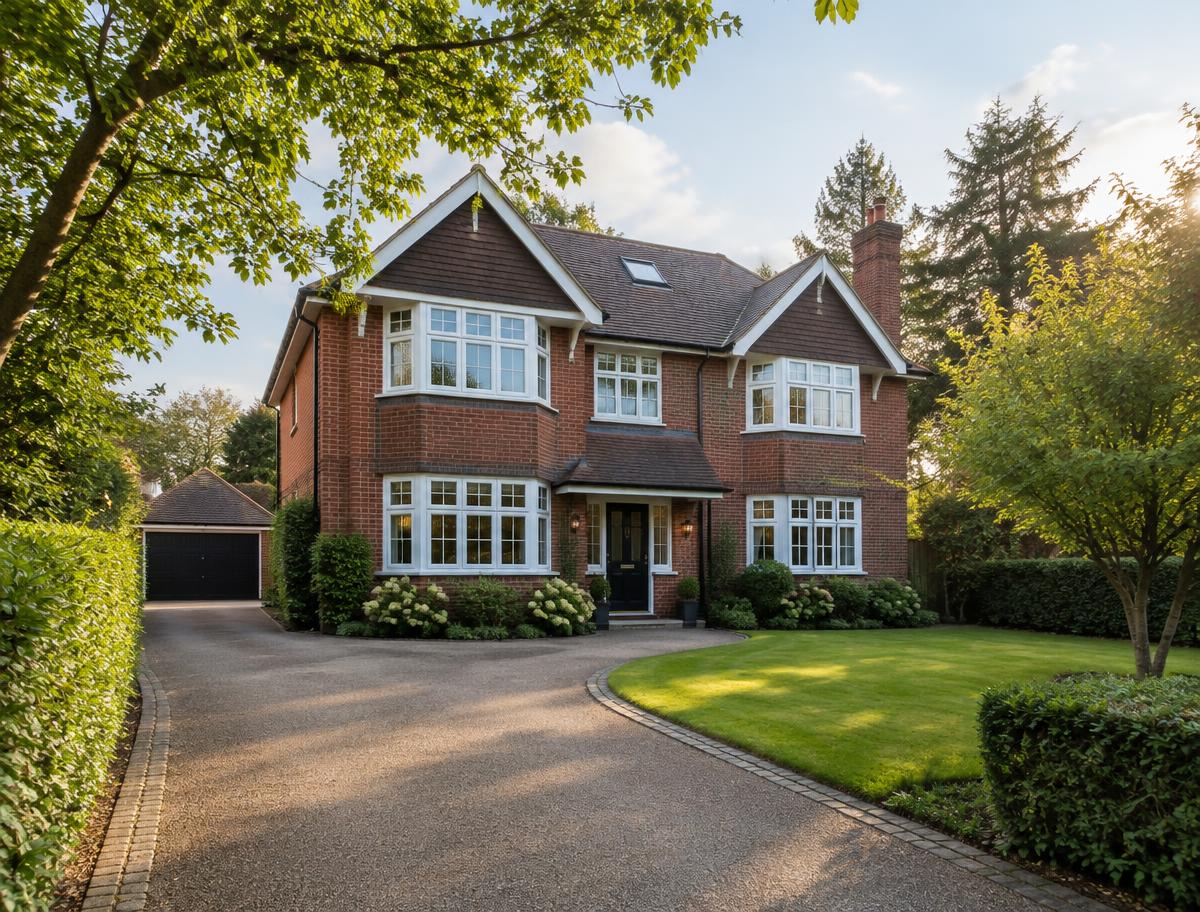
Illustrative property image — not the clients’ actual property.
Finance raised
£840,000
Client profile
Returning expat family from Asia
UK property location
Surrey
Reported completion
Within four weeks
Exit
Residential mortgage, repaid a few months later
Challenge
After an extended period living and working overseas in Asia, the family identified a Surrey home that met their long-term needs. Despite strong finances, they had only recently returned to the UK and did not yet satisfy mainstream lenders' requirements on UK residency history, recent banking activity and credit footprint. Waiting for a conventional mortgage application to become viable risked losing the property to another buyer.
Solution
Bridging finance placed the family in a cash-buyer position. The facility covered the acquisition of the Surrey property, reassured the vendor that funding was in place and let the transaction proceed quickly while the family re-established UK residency. This is an attributed summary of an external account, not a Clifton International transaction.
Funding structure
An £840,000 bridging loan covered the purchase of the Surrey family home. Property value, LTV, lender, rate, fees and exact term are not published in the source; no figures are inferred for them. Bridging finance is short term and normally more expensive than a mortgage; property offered as security is at risk if repayments are not maintained.
Outcome
The purchase completed within approximately four weeks, as reported in the source, and the family moved in. Once settled with sufficient time back in the UK, a residential mortgage was arranged through a mainstream lender and the bridge was repaid a few months later. This case-specific outcome is not a guarantee of another applicant's eligibility, completion timing or mortgage exit.
Source: Clifton Private Finance, ‘Bridging Loan To Purchase Family House In Surrey’, September 2020. This is an attributed account arranged by our sister brokerage, Clifton Private Finance. Clifton International publishes an adapted summary and did not arrange this transaction. Our publication dates are editorial dates, not transaction dates.
Property value, LTV, lender, rate, fees and exact term are not published; nothing is inferred. The four-week completion and the later mortgage repayment are reported in the source and are not a guarantee of future outcomes. Bridging finance is short term; approval, timing and the exit are not guaranteed. The property photo is illustrative.
Case narrative updated . This is an editorial date, not the completion date.
Original account supporting £840,000 raised, the Surrey location, the recent return from living and working as expats in Asia, the four-week completion and the later repayment via a high-street mortgage.
Oliver is a co-founder and Director, called to the Bar at Lincoln's Inn, a Chartered Financial Planner and a member of the Society of Trust & Estate Practitioners.
Sometimes, but many lenders prefer an established period of UK residency and recent UK financial history before approving a residential mortgage. This family bridged the gap instead.
Yes. Bridging loans are commonly used by returning British expats who need to purchase quickly before a mainstream mortgage becomes available. Approval, timing and the exit are not guaranteed.
Yes. In this case a residential mortgage was placed with a mainstream lender a few months after completion and the bridge was repaid from its proceeds.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.