First UK home for British teachers in Qatar: a £290K Birmingham purchase
£290k purchase · 25% deposit · QAR income · first-time buyers
In short
Can British expats in Qatar buy their first UK home with a mortgage?
Yes, though lender choice is narrower. This illustrative example shows a British couple teaching in Doha buying a £290,000 Birmingham home with a 25% deposit (£72,500) and a £217,500 mortgage, using QAR income converted to sterling. First-time buyer Stamp Duty relief can apply because they have never owned property anywhere, with the 2% non-resident surcharge on top.
- Buyers: British nationals living and working in Qatar; income in Qatari riyal (QAR).
- Purchase: £290,000 Birmingham semi-detached home; 25% deposit of £72,500.
- Illustrative mortgage: £217,500 at 75% LTV; foreign income converted to sterling with a currency adjustment.
- Status: illustrative worked example, not a completed transaction.
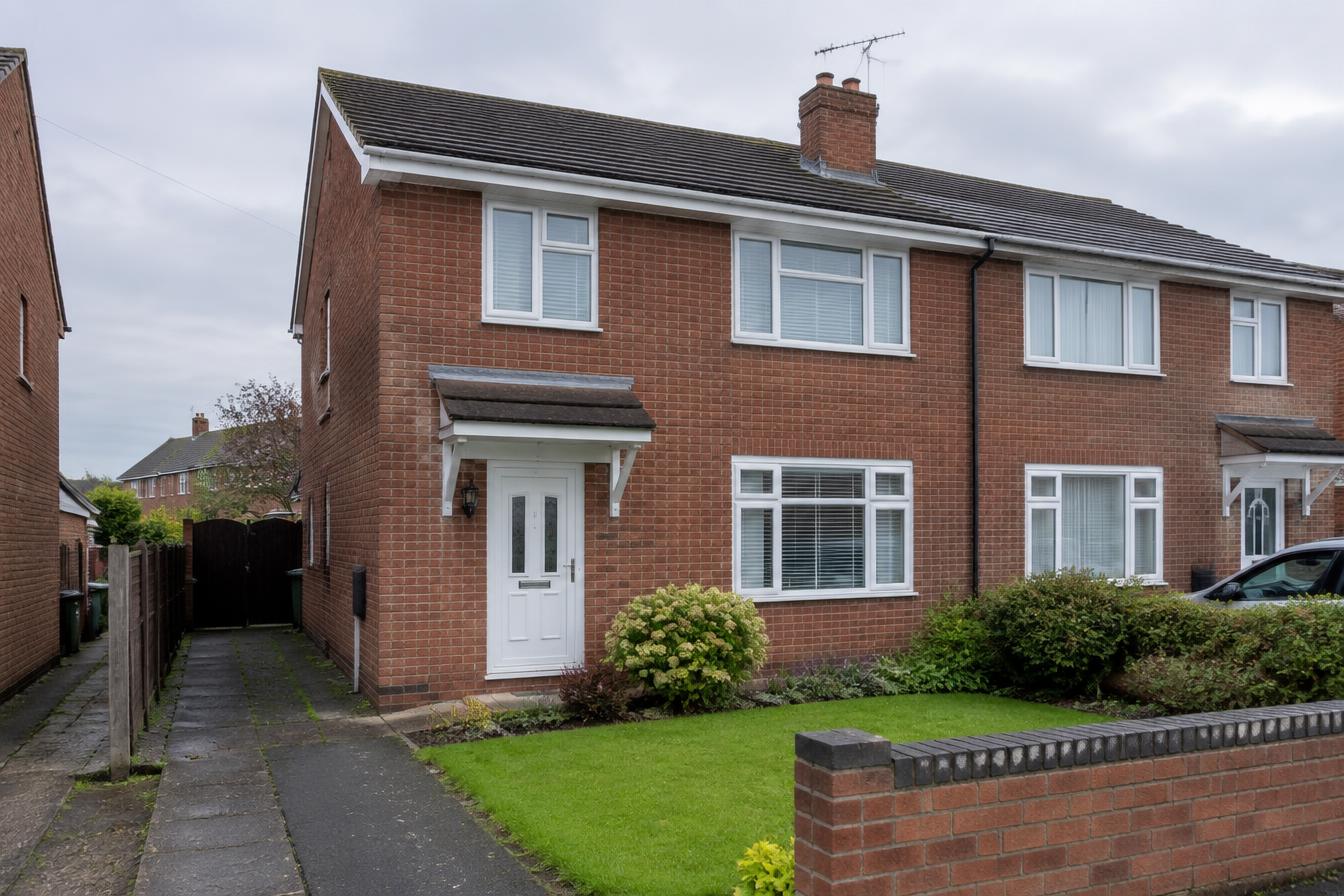
Illustrative property image — not the clients’ actual property.
- Purchase price
- £290,000
- Deposit
- £72,500 (25%)
- Illustrative mortgage
- £217,500
- Buyers
- British first-time buyers in Qatar
- Income currency
- Qatari riyal (QAR)
- Status
- Illustrative example
- Challenge
- A British couple working as teachers in Doha, Qatar, had never owned property anywhere and wanted a UK base ahead of an eventual return. As first-time buyers resident overseas they faced three hurdles at once: many expat lenders prefer applicants who already own property, their Qatari riyal (QAR) salaries needed converting to sterling with a currency adjustment, and their deposit — saved from tax-free earnings in Qatar — required a fully evidenced paper trail.
- Solution
- In this illustrative scenario, Clifton International would facilitate an introduction to a specialist expat mortgage team. The team would identify lenders whose criteria accept first-time buyers resident in Qatar, present the couple's QAR income in the required format, evidence the deposit through bank statements and coordinate the application across the time difference. Stamp Duty would be planned around first-time buyer relief (never having owned a home anywhere in the world) plus the 2% non-resident surcharge.
- Funding structure
- An illustrative £217,500 expat residential mortgage at 75% LTV against a £290,000 Birmingham semi-detached home, funded by a £72,500 evidenced deposit, with QAR income converted to sterling and assessed after a currency adjustment.
- Outcome
- This is a worked example, not a completed transaction: it shows how the deposit, income-currency and Stamp Duty pieces fit together for an expat first purchase. Real applications depend on the lender's country list, currency policy, affordability assessment and the buyers' circumstances at the time.
Case evidence, sources and limitations
Source: an illustrative worked example created by Clifton International to show how deposit, foreign income and Stamp Duty interact for an expat first-time buyer. The figures are plausible market values, not a reported transaction.
This is not a completed case and not a promise of terms. The lender, interest rate, product fees and completion timeline are not specified because no transaction took place. The property image is an illustration, not a real clients' property. Clifton International is an introducer, not a lender or mortgage adviser.
Case narrative updated . This is an editorial date, not the completion date.
- HMRC: Stamp Duty relief for first-time buyers
Official rules for first-time buyer relief, including the requirement never to have owned a home anywhere in the world.
- GOV.UK: Stamp Duty rates for non-UK residents
Official residential SDLT rates and the 2% non-resident surcharge that would apply on top of any relief.
More UK case studies
Related transactions
£250K released from a Surrey buy-to-let for Singapore-based expats
£250k capital release · Singapore-based couple · SGD income
£862K mortgage for a British doctor in Canada buying in Ealing
£862k mortgage · £1.15m Ealing new-build · CAD income
£1.3M bridging loan to support a significant upsize in Leeds
£1.3m · 65% LTV · 12-month regulated bridge
FAQs
Questions on this case
- Can a British expat in Qatar get a UK mortgage as a first-time buyer?
- Yes, but the lender panel is narrower than for UK residents or existing homeowners. Lenders that accept first-time buyers resident in Qatar will assess QAR income converted to sterling, require an evidenced deposit and apply their own country and currency criteria.
- How much deposit does an expat first-time buyer need?
- Plan for at least 20–25%. In this illustrative example the buyers put down £72,500 (25%) on a £290,000 Birmingham home. The deposit must be fully evidenced through bank statements, wherever in the world it was saved.
- Do expat first-time buyers pay Stamp Duty?
- First-time buyer relief can still apply if every buyer has never owned a home anywhere in the world and the price is within the relief limits. Non-UK residents pay the 2% non-resident surcharge on top of the relieved rates.
- Is this case study a real completed purchase?
- No. It is an illustrative worked example showing how the numbers fit together for an expat first purchase. Real outcomes depend on the lender's criteria, the buyers' circumstances and the property at the time of application.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
UK expat finance
Explore more UK expat mortgage guidance
Expat guides and tools
- UK expat mortgages hub
- UK expat finance guide
- UK expat finance FAQs
- Which UK banks lend to expats
- Expat first-time buyer mortgages
- UK expat remortgage guide
- Limited company buy-to-let for expats
- Stamp Duty surcharge for non-residents
- Bridging loans for expats and non-residents
- UK mortgages on Australian dollar income
- Australian nationals buying in the UK
Expat case studies
UK mortgages by country of residence
- Expats in UAE
- Expats in Saudi Arabia
- Expats in Qatar
- Expats in Kuwait
- Expats in Bahrain
- Expats in Oman
- Expats in Hong Kong
- Expats in Singapore
- Expats in China
- Expats in Japan
- Expats in Australia
- Expats in New Zealand
- Expats in Canada
- Expats in USA
- Expats in Spain
- Expats in France
- Expats in Ireland
- Expats in Germany
- Expats in Netherlands
- Expats in Switzerland
- Expats in South Africa
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.