Zurich old town and lake with the Alps behind

Expat Mortgages

UK mortgages for expats in Switzerland.

Purchase, buy-to-let and remortgage finance for British expatriates and residents buying UK property from Switzerland — with Swiss franc income and local banking history considered.

Get Your Finance Assessment

Two quick steps — a specialist will respond within one working day.

  • 40+ lendersWhole-of-market panel
  • 4–8 weeksTypical completion
  • Rated ExcellentClient reviews
  • No obligationFree initial review
£

An exact value lets us calculate your LTV straight away.

£

An exact figure lets us calculate LTV and indicative terms straight away.

Your figures

You're enquiring about finance for property in Switzerland.
Confidential — no obligation Rated 4.9 on Trustpilot

Last updated Reviewed by our Clifton International finance team.

In short

Can expats in Switzerland get a UK mortgage?

Yes. Switzerland-based buyers can arrange UK mortgages through lenders that accept overseas applicants and CHF income. As an indicative guide, deposits are often 25–40% and lenders may adjust converted income for currency risk. A well-prepared case typically completes in six to ten weeks.

  • CHF is a widely accepted currency, and higher Swiss salaries can support larger loans.
  • Residential, buy-to-let and remortgage purposes are available.
  • UK limited-company buy-to-let structures are widely accepted.
  • A UK credit history is helpful but not always required.

At a glance

Key facts

Figures reviewed:

Indicative deposit
25% – 40%
Accepted income
CHF, GBP, USD
Purposes
Purchase, BTL, remortgage
Indicative timescale
6 – 10 weeks
Indicative pricing
From 0.65% per month (bridging) / from 4.5% p.a. (term)Priced to profile, LTV, asset and lender. Live pricing confirmed on enquiry.
Typical set-up costs
1.5% – 2.5% of loan (arrangement, valuation, legals)Excludes stamp duty; non-resident surcharges may apply.
Adviser response time
Within one working day

Indicative figures for guidance only, correct as at October 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.

Methodology and assumptions

  • Figures are compiled by Clifton International specialists from live lender term sheets, indicative quotes and completed transactions arranged over the preceding 12 months.
  • Rates and costs are stated as ranges rather than a single number because pricing is set case-by-case on borrower profile, residency, asset type, location and loan-to-value.
  • Timelines assume a complete document file from the outset; valuation, legal capacity and (in Spain) NIE and notary availability drive the critical path.
  • Costs exclude any lender, broker or third-party fees not stated on the page, and exclude currency movement between agreement and drawdown.
  • Figures are reviewed monthly and re-checked against lender pricing whenever a material market change occurs.

Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.

Key figures

UK expat mortgage rates this month

Rates checked October 2026 across 6 UK lenders that accept expat applicants. Based on a £300,000 loan, capital and interest.

Residential 2-year fixed, 75% LTV
from 5.64%*
typical 5.66%
Residential 5-year fixed, 75% LTV
from 5.63%*
typical 5.75%
Buy-to-let 2-year fixed, 75% LTV
from 5.69%*
typical 5.72%
Buy-to-let 5-year fixed, 75% LTV
from 5.54%*
typical 5.74%

Expat rate questions

What are UK expat mortgage rates this month?

As at October 2026, 2-year fixed residential expat rates on our panel start from 5.54% at 60% LTV and 5.64% at 80% LTV, based on a £300,000 loan, capital and interest. Product fees may apply.

What is a typical expat buy-to-let rate?

For a 5-year fixed expat buy-to-let at 75% LTV, rates start from 5.54% with a typical rate of 5.74% across 5 lenders (October 2026).

Can expats get an interest-only mortgage?

Yes. Interest-only residential 2-year fixes at 75% LTV start from 5.85% as at October 2026. You will need a credible plan to repay the balance at the end of the term.

*Product fees may apply. Indicative initial rates only; after the fixed term the rate reverts to the lender's variable rate. Source: published lender rate sheets for intermediaries, approved by Clifton International (October 2026). Not an offer of finance; your home may be repossessed if you do not keep up repayments on your mortgage.

Why clients choose us

Benefits at a glance

CHF income considered

Lenders that accept Swiss franc income, with any currency adjustment explained before you apply.

No UK credit file needed

Routes that consider banking history and verified income in Switzerland rather than only a UK credit record.

Buy-to-let from Switzerland

Personal-name and UK limited-company options for overseas landlords.

Documents made clearer

Guidance on Swiss tax assessments or Lohnausweis salary certificates, residency evidence, source of funds and certification.

Borrower eligibility

Who we can help

  • British expatriates living and working in Switzerland
  • Residents of Switzerland buying UK property
  • Switzerland-based landlords buying or remortgaging UK buy-to-let
  • Buyers purchasing through a UK limited company

Typical lending criteria

Indicative parameters

Indicative deposit
25% – 40%
Accepted income
CHF, GBP, USD
Purposes
Purchase, BTL, remortgage
Indicative timescale
6 – 10 weeks

Indicative only. Actual terms depend on borrower profile, asset and lender criteria.

Applying from Switzerland

Swiss residence status and CHF income

Swiss migration guidance distinguishes British citizens protected by acquired-rights arrangements from those arriving after the transition period. The right residence evidence therefore depends on your circumstances; do not assume every British applicant holds the same permit. For a UK mortgage, describe your actual Swiss status alongside your CHF employment income and outstanding commitments. A high nominal salary does not remove the need for a lender's sterling affordability assessment. Keep pension balances separate from cash available for a deposit: this page does not assume that Swiss pension assets can be withdrawn to buy UK property.

Swiss ZEK entries need their own explanation

ZEK's borrower guidance allows individuals to request information about entries held in their name. Its credit-information records should be read alongside current Swiss bank and leasing statements, rather than translated into an assumed UK credit score. Check names and the status of any borrowing before supplying a report requested by the UK lender, and query inaccuracies through the local process. For a Zurich applicant, explaining Swiss financial commitments remains important even with a substantial salary. A report or database extract alone does not establish affordability or lender acceptance.

CHF pay, deductions and a sterling mortgage

The Swiss National Bank publishes exchange-rate data, but that reference is separate from a lender's assessment of CHF income. Show the salary credited after deductions and identify variable pay separately so the UK application does not rely only on a high gross figure. Ask how the lender converts CHF into GBP and whether it applies a currency haircut. For a planned family return from Switzerland, explain whether the income will continue or change. Keep pension balances separate from transferable deposit cash; no withdrawal eligibility is assumed here.

Illustrative mini case — not a completed client transaction

Zurich-based specialist buying in Cambridge

A British specialist paid in CHF intends to buy a UK property for a planned family return, using cash savings rather than pension assets.

Assumed purchase price
£650,000
Assumed cash deposit
£260,000
Proposed mortgage
£390,000
Illustrative LTV
60%

The file would show the actual Swiss permit, employer income evidence and the savings trail. The adviser would confirm how CHF income is converted and adjusted and whether the proposed future occupancy fits a residential product.

Hypothetical amounts, not a quote or a statement of lender policy. Purchase taxes, legal costs, product fees and currency-transfer costs are excluded. Eligibility, affordability and source of funds require individual checks. Current indicative rates appear in the approved rates panel above.

Discuss a UK purchase from Switzerland
Who this page is for

  • UK expats living in Switzerland — British nationals earning in CHF who want to buy, remortgage or let UK property.
  • Residents of Switzerland — buying a UK home or investment property from Switzerland.
Read the Switzerland documents checklist

Common questions covered in our UK expat finance FAQs — currency conversion, deposit rules and residency.

Already living in the UK? See our UK mortgages page.

Start an enquiry

Opens our enquiry form already filled in for a Switzerland-based applicant — just add your details.

Enquire about a UK mortgage from Switzerland

Clifton International introduces you to lenders and brokers; it is not a lender and does not handle client funds.

Buying from overseas

Use bridging finance to secure the property, then exit onto an expat mortgage.

If a UK property cannot wait for a standard expat mortgage timescale, bridging finance may let an overseas buyer complete without making the purchase conditional on that mortgage. It can put you in a cash-buyer position for the transaction, although the purchase is still being funded by a secured loan.

1

Secure the property

A short-term bridge can fund the UK purchase before the longer expat mortgage process has completed, allowing you to proceed in a cash-buyer position.

2

Complete the expat mortgage

The longer-term application continues with the lender assessing overseas residency, foreign-currency income, documents and the property.

3

Repay the bridge

Once the expat mortgage completes, its proceeds repay the bridging loan and move the borrowing onto the intended longer-term arrangement.

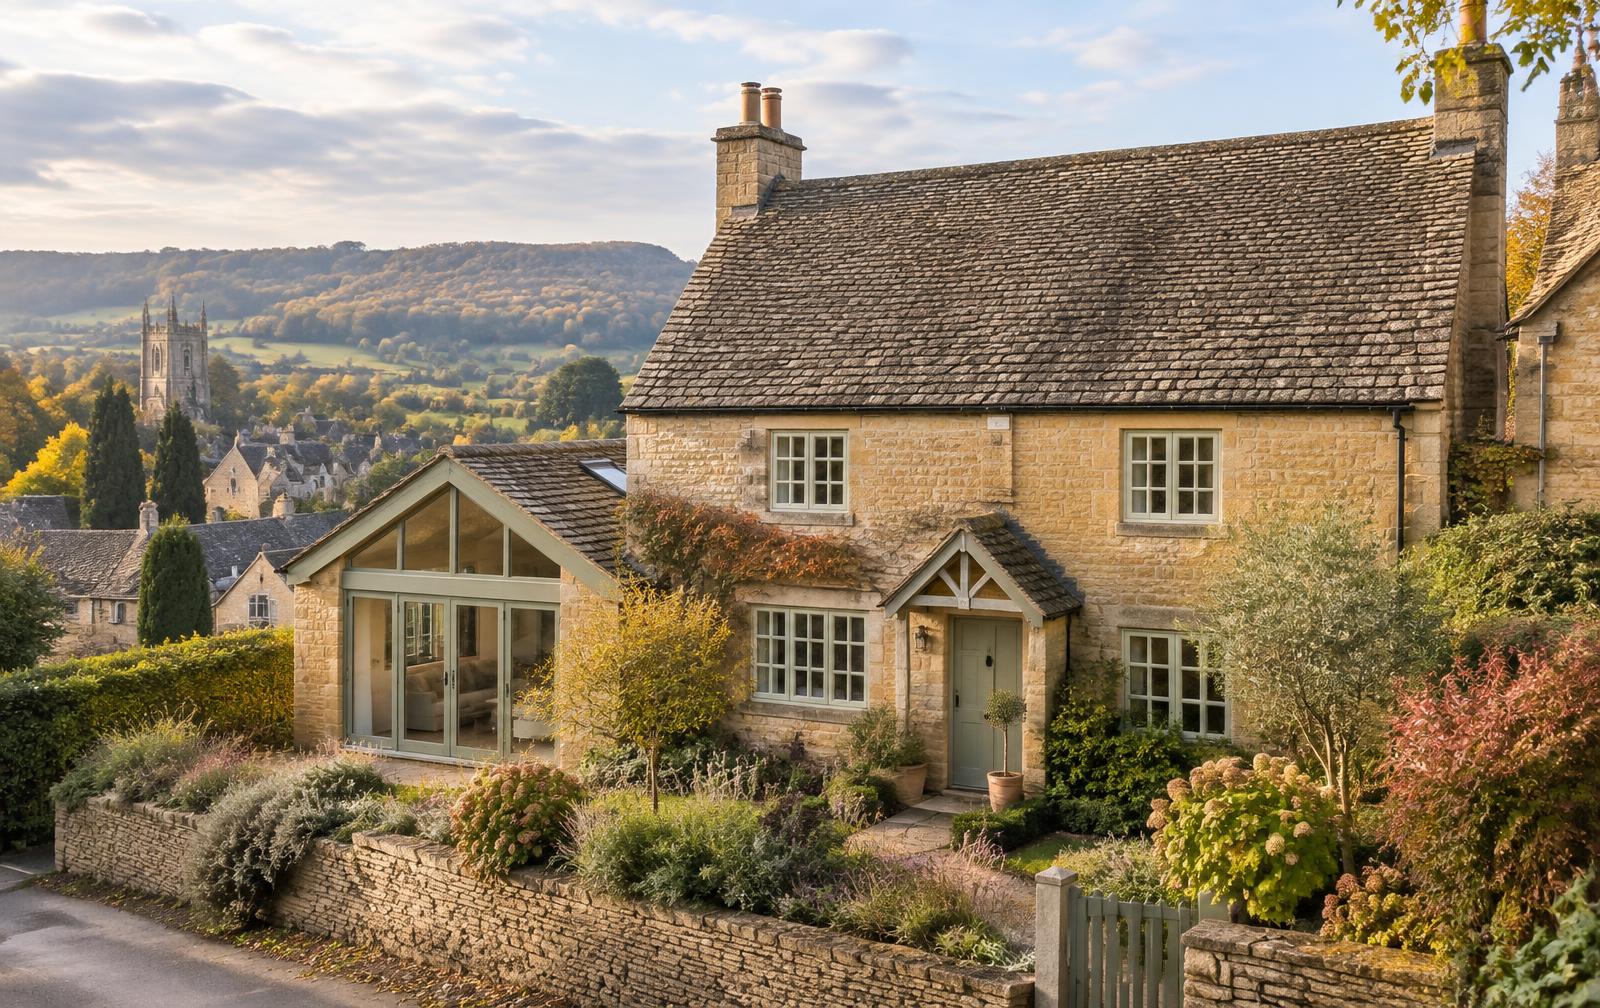
Cotswold stone cottage with a glass extension in Painswick, the property in the case studyCase study

A real example

£500k Cotswolds bridge for a couple based overseas

A UK national and an Australian national working in Hong Kong used a regulated bridge at around 50% LTV to secure a Painswick cottage before their existing home was sold.

Read the case study

The expat mortgage must be assessed as a credible exit before entering the bridge. Bridging finance is short term and normally more expensive than a mortgage; approval, timing and the eventual mortgage terms are not guaranteed. Clifton International is an introducer, not a lender or adviser, and does not handle client funds.

Frequently asked

Questions from clients

Can people living in Switzerland get a UK mortgage?

Yes. British expats and residents of Switzerland can arrange UK residential and buy-to-let mortgages through a wide range of UK lenders and private banks that accept overseas applicants. Approval depends on income, deposit, residency and the property.

Is Swiss franc (CHF) income accepted by UK lenders?

CHF is a widely accepted currency, and higher Swiss salaries can support larger loans. For affordability, lenders convert the income into pounds and may apply a currency adjustment for exchange-rate movement.

What deposit do Switzerland-based buyers need?

As an indicative working assumption, overseas applicants often need a 25–40% deposit. The exact amount depends on residency, income, property use and lender criteria.

Do I need a UK credit history?

Not necessarily. Lenders experienced with overseas applicants can assess verified income, assets and banking history in Switzerland instead of a UK credit file.

Will the UK non-resident stamp duty surcharge apply?

It can apply in England and Northern Ireland if the residence test is not met, and higher additional-property rates may also apply. Your UK solicitor should confirm the position before exchange.

What documents will I need?

Usually a passport, Swiss residence permit (B or C), proof of address, payslips and an employment contract, Swiss tax assessments or Lohnausweis salary certificates, bank statements, source-of-funds evidence and certified copies of ID.

How long does a UK mortgage from Switzerland take?

A well-prepared overseas application often takes around six to ten weeks, depending on valuation, document certification and international identity checks.

Is Swiss franc income accepted?

Yes. CHF is one of the more widely accepted foreign currencies. Lenders convert it to pounds and may apply a currency adjustment for affordability.

Currency exchange

Earning overseas? Your deposit is exposed until it’s in sterling.

Expat buyers moving dollars, dirhams, riyals or euros into the UK can lose thousands to bank margins and rate moves. We introduce you to an FCA-authorised currency specialist who plans your transfer around exchange and completion.

  • Forward contracts to fix your sterling deposit before completion
  • Better-than-bank rates on large one-off and regular transfers
  • Flexible contact across time zones with a dedicated specialist

Clifton introduces clients to a specialist currency partner and does not hold, convert or transfer client funds.

Ready to explore your options?

Speak to a UK property finance specialist.

A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.