£490,000 mortgage for a day-rate IT contractor paid in euros
£490,000 mortgage · £611,000 Leeds home · offer within two weeks
In short
Can a day-rate IT contractor paid in euros get a UK mortgage?
A limited-company IT contractor paid in euros secured a £490,000 mortgage offer for a £611,000 detached family home in Leeds after previous declines. Specialist underwriting considered the underlying day-rate contract income rather than salary and dividends alone. The offer arrived within two weeks; this was not the purchase completion timescale.
- Mortgage offer: £490,000 towards a £611,000 detached family home in Leeds.
- Income: euro-denominated day-rate IT contracting through a limited company.
- Assessment: underlying contract income considered, rather than salary and dividends alone.
- Offer within two weeks; purchase completion date, lender, rate and term not disclosed.
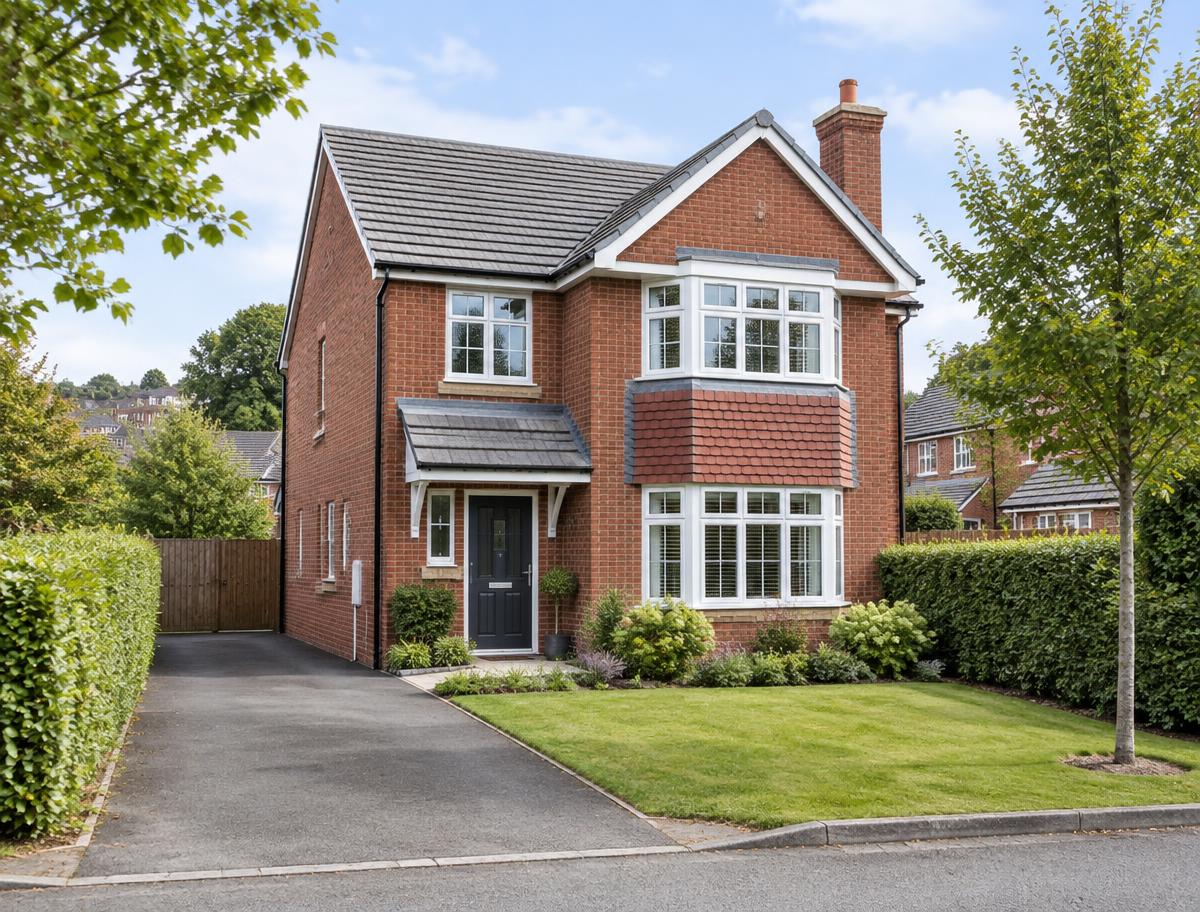
Illustrative property image — not the clients’ actual property.
- Mortgage offer
- £490,000
- Purchase price
- £611,000
- Offer secured
- Within two weeks
- Income currency
- Euros (EUR)
- Income structure
- Day-rate IT contractor
- Location
- Leeds
- Challenge
- An experienced IT contractor paid in euros through his limited company wanted to purchase a detached family home in Leeds for £611,000, requiring a £490,000 mortgage. Previous applications had been unsuccessful because the assessment focused on salary and dividends withdrawn from the company rather than the underlying day-rate contract income. The client also wanted flexibility around future bonus payments and changing contractor cash flow. His country of residence and nationality are not stated in the supplied account.
- Solution
- Clifton International facilitates introductions to specialist property finance teams, rather than acting as lender or mortgage adviser. In the supplied account, the specialist team reviewed the client's contracts, company structure, income and borrowing needs, then identified lenders experienced with euro earnings and day-rate contractors operating through limited companies. The application evidenced the strength and consistency of contract income so the lender could consider contractor-based affordability rather than salary and dividends alone.
- Funding structure
- A £490,000 residential mortgage offer towards the £611,000 purchase of a detached family home in Leeds, supported by euro-denominated day-rate contractor income. The account reports flexibility for future bonus income and cash-flow changes but does not specify the repayment basis, term, interest rate, fees or overpayment conditions. The purchase was for a family home; operating through a limited company describes the client's income structure, not confirmed company ownership of the property.
- Outcome
- A mortgage offer was secured within two weeks following previous unsuccessful attempts elsewhere, allowing the client to proceed with the Leeds home purchase at the required borrowing level. Two weeks refers to the mortgage offer, not completed purchase or funds drawn. The supplied account does not give a completion date. This is a reported case-specific outcome, not a guarantee of approval, borrowing capacity or timing for other applicants.
Case evidence, sources and limitations
Source: the anonymised case-study account supplied by James Caldwell, headed ‘£490,000 Mortgage Secured for a Day-Rate IT Contractor Paid in Euros’, adapted from ‘Mortgage Secured for Day Rate Contractor Paid in Euros’. Figures and outcomes are reported case facts, not independently audited market data. Clifton International presents the account as an introducer, not as lender or mortgage adviser.
The client's residence, nationality, day rate, contract duration, lender identity, lender valuation, currency adjustment, interest rate, fees, mortgage term and repayment basis are not supplied. No specific overpayment allowance is confirmed. The two-week milestone is a mortgage offer, not completion or funds drawn. The photo is illustrative, not the client's actual home. Lender criteria and affordability vary. Your home may be repossessed if you do not keep up repayments on your mortgage.
Case narrative updated . This is an editorial date, not the completion date.
More UK case studies
Related transactions
£809K mortgage for unique countryside property to exit bridging loan
£809k · 60% LTV · 25-year term
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
FAQs
Questions on this case
- Can euro-paid contractors be assessed on their day rate?
- Some lenders can consider underlying day-rate contract income rather than only salary and dividends. In this reported Leeds case, that approach supported a £490,000 mortgage offer. Currency acceptance, contract history and affordability still require individual assessment.
- Did the Leeds purchase complete in two weeks?
- No completion timescale is reported. The supplied account says the mortgage offer was secured within two weeks, allowing the client to proceed. An offer is a different milestone from legal completion and funds drawn.
- Was the Leeds home purchased through a limited company?
- The source describes the client as a limited-company director, explaining how his contracting income was received. It does not confirm company ownership of the family home, so that should not be inferred.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.