£862K mortgage for a British doctor in Canada buying in Ealing
£862k mortgage · £1.15m Ealing new-build · CAD income
In short
How was £862K mortgage for a British doctor in Canada buying in Ealing financed?
Clifton International arranged expat residential mortgage for this West London transaction — £862k mortgage, £1.15m Ealing new-build, CAD income. A £862,000 expat residential mortgage secured against the £1.15m Ealing new-build, underwritten for UK nationals permanently resident in Canada with multiple professional income streams.
- Location: West London. Finance type: Expat residential mortgage.
- Headline terms: £862k mortgage · £1.15m Ealing new-build · CAD income.
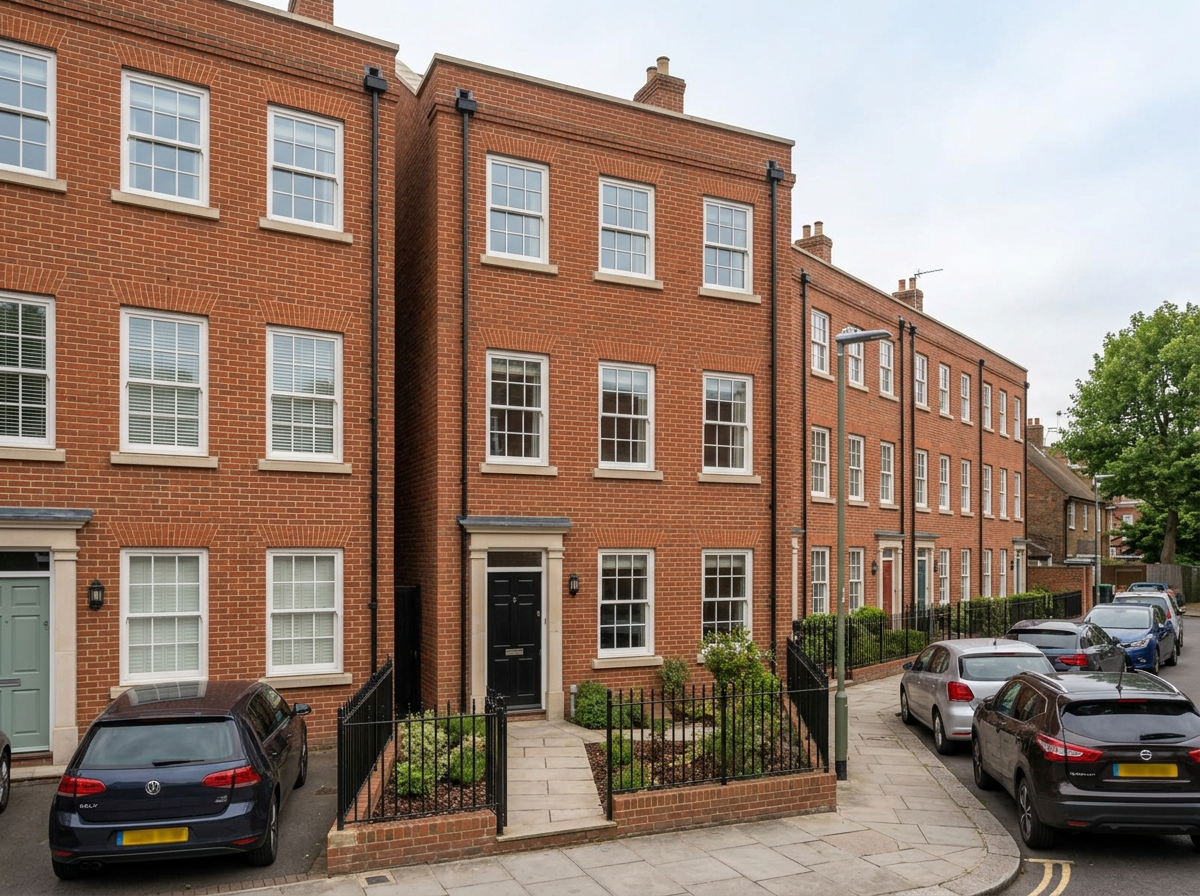
- A British couple living and working in Toronto wanted to buy a permanent UK base for family visits to the wife's parents. After paying a 5% reservation deposit on a £1.15m Georgian-style new-build in Ealing, their high street bank declined the application because its policy did not support applicants permanently resident overseas. With the developer seeking reassurance and valuation and legal costs already sunk, the purchase was at risk. The case combined overseas residence, multiple income streams from the husband's hospital, private practice and board work, and a high-value new-build purchase.
- The mortgage was approved and the purchase completed within the developer's required timeframe, funding £862,000 of the £1.15m purchase. The couple secured a permanent London base for family visits and future flexibility while continuing their careers overseas.
- Property value
- £1,150,000
- Mortgage secured
- £862,000
- Location
- Ealing, West London
- Clients
- British expats in Toronto
- Income currency
- Canadian dollars
- Purpose
- UK residential purchase
- Challenge
- A British couple living and working in Toronto wanted to buy a permanent UK base for family visits to the wife's parents. After paying a 5% reservation deposit on a £1.15m Georgian-style new-build in Ealing, their high street bank declined the application because its policy did not support applicants permanently resident overseas. With the developer seeking reassurance and valuation and legal costs already sunk, the purchase was at risk. The case combined overseas residence, multiple income streams from the husband's hospital, private practice and board work, and a high-value new-build purchase.
- Solution
- Clifton International reviewed the couple's finances, assets and objectives, then facilitated an introduction to a specialist expat mortgage team. Several lenders were considered — one requiring audited accounts at significant cost and delay, another restricting borrowing to a lower LTV — before a lender experienced with high-net-worth expatriate borrowers and overseas medical professionals was identified. When a historical tax question on the husband's private practice arose before final commitment, the transaction was coordinated between solicitors, the lender and the developer's sales team so every point was documented before exchange, without ceding to time pressure.
- Funding structure
- A £862,000 expat residential mortgage secured against the £1.15m Ealing new-build, underwritten for UK nationals permanently resident in Canada with multiple professional income streams.
- Outcome
- The mortgage was approved and the purchase completed within the developer's required timeframe, funding £862,000 of the £1.15m purchase. The couple secured a permanent London base for family visits and future flexibility while continuing their careers overseas.
More UK case studies
Related transactions
£250K released from a Surrey buy-to-let for Singapore-based expats
£250k capital release · Singapore-based couple · SGD income
£1.3M bridging loan to support a significant upsize in Leeds
£1.3m · 65% LTV · 12-month regulated bridge
£230k bridging loan secured against UK property to buy a Malaga apartment
£230k · c.25% LTV · 36 days to completion
FAQs
Questions on this case
- Can a British expat living in Canada get a UK residential mortgage?
- Yes. Specialist lenders and private banks can consider UK nationals permanently resident in Canada for UK residential mortgages, subject to income, deposit, the property and lender policy. Mainstream high street banks often decline overseas applicants outright, as happened in this case before the clients came to us.
- Can complex professional income be used for an expat mortgage?
- It can. Lenders experienced with overseas professionals can assess multiple income streams — such as hospital employment, private practice and governance or board remuneration — alongside overseas residence, although underwriting approaches differ between lenders.
- Can an expat mortgage be arranged on a new-build property?
- Yes, but not every lender handles new-builds, particularly at higher values. In this case the specialist lender was comfortable with a high-value new-build purchase in West London for applicants living in Canada.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.