€3M bridging loan on Ibiza residential property to fund a London development project
€3m · 60% LTV · 12-month term
Swift turnaround on complex overseas security
In short
How was €3M bridging loan on Ibiza residential property to fund a London development project financed?
Clifton International arranged overseas bridging loan for this Ibiza / London transaction — €3m, 60% LTV, 12-month term. We identified two private lenders comfortable with overseas security, gained a detailed overview of the clients' financial situation, and obtained initial terms quickly. We liaised with the clients' solicitor and the preferred lender to structure a 12-month facility.
- Location: Ibiza / London. Finance type: Overseas bridging loan.
- Time to funding: Swift turnaround on complex overseas security.
- The clients needed €3m quickly to finish development works on a London property. They already had outstanding mortgages on the London asset, so raising further funds against it was not possible. Their residential property in Ibiza was identified as an alternative source of security, but the lending pool for overseas-secured bridging is minimal.
- The clients completed the London development works and had 12 months to sell the Ibiza property at the right price. The deal demonstrated how specialist knowledge of private lenders can unlock finance when mainstream routes are closed.
- Loan amount
- €3,000,000
- LTV
- 60%
- Term
- 12 months
- Security
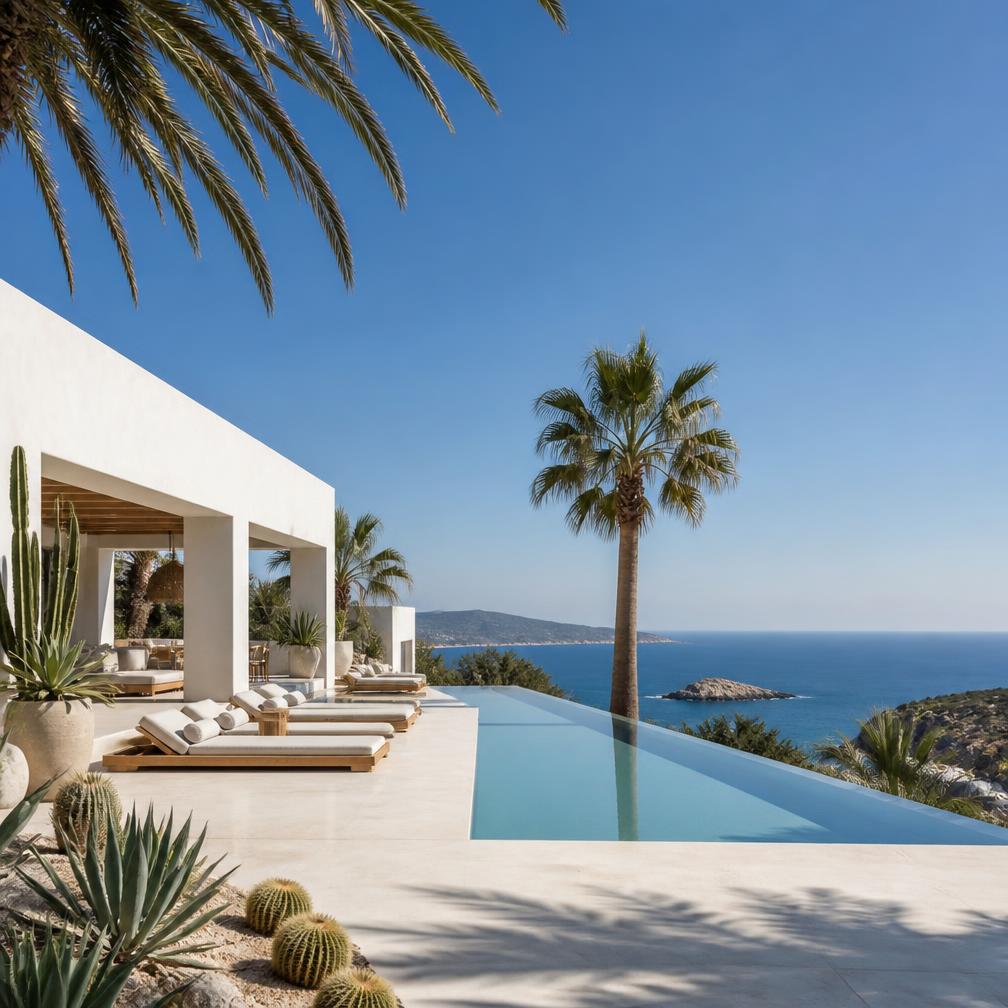
- Residential property in Ibiza
- Use of funds
- London development project
- Exit
- Sale of Ibiza property
- Challenge
- The clients needed €3m quickly to finish development works on a London property. They already had outstanding mortgages on the London asset, so raising further funds against it was not possible. Their residential property in Ibiza was identified as an alternative source of security, but the lending pool for overseas-secured bridging is minimal.
- Solution
- We identified two private lenders comfortable with overseas security, gained a detailed overview of the clients' financial situation, and obtained initial terms quickly. We liaised with the clients' solicitor and the preferred lender to structure a 12-month facility.
- Funding structure
- €3m bridging loan secured against a residential property in Ibiza, 60% LTV, 12-month term, with repayment from the sale of the Spanish property. Ownership was moved into a limited company before completion to make interest repayments more tax-efficient.
- Outcome
- The clients completed the London development works and had 12 months to sell the Ibiza property at the right price. The deal demonstrated how specialist knowledge of private lenders can unlock finance when mainstream routes are closed.
More UK case studies
Related transactions
£1.3M bridging loan to support a significant upsize in Leeds
£1.3m · 65% LTV · 12-month regulated bridge
£230k bridging loan secured against UK property to buy a Malaga apartment
£230k · c.25% LTV · 36 days to completion
£1.2M bridging loan secured to complete dream home purchase in Oxfordshire
£1.2m · 60% LTV · chain-break bridge
FAQs
Questions on this case
- Can I use an overseas property as security for a UK bridging loan?
- Yes, but the lender pool is very small. In this case, a €3m bridging loan was secured against a residential property in Ibiza to fund development works on a London property, arranged through a specialist private lender.
- Can a bridging loan be used for property development?
- Yes. Bridging finance is commonly used to fund development works, either as a development bridge or — as in this case — to raise capital against an existing asset when further advances on the development property are not available.
- Is it better to hold overseas security in a limited company for a bridging loan?
- Holding the security property in a limited company can make interest repayments more tax-efficient depending on the borrower's personal income structure. Tax advice should always be sought before making this decision.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.