£500,000 mortgage for a returning expat buying in Bristol
£500k mortgage · Clifton flat · AUD income via trust structure · approved within weeks
In short
Can a returning UK expat with Australian income get a UK mortgage?
Yes. Clifton PF International arranged a £500,000 residential mortgage on a flat in Clifton, Bristol for a British national returning to the UK after more than ten years in Australia. The applicant earned Australian dollars through a trust-owned business, had only recently begun rebuilding his UK credit profile, and had a one-month break in salary records during the application. A lender willing to assess the case on its individual merits approved the mortgage within weeks.
- Location: Clifton, Bristol. Finance type: Expat residential mortgage for a returning UK expat.
- Headline terms: £500k mortgage · Clifton flat · AUD income via trust structure · approved within weeks.
- The client had spent over ten years living in Australia before returning to the UK with his partner to help care for his elderly mother. After renting in London while settling back, the couple wanted a permanent family home in Bristol and identified a desirable flat in Clifton, requiring a mortgage of approximately £500,000 — a high loan-to-value borrowing requirement. The application combined ten years of overseas residence, income earned in Australia as Chief Executive Officer of a health retreat business through a trust-owned employment structure, and a UK financial footprint only recently being re-established, including electoral roll registration and UK credit accounts. During the process, following the death of his mother, the client also missed one month's salary drawing from the business — explainable, but the kind of income break many lenders would flag.
- The mortgage was approved within a matter of weeks, allowing the clients to complete the purchase of their Clifton home and establish their long-term family base following their return to the UK. Every case is assessed individually; this outcome does not guarantee terms for another applicant.
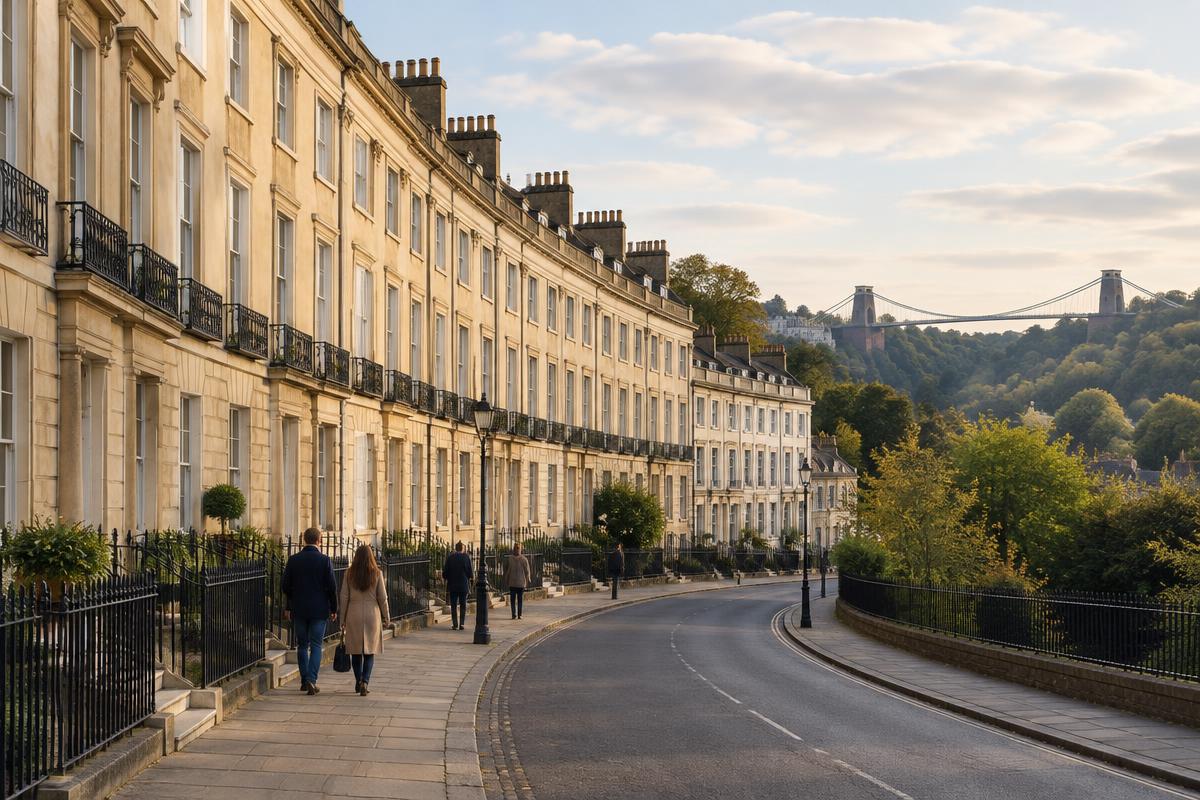
Illustrative property image — not the clients’ actual property.
- Mortgage secured
- £500,000
- Location
- Clifton, Bristol
- Borrower
- Returning UK expat after 10+ years in Australia
- Income currency
- Australian dollars (AUD)
- Employment
- CEO of an Australian health retreat business (trust-owned)
- Approval
- Approved within a matter of weeks
- Challenge
- The client had spent over ten years living in Australia before returning to the UK with his partner to help care for his elderly mother. After renting in London while settling back, the couple wanted a permanent family home in Bristol and identified a desirable flat in Clifton, requiring a mortgage of approximately £500,000 — a high loan-to-value borrowing requirement. The application combined ten years of overseas residence, income earned in Australia as Chief Executive Officer of a health retreat business through a trust-owned employment structure, and a UK financial footprint only recently being re-established, including electoral roll registration and UK credit accounts. During the process, following the death of his mother, the client also missed one month's salary drawing from the business — explainable, but the kind of income break many lenders would flag.
- Solution
- The application was presented within the wider context of the client's circumstances to lenders with experience of returning expatriates and overseas income structures: a long-standing senior executive position, an established income history, strong career credentials, genuine family circumstances behind the temporary interruption to income, and a clear commitment to re-establishing permanent UK residence. A lender was identified willing to take a pragmatic view of the income evidence and to understand the circumstances behind the missing payment, recognising it did not reflect any ongoing affordability concern.
- Funding structure
- A £500,000 residential mortgage secured on a flat in Clifton, Bristol, with income evidenced in Australian dollars earned through a trust-owned business structure. The lender, loan-to-value and rate are not published.
- Outcome
- The mortgage was approved within a matter of weeks, allowing the clients to complete the purchase of their Clifton home and establish their long-term family base following their return to the UK. Every case is assessed individually; this outcome does not guarantee terms for another applicant.
Case evidence, sources and limitations
Source: Clifton PF International’s own client case, first published on this site on 30 October 2026 from the adviser’s account of the transaction. No separate external account is cited.
Client details are anonymised. The lender, loan-to-value and rate are not published, and the photograph is an illustrative view of Clifton, Bristol rather than the clients’ actual property.
Case narrative updated . This is an editorial date, not the completion date.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£380,000 buy-to-let remortgage for UK expats in the US paid in dollars
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
FAQs
Questions on this case
- Can a returning UK expat with overseas income get a UK mortgage?
- Yes. Lenders experienced with returning expatriates can consider applicants recently back in the UK with overseas income, including non-standard employment structures such as trust-owned businesses. Lender selection matters: one relying on automated criteria may decline what a specialist lender can underwrite on its individual merits.
- Does a break in salary records stop a mortgage application?
- Not necessarily. In this case the applicant missed one month's salary drawing from his business following a family bereavement. The lender was willing to understand the circumstances behind the temporary interruption and did not treat it as an ongoing affordability concern.
- Do I need a full UK credit history after moving back from Australia?
- You do not need to have rebuilt it fully before applying. Returning expats commonly need time to re-register on the electoral roll and reopen UK credit accounts; some lenders will still lend on documented overseas income while that footprint is re-established.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.