£410,000 buy-to-let remortgage for a UK expat in Japan earning in Japanese yen
Reported £410k raised · mortgage-free London BTL valued ~£1.3m · ~£2,500/month rent · JPY income
In short
Can a UK expat in Japan paid in yen remortgage a UK buy-to-let?
Yes, though lender choice is narrower. Clifton Private Finance reports £410,000 raised through a buy-to-let remortgage on a mortgage-free London rental worth about £1.3 million, for a British national in Japan paid entirely in yen, to fund a second UK purchase. This is an attributed external case, not a Clifton International deal.
- Borrower: British national living in Japan, employed by a multinational, paid in Japanese yen.
- Security: mortgage-free London buy-to-let valued at about £1.3 million, let for around £2,500 a month.
- Reported remortgage: £410,000 released, about 32% loan-to-value (derived).
- Purpose: deposit for a second UK investment property facing competing buyers.
- Source: attributed Clifton Private Finance account; lender, rate and fees not published.
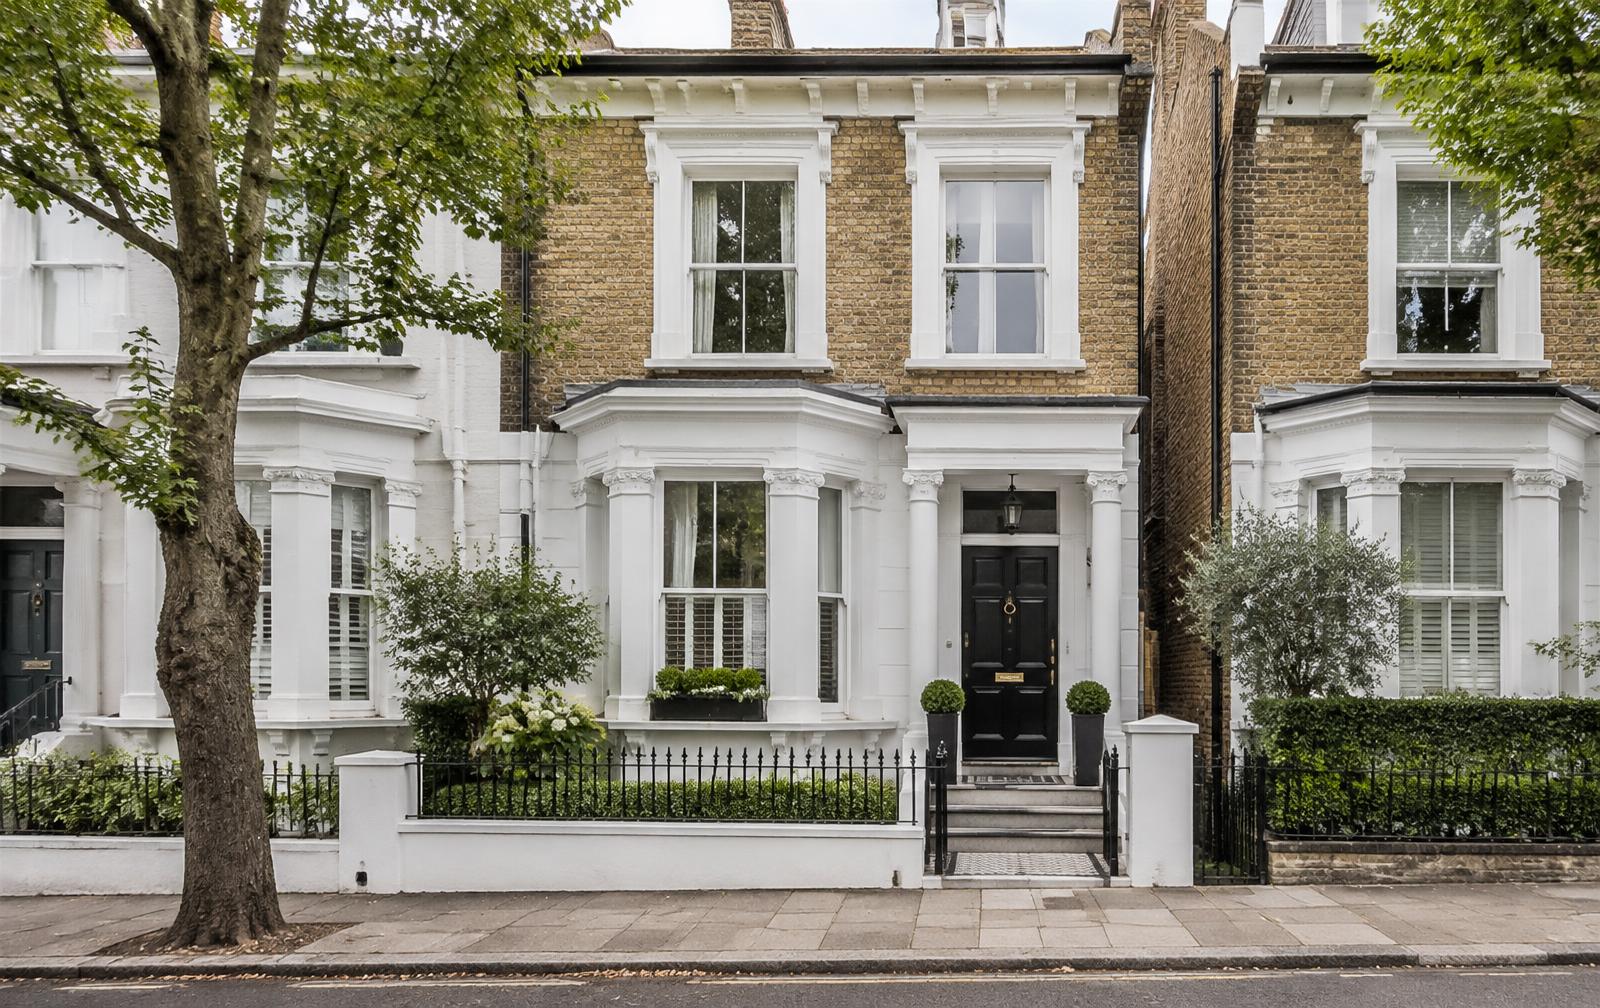
Illustrative property image — not the clients’ actual property.
- Reported capital raised
- £410,000
- Property value reported
- About £1.3 million (mortgage-free)
- Loan-to-value
- About 32% (derived)
- Rental income reported
- About £2,500 per month
- Income currency
- Japanese yen (JPY)
- Purpose
- Deposit for a second UK investment property
- Challenge
- According to Clifton Private Finance’s account, a British national living and working in Japan for a multinational company owned a London rental property outright, valued at about £1.3 million and let for around £2,500 a month. He needed £410,000 to fund the deposit on a second UK investment property that was already attracting other buyers, so speed mattered. He lived overseas and was paid entirely in Japanese yen (JPY), which narrows lender choice: many lenders prefer sterling income and are cautious about currency movements, verifying overseas employment and assessing foreign-currency affordability.
- Solution
- Clifton Private Finance, the arranging team named in the original account, identified a lender comfortable with UK nationals living overseas, income paid in yen, capital raising against a UK buy-to-let and an investment strategy involving more than one UK property. The substantial equity and established rent on the London property supported the application. Clifton International publishes an attributed summary of that external account; this is not a Clifton International transaction.
- Funding structure
- The source reports a £410,000 buy-to-let remortgage secured on a mortgage-free London property valued at about £1.3 million — roughly 32% loan-to-value, derived from the reported figures — with rental income of around £2,500 a month and the borrower’s JPY income. The lender, rate, fees, term and repayment basis are not published.
- Outcome
- The remortgage completed and the client used the £410,000 released to proceed with the second UK purchase, keeping the London rental. The source describes completion as quick but gives no timescale. This is a case-specific historical account, not evidence of current terms or a guarantee that another Japan-based applicant will qualify.
Case evidence, sources and limitations
Source: Clifton Private Finance, ‘Buy To Let Remortgage For UK Expat Based In Japan’. Clifton Private Finance is the arranging team named in the account. Clifton International publishes an attributed, adapted summary only and did not arrange this transaction. Figures are reported case facts, not independently audited data.
The source does not identify the lender, interest rate, fees, term, repayment basis or timescale, and none is implied here. The loan-to-value is derived from the reported £410,000 and approximate £1.3 million value. The image is illustrative, not the client’s property. Eligibility and terms require individual assessment; your property may be repossessed if you do not keep up repayments.
Case narrative updated . This is an editorial date, not the completion date.
- Clifton Private Finance — original Japan expat buy-to-let remortgage case
Original published account, including the reported £410,000 raised, the ~£1.3m mortgage-free London property, ~£2,500 monthly rent and JPY income.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£380,000 buy-to-let remortgage for UK expats in the US paid in dollars
£380,000 capital raised · Oxford buy-to-let valued at about £1.29m · US dollar income
FAQs
Questions on this case
- Can I get a UK buy-to-let mortgage while living in Japan?
- Yes. Some specialist lenders consider British expats based in Japan, subject to affordability, the property and how they assess the income. Lender choice is usually narrower than for UK-based borrowers.
- Do UK lenders accept Japanese yen income?
- Some do, although criteria vary and many mainstream lenders prefer sterling income. Any conversion adjustment is lender-specific, and yen income still carries exchange-rate risk against sterling.
- Can I remortgage a UK property from overseas?
- Often, yes. Expats can remortgage UK residential and buy-to-let properties while living abroad, subject to lender criteria for their country of residence and income.
- Can I release equity from a UK buy-to-let to buy another property?
- In many cases. In this case £410,000 was released from a mortgage-free London rental to fund the deposit on a second UK investment, without selling the existing property. Rental cover and affordability are assessed individually.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.