£1m+ development exit finance for an Essex residential scheme
Over £1,000,000 development exit facility · existing development loan refinanced · orderly unit sales
In short
How did an Essex developer refinance a development loan nearing expiry?
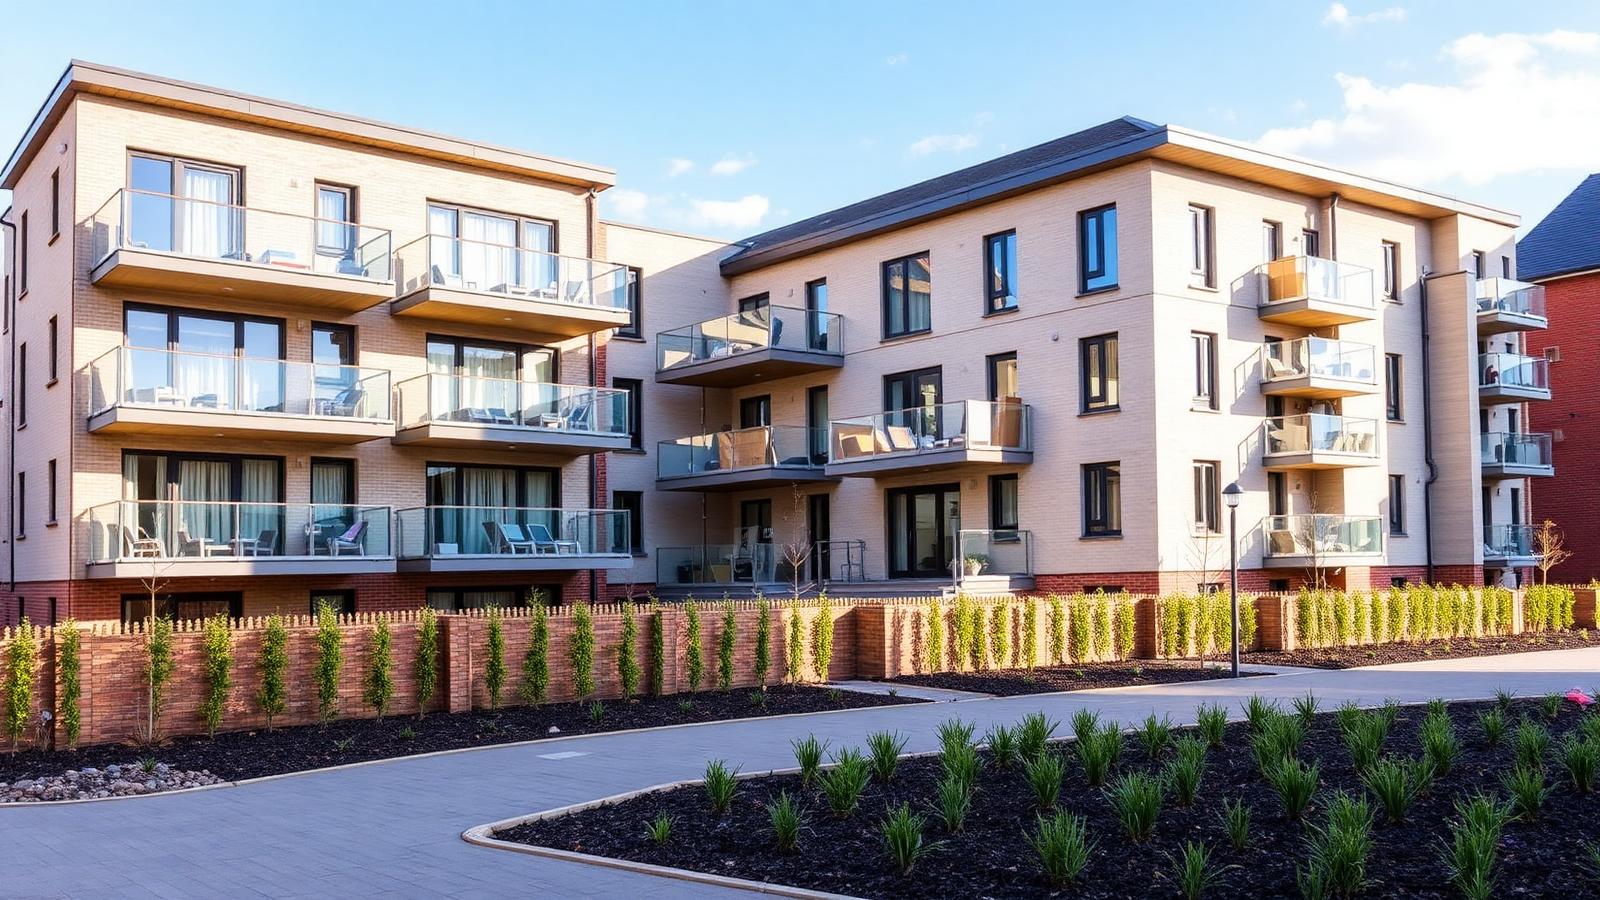
Clifton PF International arranged development exit finance of over £1 million for an Essex residential scheme approaching practical completion. The facility repaid the existing development lender before expiry, reduced reliance on higher-cost development funding and gave the developer time to market and sell the remaining units in an orderly way.
- Location: Essex. Finance type: Development exit finance for a residential scheme.
- Headline terms: Over £1,000,000 development exit facility · existing development loan refinanced · orderly unit sales.
- The developer had reached the latter stages of an Essex residential scheme and the original development finance facility was nearing expiry. The project was progressing well, but the developer wanted to avoid a forced-sale strategy that could erode profit margins, and needed breathing space to finish the final units and market them in an orderly way.
- With the pressure of an imminent facility expiry removed, the developer gained time to finalise the project, market the remaining units and achieve the sales strategy originally planned, with greater flexibility, improved cash-flow management and a clear pathway to a profitable exit. Every case is assessed individually; this outcome does not guarantee terms for another scheme.
- Loan amount
- Over £1,000,000
- Purpose
- Development exit finance
- Property type
- Residential development
- Location
- Essex
- Borrower
- Property developer
- Objective
- Refinance development facility and exit
- Challenge
- The developer had reached the latter stages of an Essex residential scheme and the original development finance facility was nearing expiry. The project was progressing well, but the developer wanted to avoid a forced-sale strategy that could erode profit margins, and needed breathing space to finish the final units and market them in an orderly way.
- Solution
- Drawing on our network of specialist development and commercial finance lenders, we identified a lender experienced in development exit finance for residential projects nearing completion. We worked with all parties to demonstrate the strength of the scheme, the remaining sales strategy and the underlying asset value, presenting a clear exit plan and detailed project information.
- Funding structure
- A development exit facility of over £1,000,000 repaid the existing development lender and moved the developer away from higher-cost development funding. The facility provided additional time to complete the remaining works, market the properties and execute the sales exit. Lender, rate and exact loan-to-value are not published.
- Outcome
- With the pressure of an imminent facility expiry removed, the developer gained time to finalise the project, market the remaining units and achieve the sales strategy originally planned, with greater flexibility, improved cash-flow management and a clear pathway to a profitable exit. Every case is assessed individually; this outcome does not guarantee terms for another scheme.
More UK case studies
Related transactions
£35,000 second-charge finance for a British couple relocating to France
£35,000 raised · Rugby property security · Normandy purchase

£1.2m buy-to-let remortgage for British expats living in Spain
£1,200,000 remortgage · Reading former home · residential mortgage and bridge repaid
£1.5m raised for a Birmingham commercial portfolio: Canada-based British expat
Reported £1.5m capital raised · £2.4m portfolio · share purchase
FAQs
Questions on this case
- Why did the Essex developer use development exit finance?
- The original development facility was nearing expiry while the final units were being completed and sold. Development exit finance repaid that lender and gave the developer time to sell without a forced-sale discount.
- How much was raised?
- A development exit facility of over £1,000,000 was arranged for the residential scheme.
More answers in our UK mortgage FAQs, covering standard mortgages, expat applications, foreign-currency income and bridging.
Ready to explore your options?
Speak to a UK property finance specialist.
A discreet, no-obligation conversation with a UK-based adviser who understands the full UK lending landscape — residential, bridging, development and commercial.