70% LTV holiday-home mortgage, Murcia
€750k purchase · 70% LTV · holiday home
In short
How was 70% LTV holiday-home mortgage, Murcia financed?
Clifton International helped facilitate this Spanish non-resident mortgage through a specialist partner for a Murcia holiday-home purchase — €750k purchase, 70% LTV, joint UK-resident applicants. A Spanish mortgage facility at 70% LTV against a €750,000 holiday home in the Murcia region, structured as a joint application by UK-resident borrowers.
- Location: Murcia, Spain. Finance type: Spanish non-resident mortgage.
- Headline terms: €750k purchase · 70% LTV · holiday home.
- A UK-resident couple wanted to buy a €750k residential property on an established golf resort in the Murcia region as a holiday home. As non-residents with two different income types — one salaried, one self-employed — the application needed to be presented so a Spanish lender could properly assess both income streams and modest existing credit commitments.
- The specialist Spanish mortgage partner secured the required financing, enabling the clients to proceed with the holiday-home purchase while retaining their financial and employment base in the United Kingdom.
Financing something comparable? A specialist will review your scenario and revert within one working day.
Start an enquiry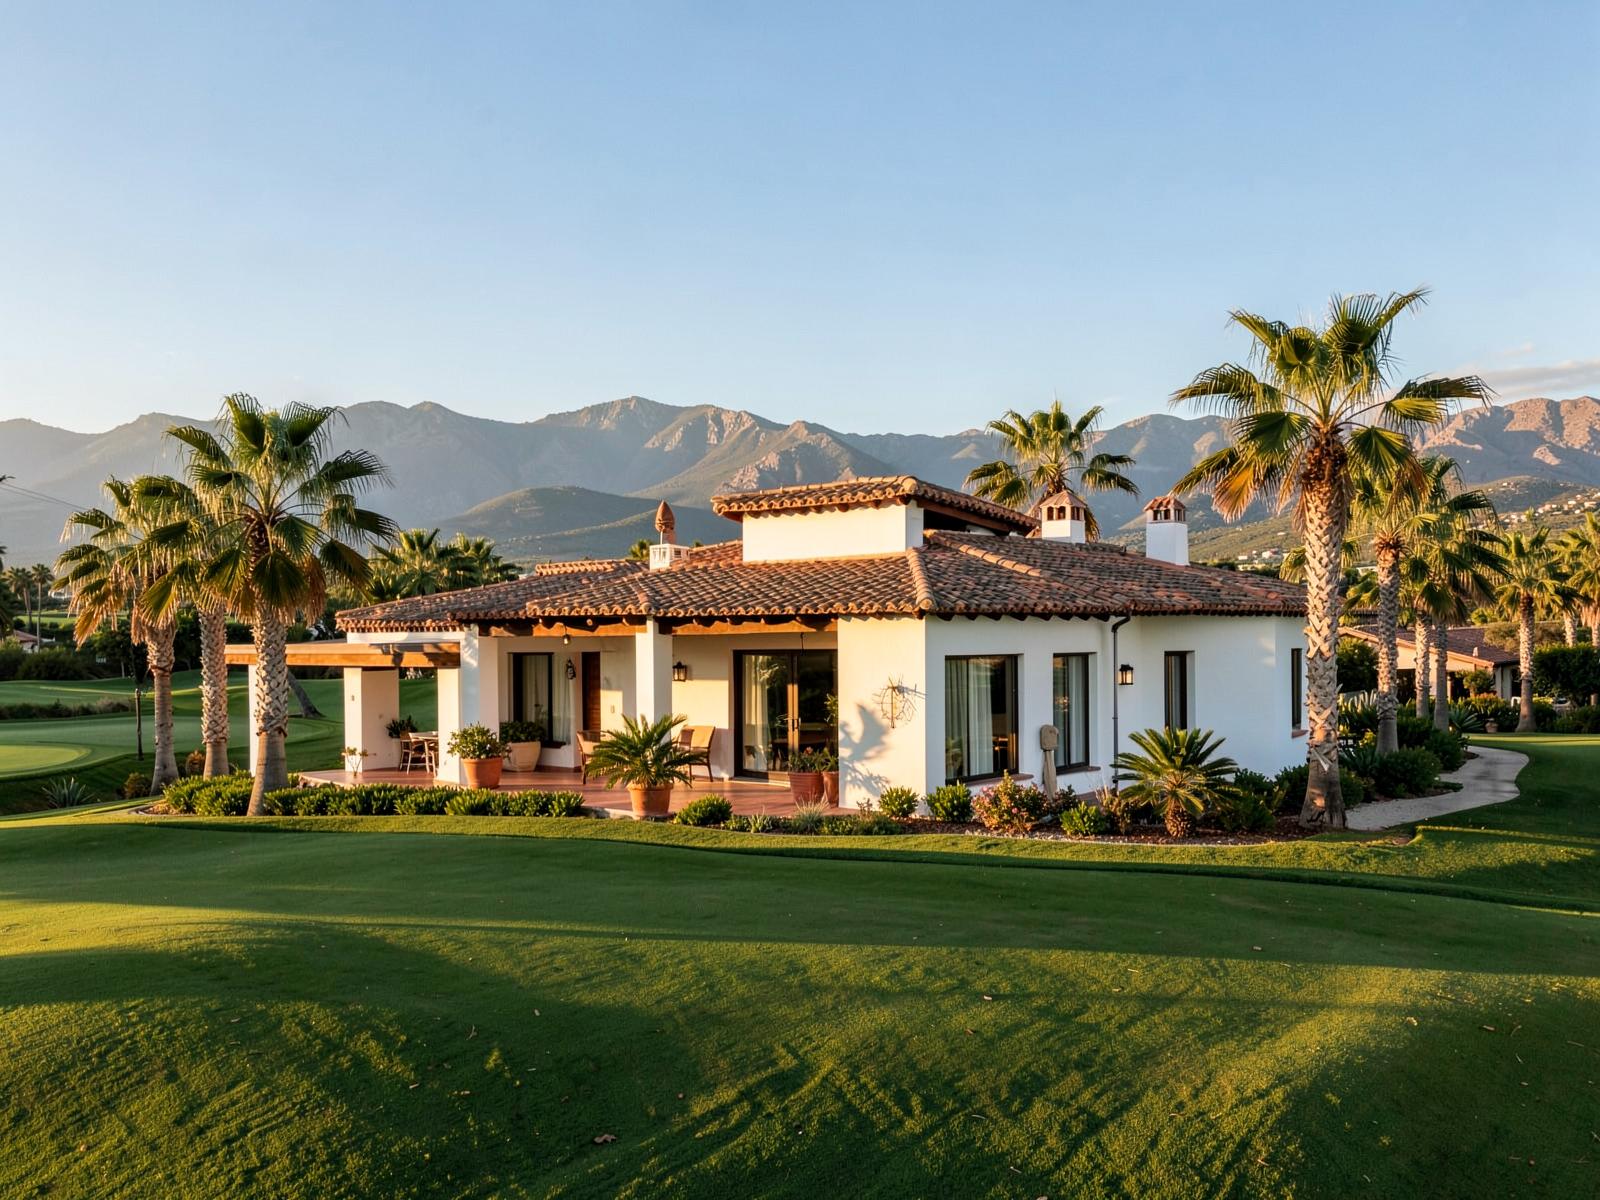
- Property value
- €750,000
- Loan to value
- 70%
- Clients
- UK residents, joint
- Purpose
- Holiday home
- Income
- Salaried + self-employed
- Location
- Murcia, Spain
Murcia holiday home mortgage, Costa Cálida
The Murcia region and Costa Cálida golf resorts attract UK buyers looking for a holiday home at lower price points than the Costa del Sol, which is the market this mortgage was arranged in.
- Challenge
- A UK-resident couple wanted to buy a €750k residential property on an established golf resort in the Murcia region as a holiday home. As non-residents with two different income types — one salaried, one self-employed — the application needed to be presented so a Spanish lender could properly assess both income streams and modest existing credit commitments.
- Solution
- Clifton introduced the clients to a specialist Spanish mortgage specialist experienced in placing cases for UK-based non-residents. The file evidenced two established income sources, stable salaried employment, a long and consistent self-employment history with documented business earnings, strong savings and a conservative 70% LTV.
- Funding structure
- A Spanish mortgage facility at 70% LTV against a €750,000 holiday home in the Murcia region, structured as a joint application by UK-resident borrowers.
- Outcome
- The specialist Spanish mortgage partner secured the required financing, enabling the clients to proceed with the holiday-home purchase while retaining their financial and employment base in the United Kingdom.
Client profile
The clients were a couple living and paying taxes in the United Kingdom, buying a Spanish holiday home on an established golf resort in the Murcia region.
- UK residents applying jointly
- Purpose: holiday home in the Murcia region
- Property within an established golf resort
- Introduced by a professional referral partner
Employment and income
The application benefited from two complementary income sources: one applicant held a stable, full-time salaried role in education with an established employment history, while the other was a long-established self-employed business owner in the property maintenance and services sector with several decades of continuous trading.
- Applicant 1: established full-time salaried employment in education
- Applicant 2: self-employed with decades of continuous trading
- Consistent, documented self-employed business earnings
- Complementary income streams strengthened the application
Deposit, commitments and affordability
Documented joint and personal savings with established financial institutions covered the deposit and purchase costs. Modest personal credit commitments and revolving credit were considered in the affordability assessment but remained comfortable relative to combined income, which supported the proposed mortgage with capacity to spare.
- Documented joint and personal savings
- Modest existing credit commitments
- Comfortable affordability on combined income
- Conservative 70% loan-to-value
Spanish mortgage for UK residents buying a holiday home
The clients intended to keep their home, employment and tax position in the United Kingdom, so this was a Spanish mortgage for UK residents rather than a relocation case. The proposed property would be used as a holiday home. The specialist partner therefore presented the application on a non-resident basis, supported by UK income records, business accounts, savings evidence and details of the applicants’ existing commitments.
Property and mortgage requirement
The €750,000 property was within an established golf resort in Murcia. A 70% loan-to-value mortgage left the clients responsible for the deposit and purchase costs from documented savings. The joint application combined a stable salary with a long self-employed trading record, giving the lender a fuller view of household affordability than either income source would have provided alone.
Why the application succeeded
A strong combined financial profile was matched with a lender suited to UK-based non-resident borrowers, and the documentation presented both income types clearly. This was important because a Spanish lender assessing overseas applicants needs to understand not only headline earnings but also how sustainable each source is, what debts remain and whether the applicants retain enough funds for the deposit and associated buying costs.
- Strong combined household income from two established sources
- Long-established self-employment with consistent earnings
- Strong documented savings and moderate existing debt
- Conservative LTV and a clear holiday-home purpose
- Well-prepared supporting documentation
- Lender selection suited to non-resident applicants
Enquire about a similar transaction
Prefilled with the context of this case study. A specialist will respond within one working day.
- 40+ lendersWhole-of-market panel
- 4–8 weeksTypical completion
- Rated ExcellentClient reviews
- No obligationFree initial review
More case studies
Related transactions

Ready to explore your options?
Speak to a Spanish property finance specialist.
A discreet, no-obligation conversation with a UK & Spain-focused specialist who understands both the UK and Spanish lending landscape.