Can German buyers get a mortgage in Spain?
Yes. German residents are among the strongest non-resident applicants in Spain, typically borrowing up to 70% of value over five to twenty-five years. Because income is earned in euros there is no currency haircut, and a well-documented file usually completes in eight to fourteen weeks.
- Lohnsteuerbescheinigung, tax assessments and payslips are the standard income evidence.
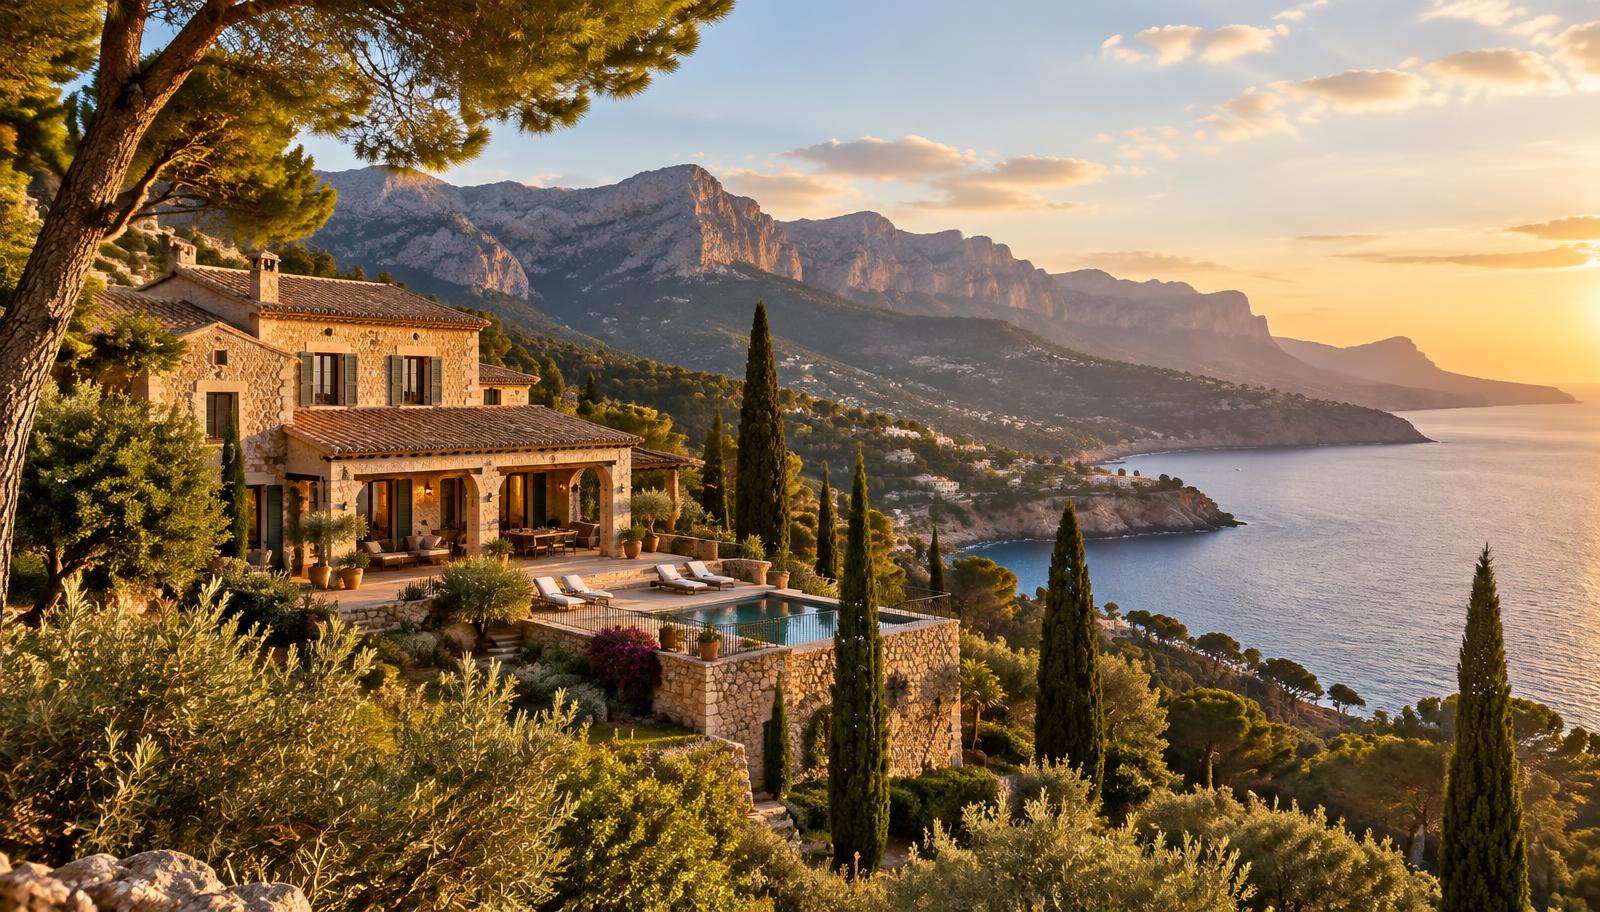
- Mallorca, the Costa Blanca and the Costa del Sol see the heaviest German demand.
- Fixed, variable and mixed rate structures are all available.
- On Mallorca, Balearic resale tax is progressive (8% up to €400,000, rising by band), so total costs are often 11–14% of price.
At a glance
Key facts
Figures reviewed:
- Typical LTV (German non-resident)
- 60–70%Of the lower of purchase price or tasación valuation.
- Indicative fixed rates
- Approx. 2.80% – 3.90% p.a.Indicative non-resident pricing from Clifton International's Spanish lender panel, reviewed 2 November 2026. Not a rate offer.
- Indicative mixed rates
- Approx. 2.50% – 3.40% p.a. initial period
- Variable margin
- 12-month Euribor + 0.90% – 1.75%
- Affordability test
- c.35% of gross incomeExisting German Baufinanzierung is included in total debt service.
- Balearic resale tax (ITP)
- 8% to 13%, progressive8% to €400k, 9% to €600k, 10% to €1m, 12% to €2m, 13% above. Reduced rates may apply to qualifying primary residences.
- Typical timeline
- 8–14 weeksSelf-employed or GmbH income may take longer. Where speed matters consider short term bridging finance.
- Non-resident income tax
- 19% IRNR (EU/EEA rate)
Indicative figures for guidance only, correct as at 2 November 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.
Methodology and assumptions
- Figures are compiled by Clifton International specialists from live lender term sheets, indicative quotes and completed transactions arranged over the preceding 12 months.
- Rates and costs are stated as ranges rather than a single number because pricing is set case-by-case on borrower profile, residency, asset type, location and loan-to-value.
- Timelines assume a complete document file from the outset; valuation, legal capacity and (in Spain) NIE and notary availability drive the critical path.
- Costs exclude any lender, broker or third-party fees not stated on the page, and exclude currency movement between agreement and drawdown.
- Figures are reviewed monthly and re-checked against lender pricing whenever a material market change occurs.
Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.
Contributor
- Called to the Bar, Lincoln's Inn
- Chartered Financial Planner
- Society of Trust & Estate Practitioners
Oliver is a co-founder and Director, called to the Bar at Lincoln's Inn, a Chartered Financial Planner and a member of the Society of Trust & Estate Practitioners.
Key takeaways
- EU residency and EUR income give German buyers access to the top of the non-resident LTV range — typically 60–70%.
- No currency risk on a euro loan means broader lender choice and no MCD currency-conversion consideration.
- SCHUFA is not used by Spanish lenders; expect payslip, tax and bank-statement led underwriting instead.
- Holiday-let licensing on Mallorca is tightly regulated — lenders check the licence status of the target property.
- Typical timelines are 8–14 weeks from fact-find to notary for prepared German files.
German buyers versus non-EU buyers in Spain
EU residency and euro income are the two factors that most widen the Spanish lender panel.
| Factor | German buyer | Non-EU buyer (US / GCC) |
|---|---|---|
| Typical LTV | 60–70% | 50–65% |
| Lender pool | Broad — most Spanish retail banks | Narrow — international desks only |
| Income currency | EUR, no discount | USD/AED, discounted 10–30% |
| Non-resident income tax (IRNR) | 19% (EU/EEA rate) | 24% |
| Typical timeline | 8–14 weeks | 8–14 weeks, often at the upper end |
Swipe the table sideways to see all columns.
Indicative figures only. Actual terms depend on borrower profile, asset and lender criteria.
How much can German buyers borrow?
Spanish lenders generally cap non-resident LTVs at 70% of the lower of purchase price or valuation. German applicants regularly reach that ceiling, subject to affordability, particularly with employed income from an established employer, civil-servant (Beamte) status, or established self-employment (Freiberufler / Selbstständig).
Total worldwide debt service is stress-tested to around 35% of gross monthly income. A German Baufinanzierung on your main home is included, but a long-term fixed rate at home often leaves capacity for a Spanish facility.
Rates this month
Spanish mortgage rates for non-residents
Euribor published:
12-month Euribor (September 2026)
3.247%
+0.293 on August 2026
Variable margin
0.90% – 1.75%
Over Euribor; panel reviewed 2 November 2026
Indicative variable rate
4.15% – 5.00%
Euribor + margin
Non-resident fixed
2.80% – 3.90%
10–25 year products; panel reviewed 2 November 2026
Worked example — a €750,000 Mallorca purchase
Euribor reference: September 2026, published 2 October 2026 (Banco de España / BOE). Lender margins reviewed: 2 November 2026. Purchase tax: Balearic resale ITP scale (Agència Tributària de les Illes Balears). Illustrative only, not an offer.
| Purchase price (resale) | €750,000 |
|---|---|
| Mortgage (70% LTV) | €525,000 |
| Deposit | €225,000 |
| Purchase tax (ITP, effective 8.7%) | €65,000 |
| Notary, registry, legal and lender costs (c.3%) | €22,500 |
| Total cash needed | €312,500 |
| Rate (Euribor 3.247% + 1.33% margin) | 4.58% variable |
| Monthly payment (25 years, capital and interest) | €2,941 |
Tax is calculated band by band: 8% on the first €400,000, 9% from €400,000 to €600,000 and 10% from €600,000 to €750,000. German buyers earn and borrow in euros, so no currency conversion applies. A lender may offer less than 70% depending on valuation, property type and affordability — rural fincas are often lower.
Try your own Mallorca figures
- Mortgage
- €525,000
- Deposit
- €225,000
- Balearic ITP (8.7%)
- €65,000
- Total cash needed
- €312,500
Monthly payment: €2,941 at 4.58% variable (approved Euribor + margin midpoint). Other costs assumed at 3%. Illustrative only, not an offer.
What documents will you need?
- Reisepass or Personalausweis, plus NIE application in progress.
- Last 3 months' Gehaltsabrechnungen and most recent Einkommensteuerbescheid.
- For self-employed: last 2–3 years of BWA, EÜR or GuV plus tax assessments.
- Last 6 months of Kontoauszüge (current, savings and brokerage).
- Existing Grundschuld / mortgage statement for your German home.
- SCHUFA-Selbstauskunft is helpful supporting evidence, though not scored by Spanish banks.
Sworn Spanish translation of statutory documents is standard.
Where German buyers buy in Spain
Mallorca. The island's south-west (Andratx, Santa Ponsa, Port d'Andratx), Palma and the north-east (Cala Ratjada, Alcúdia) have long-established German communities and direct flights from most German airports. Holiday-let (ETV) licences are strictly limited; lenders check licence status, and a property without an active licence is financed as a second home. See Mallorca mortgages.
Costa Blanca. Dénia, Jávea and Moraira attract German buyers seeking lower entry prices than the Balearics, with Valencia's 9% resale tax (11% above €1m). See Costa Blanca mortgages.
Costa del Sol. Marbella and Estepona draw higher-value German purchases, with Andalucía's 7% flat resale tax. See Costa del Sol mortgages.
Ibiza. Prime and seasonal-let demand under the same Balearic tax scale as Mallorca. See Ibiza mortgages.
The end-to-end process
- Week 1–2: Fact-find, EU-lender shortlist, indicative terms.
- Week 2–4: NIE, formal submission, initial underwriting.
- Week 4–7: Valuation (tasación) and credit committee approval.
- Week 7–10: FEIN/FiAE offer issued; 10-day cooling-off period.
- Week 10–14: Notary appointment and escritura pública.
Tax and structuring notes for German residents
General information, reviewed 16 October 2026. Your position depends on tax residence, not nationality — take advice from a Steuerberater and a Spanish tax adviser.
- Under the 2011 Germany–Spain double tax treaty, Spain generally has the first right to tax Spanish rental income and gains. If you are German tax resident, Germany may also tax that income and generally gives credit for Spanish tax; the credit may not remove all German tax. See the Federal Ministry of Finance Spain page.
- Non-resident owners file Spanish non-resident income tax (IRNR): 19% for EU/EEA residents on net rental income, and imputed income tax on a non-let second home.
- Spanish wealth tax (Impuesto sobre el Patrimonio) can apply to Spanish assets of non-residents; allowances vary by region and change often. The state solidarity tax on large fortunes may apply to net Spanish assets above €3 million.
- Spanish inheritance and gift tax may apply to Spanish property, and Germany may also tax the estate of a German resident; treaty relief is limited, so plan ownership early.
- Ownership via a German GmbH or Spanish SL is possible but narrows lender choice and rarely improves tax efficiency for pure holiday use.
Frequently asked
Questions from readers
Are German buyers treated as EU residents in Spain?
Yes. German applicants benefit from the most favourable non-resident LTV band in the Spanish market — typically 60–70%, higher than UK, US or Middle East buyers.
Does SCHUFA affect my Spanish mortgage application?
Spanish banks don't use SCHUFA. A clean SCHUFA-Selbstauskunft is useful supporting evidence, but underwriting relies on payslips, tax assessments and bank statements.
How much cash do I need for a €750,000 Mallorca purchase?
At 70% LTV the deposit is €225,000, Balearic resale tax is about €65,000 and other costs about €22,500 — around €312,500 in total. At this month's approved Euribor plus margin (4.58%), the 25-year payment is about €2,941 a month. Illustrative only.
What purchase tax applies on Mallorca?
Resale property in the Balearics pays progressive ITP: 8% up to €400,000, 9% to €600,000, 10% to €1 million, 12% to €2 million and 13% above. New builds pay 10% IVA plus stamp duty instead.
Can I finance a holiday-let property on Mallorca?
Yes, but the lender will check whether the property holds an active ETV licence. Without a licence the loan will be underwritten as a second-home purchase, not as an income-generating investment.
Is Spanish rental income taxed in Germany too?
If you are German tax resident, generally yes. Spain taxes it first under the 2011 treaty and Germany usually gives credit for Spanish tax, but the credit may not cancel all German tax. Take personal advice.
Where do German buyers buy in Spain?
Mallorca (Andratx, Palma, Santa Ponsa and the north-east coast) is the main German market, followed by the northern Costa Blanca (Dénia, Jávea, Moraira), the Costa del Sol and Ibiza.
Do I need a German co-signer or guarantor?
Generally no. Standalone applications from German employed and self-employed borrowers are the norm.
How long does the process take from offer to completion?
For a well-prepared German file, 8–14 weeks from fact-find to notary is realistic. Complex or corporate cases may take longer than 14 weeks.