
At a glance
Key facts
Figures reviewed:
- Typical LTV (Australian non-resident)
- 60–65%Of the lower of purchase price or tasación valuation.
- Indicative fixed rates
- Approx. 2.80% – 3.90% p.a.Indicative non-resident pricing from Clifton International's Spanish lender panel, reviewed July 2026. Not a rate offer.
- Indicative mixed rates
- Approx. 2.50% – 3.40% p.a. initial period
- Variable margin
- 12-month Euribor + 0.90% – 1.75%
- FX discount on AUD income
- 10–20%Applied before the affordability calculation.
- Affordability test
- c.35% of gross incomeIncludes Australian home loans, offset facilities and card limits.
- Acquisition costs
- 10–14% of priceITP in Andalucía is 7%; 10% IVA plus 1.2% AJD on new build.
- Non-resident income tax
- 24% IRNR (non-EU rate)
Indicative figures for guidance only, correct as at July 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.
Methodology and assumptions
- Figures are compiled by Clifton International specialists from live lender term sheets, indicative quotes and completed transactions arranged over the preceding 12 months.
- Rates and costs are stated as ranges rather than a single number because pricing is set case-by-case on borrower profile, residency, asset type, location and loan-to-value.
- Timelines assume a complete document file from the outset; valuation, legal capacity and (in Spain) NIE and notary availability drive the critical path.
- Costs exclude any lender, broker or third-party fees not stated on the page, and exclude currency movement between agreement and drawdown.
- Figures are reviewed at least quarterly and re-checked against lender pricing whenever a material market change occurs.
Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.
Can Australian residents get a mortgage in Spain?
Yes. Australian residents borrow in Spain as non-EU non-residents, typically at 60–65% of the lower of purchase price or valuation over terms up to 25 years. AUD income is normally discounted 10–20% for currency volatility, and a prepared file completes in eight to twelve weeks.
- 60–65% LTV is standard; private-bank routes can reach 65–70% on prime coastal assets.
- AUD salary, business and franked-dividend income are accepted when documented over two to three years.
- Non-EU status means IRNR is charged at 24% on Spanish rental and imputed income.
- Time zones and apostille logistics, not credit, are the usual cause of delay — build them into the timetable.
Key takeaways
- Australian residents typically secure 60–65% LTV; private-bank routes can reach 65–70% on prime assets.
- AUD income is usually discounted 10–20% before affordability is tested at around 35% of gross income.
- Non-EU status means 24% IRNR with no expense deduction on Spanish rental income.
- An SMSF is not a practical borrowing vehicle for Spanish property — lenders will not lend to it.
- Allow 8–12 weeks, and complete by apostilled power of attorney rather than a second flight.
Australian buyers versus EU-resident buyers in Spain
Tax residency outside the EU — not nationality — is what tightens LTVs and raises the non-resident tax rate.
| Factor | Australian buyer | EU-resident buyer |
|---|---|---|
| Typical LTV | 60–65% | 60–70% |
| Lender pool | International desks and selected retail banks | Broad — most Spanish retail banks |
| Income currency | AUD, discounted 10–20% | EUR, no discount |
| Non-resident income tax (IRNR) | 24%, no expense deduction | 19%, with deductible expenses |
| Typical timeline | 8–12 weeks | 6–8 weeks |
Swipe the table sideways to see all columns.
Indicative figures only. Actual terms depend on borrower profile, asset and lender criteria.
How much can Australian buyers borrow?
Spanish lenders classify borrowers by tax residency, not nationality. As non-EU non-residents, Australian applicants typically reach 60–65% of the lower of purchase price or valuation, over terms up to 25 years and generally to age 75.
Above roughly €1m the international private-bank channel opens up, offering 65–70%, interest-only options and sometimes better pricing than retail — normally alongside an assets-under-management relationship.
Affordability is stress-tested at around 35% of gross monthly income including all worldwide debt service: Australian home loans, investment-property debt, offset arrangements and card limits all count.
AUD income and currency treatment
The loan is euro-denominated while your income is in Australian dollars, so lenders discount the AUD figure — typically 10–20% — before running affordability. Salary, business income, franked dividends, trust distributions and account-based pensions are all acceptable when documented over two to three years.
Under the EU Mortgage Credit Directive you keep the right to convert loan currency if AUD/EUR moves materially against you. In practice most Australian buyers hedge the deposit and monthly payments with forward contracts rather than converting the loan.
Documents required
- Australian passport plus NIE (obtainable through the Spanish consulate or in Spain).
- Last three payslips, or two to three years of company financials for business owners.
- Last two years of ATO notices of assessment and individual tax returns.
- Twelve months of statements for every bank, broker and loan account.
- Equifax or illion credit report.
- Full source-of-funds file for the deposit, translated where required.
- Sworn Spanish translation and DFAT apostille of statutory documents.
Australian and Spanish tax interaction
- Spanish property income is taxed in Spain first; Australian residents then declare worldwide income to the ATO with foreign income tax offsets for Spanish tax paid.
- Spanish IRNR is charged at 24% for non-EU residents on rental income, with no deduction for mortgage interest or running costs.
- If the property is not let, an annual imputed income charge still applies via Modelo 210.
- Australian CGT applies on eventual disposal, alongside Spanish CGT and the 3% non-resident retention withheld at the notary.
- Regional Spanish wealth tax (Patrimonio) and the state solidarity levy can apply on higher-value holdings.
- Self-managed super funds cannot practically hold or borrow against Spanish property — Spanish lenders will not lend to an SMSF.
End-to-end process
- Week 1–2: Fact-find, indicative terms, lender shortlist.
- Week 2–4: NIE, full document pack, formal submission.
- Week 4–7: Tasación, source-of-funds review and credit approval.
- Week 7–9: FEIN/FiAE binding offer; 10-day cooling-off.
- Week 9–12: Notary, escritura pública, funds released, Land Registry filing.
What rate will an Australian buyer pay?
Australian applicants price on the standard Spanish non-resident grid. Indicative fixed pricing is 2.80% – 3.90% p.a. over 10–25 years, mixed products open at 2.50% – 3.40% p.a. for the initial fixed period, and variable products track 12-month Euribor plus 0.90% – 1.75%.
Unlike Australian home loans, Spanish fixed rates can run for the full 25-year term, there is no offset-account culture, and early-repayment compensation is capped by statute at low levels. Bundled insurance and a Spanish direct debit reduce the margin — compare total cost rather than the headline discount. Indicative non-resident pricing from Clifton International's Spanish lender panel, reviewed July 2026. Not a rate offer.
A Spanish case study
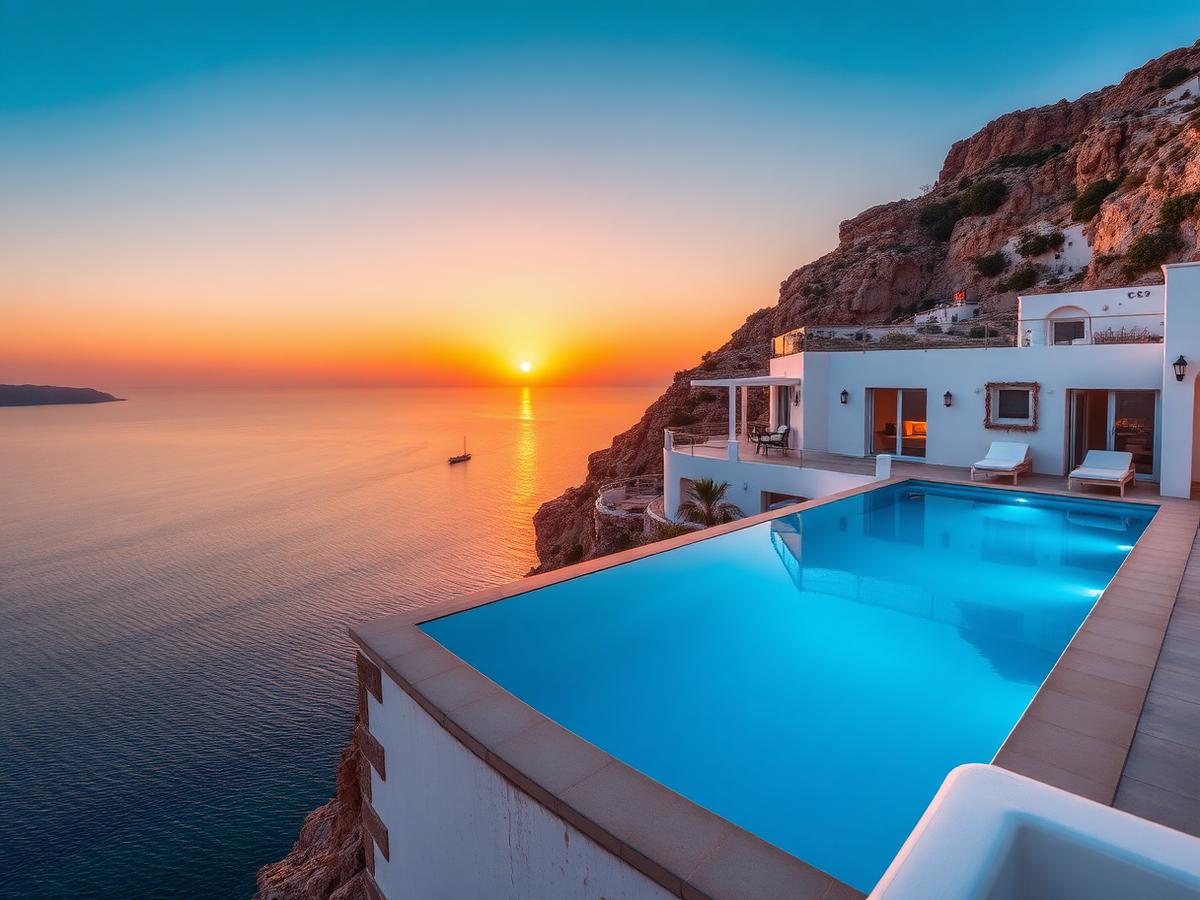
Luxury holiday home, Ibiza cliffside
€3.9m · 60% LTV · 20-year interest-only
A HNW UK client wanted to acquire a €6.5m cliffside villa for personal use and seasonal short-let, requiring a lender comfortable with rental income.
Our specialist partners structured a facility with a private bank willing to consider seasonal rental income alongside the client's UK income base.
- Holiday-home purchase completed on a euro-denominated non-resident facility
- Overseas income accepted after a currency discount
- Mirrors the route used by Australian buyers in the Balearics and Costa del Sol
Five mistakes that cost Australian buyers time
- Planning a single trip that covers viewing, NIE and notary. The statutory cooling-off period alone makes that impossible.
- Assuming an Australian bank will lend on Spanish security. They will not — finance is arranged in Spain or raised separately against Australian assets.
- Budgeting on Australian LVRs. Expect 60–65%, with total cash-in near 50% of the price once costs are included.
- Skipping the apostille. Australian documents need DFAT apostille and sworn Spanish translation before a notary will accept them.
- Assuming an SMSF can buy it. Spanish lenders do not lend to superannuation vehicles, and the compliance risk is significant.
Frequently asked
Questions from readers
Can Australians buy property in Spain?
Yes. There are no restrictions on Australian citizens owning Spanish residential property, and no foreign-buyer approval regime equivalent to Australia's FIRB.
How much deposit does an Australian buyer need?
Plan on 35–40% of the purchase price plus 10–14% in taxes and costs. On a €700,000 Costa del Sol apartment at 65% LTV that is roughly €245,000 deposit and €70,000–€98,000 of costs.
Is AUD income accepted by Spanish lenders?
Yes, by lenders with international desks. Expect a 10–20% haircut on the AUD figure before affordability is tested, to reflect currency volatility over the loan term.
Can my SMSF buy a Spanish property?
In practice, no. Spanish lenders will not lend to an Australian superannuation fund, and unencumbered SMSF ownership of foreign residential property raises significant compliance issues. Take Australian advice first.
Will my Australian home loan reduce my Spanish borrowing?
Yes. Spanish underwriters count worldwide debt service against the c.35% debt-to-income cap, including investment-property loans.
What rate will I pay as an Australian non-resident?
Indicative non-resident pricing is 2.80% – 3.90% p.a. fixed over 10–25 years, 2.50% – 3.40% p.a. for the initial period on a mixed product, or 12-month Euribor plus 0.90% – 1.75% on a variable. Indicative non-resident pricing from Clifton International's Spanish lender panel, reviewed July 2026. Not a rate offer.
How long does the process take?
8–12 weeks from application to completion for a well-prepared file. Document apostille and time-zone lag are the usual causes of drift.
Can I complete without flying to Spain?
Yes, and most Australian buyers do. A power of attorney signed before an Australian notary public and apostilled by DFAT lets your Spanish abogado sign the escritura for you.
Can I let the property short-term?
Yes, where the property holds a valid regional tourist licence. Andalucía, the Balearics and Catalonia each run their own registration regimes, and lenders underwrite licensed stock as investment property.
Do I need a Spanish bank account?
Yes. Mortgage payments, IBI, community fees and utilities are all collected by direct debit from a Spanish account, and lenders require one before completion.
Is interest-only available?
Rarely on retail non-resident terms. It is realistic through international private banks, generally above €1m and with an assets-under-management relationship.
Is bridging available to Australian buyers?
Yes. Short-term finance secured on the Spanish property is used where a purchase deadline precedes an Australian sale or share liquidation. Expect 0.7–0.9% per month to a maximum 65% LTV, plus an arrangement fee of 2%–5% dependent on project scenario.
Does buying give me residency in Spain?
No. Spain's Golden Visa route closed in 2025. Australians travel visa-free within Schengen short-stay limits; longer stays need a separate visa such as the non-lucrative visa.
Should I buy personally or through a company?
Personal ownership keeps the widest lender panel and the simplest tax position. Australian companies and family trusts narrow the panel sharply and require full UBO disclosure — take advice in both countries first.