€5.1m Madrid refinance and liquidity release
€5.1m · ~47.7% LTV · 13.5% p.a.
In short
How was €5.1m Madrid refinance and liquidity release financed?
Clifton International arranged spanish refinance & capital raise for this Central Madrid transaction — €5.1m, ~47.7% LTV, 13.5% p.a. €5,101,902 maximum principal, mortgage-backed credit line at 13.50% fixed, ~47.7% LTV, 12-month term renewable by 6, first-ranking mortgage plus sale mandate.
- Location: Central Madrid. Finance type: Spanish refinance & capital raise.
- Headline terms: €5.1m · ~47.7% LTV · 13.5% p.a..
- A private owner of a €10.7m residential property in a prime central Madrid district, already mortgaged with a Spanish bank at €1.6m, wanted to refinance that debt and release substantial further liquidity for professional investment — without exceeding a conservative loan-to-value or losing flexibility on how the facility would be repaid.
- The existing Spanish bank mortgage was repaid in full and the released liquidity was deployed into the client's professional investment strategy, with the conservative LTV preserving flexibility for a future bank refinance or sale exit.
Financing something comparable? A specialist will review your scenario and revert within one working day.
Start an enquiry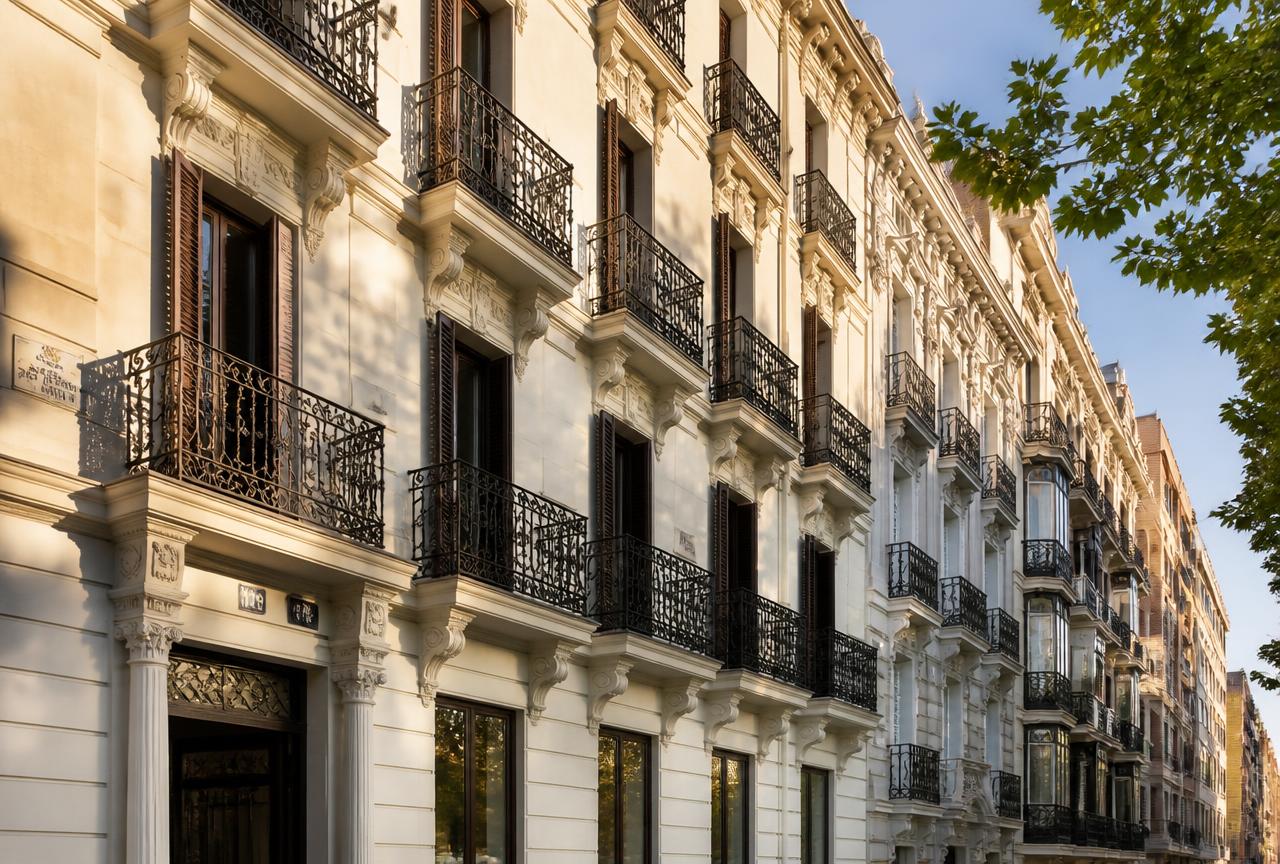
- Appraised value
- €10,700,000
- Existing mortgage
- €1,600,000
- Facility
- €5,101,902
- Maximum LTV
- ≈47.7%
- Interest rate
- 13.50% p.a.
- Outcome
- Completed
Refinance and capital raise in central Madrid
Prime central Madrid homes support conservative loan-to-values, which is what allowed an existing bank mortgage to be repaid and further liquidity released.
- Challenge
- A private owner of a €10.7m residential property in a prime central Madrid district, already mortgaged with a Spanish bank at €1.6m, wanted to refinance that debt and release substantial further liquidity for professional investment — without exceeding a conservative loan-to-value or losing flexibility on how the facility would be repaid.
- Solution
- A mortgage-secured credit line was structured and negotiated with a specialist private lending platform, sized to repay the existing mortgage and fund the investment requirement in full, with a multi-layered exit agreed upfront: sale of the asset, bank refinancing or other means. Terms were issued and the facility completed roughly a month after the initial approach.
- Funding structure
- €5,101,902 maximum principal, mortgage-backed credit line at 13.50% fixed, ~47.7% LTV, 12-month term renewable by 6, first-ranking mortgage plus sale mandate.
- Outcome
- The existing Spanish bank mortgage was repaid in full and the released liquidity was deployed into the client's professional investment strategy, with the conservative LTV preserving flexibility for a future bank refinance or sale exit.
Property owner’s objective
The client owned a prime central Madrid residence appraised at €10.7m with an existing €1.6m Spanish bank mortgage. The objective was to repay that debt and release additional liquidity for professional investment without pushing leverage to a level that removed future refinancing or sale options.
Refinance and capital-release terms
A mortgage-backed credit line of up to €5,101,902 was agreed, equal to approximately 47.7% of the appraised value. The loan carried a fixed rate of 13.50%, a 12-month term renewable by six months, a first-ranking mortgage and a sale mandate. Part of the advance repaid the existing mortgage; the balance funded the investment requirement.
- €10.7m appraised residential property
- €1.6m existing bank mortgage repaid
- €5,101,902 maximum principal
- Approximately 47.7% LTV
Flexible exit planning
The specialist private lending platform agreed more than one potential repayment route: sale of the asset, subsequent bank refinancing or repayment from other means. Defining these alternatives before completion gave the lender a clear exit while allowing the owner to retain flexibility over the property and investment strategy.
Completed outcome
Terms were issued and the facility completed roughly one month after the initial approach. The existing mortgage was discharged in full and the additional liquidity was deployed for professional investment. Conservative leverage preserved the possibility of returning to bank finance or selling the Madrid property later.
Enquire about a similar transaction
Prefilled with the context of this case study. A specialist will respond within one working day.
- 40+ lendersWhole-of-market panel
- 4–8 weeksTypical completion
- Rated ExcellentClient reviews
- No obligationFree initial review
More case studies
Related transactions
70% LTV non-resident mortgage, Estepona
€1.6m purchase · 70% LTV · primary residence
70% LTV holiday-home mortgage, Murcia
€750k purchase · 70% LTV · holiday home

€1.5M villa refurb, Marbella
€3.24m · 60% LTV · interest-only
Ready to explore your options?
Speak to a Spanish property finance specialist.
A discreet, no-obligation conversation with a UK & Spain-focused specialist who understands both the UK and Spanish lending landscape.