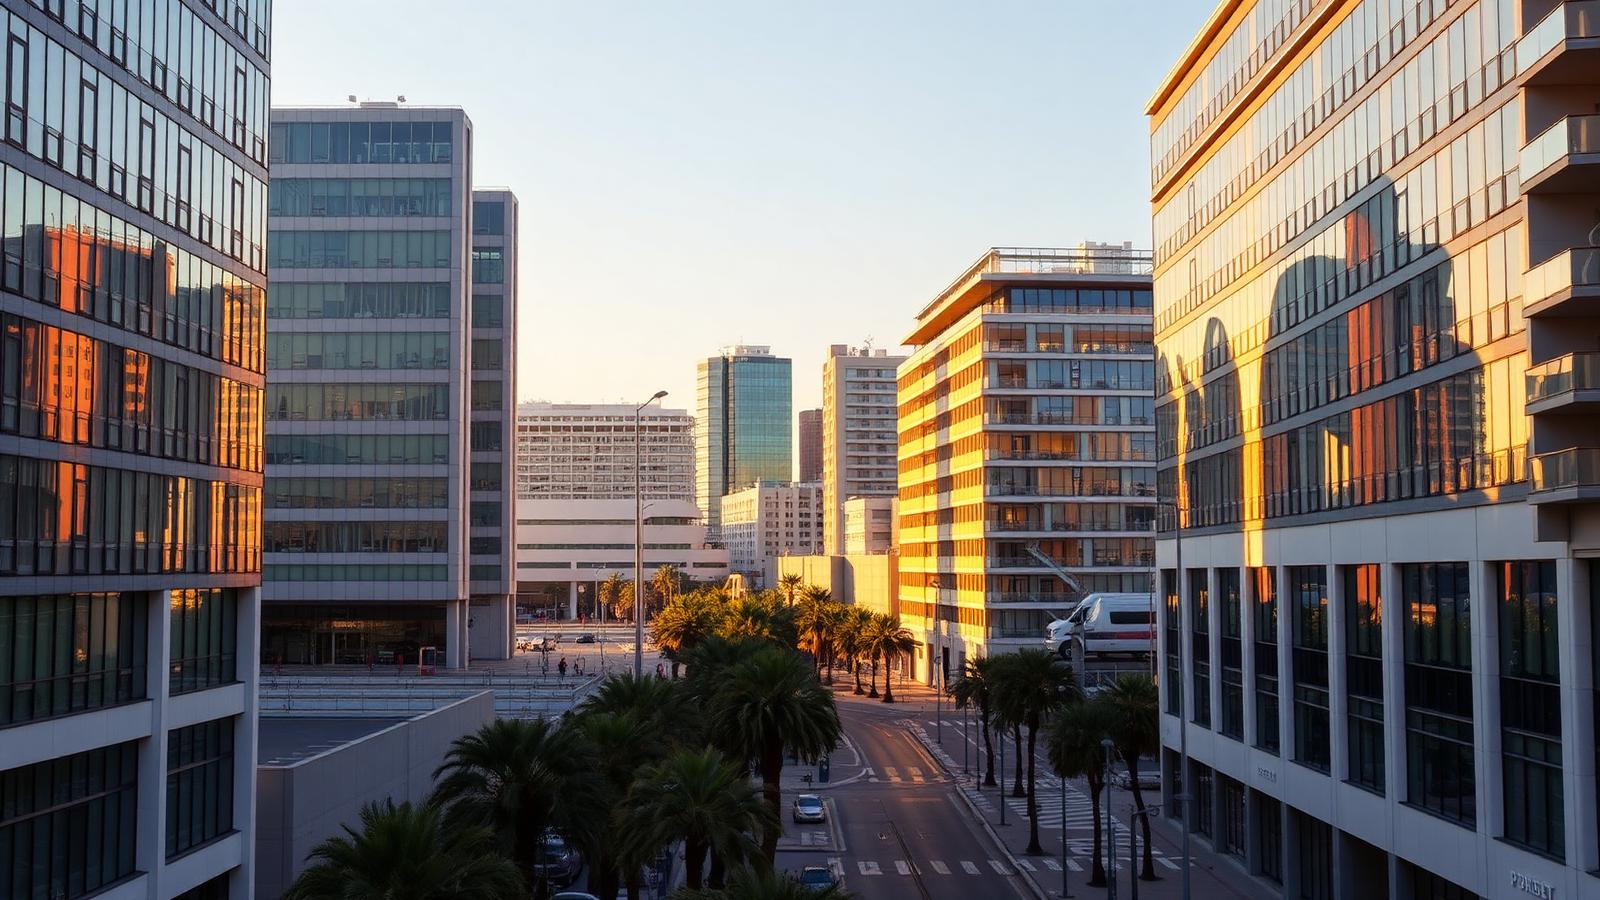
Senior investment debt for logistics and distribution assets along the port and A-3 corridor, let office stock in the city, high-street and district retail, and hotel and mixed-use buildings across Valencia.
Speak to a Valencia commercial property finance specialist.
Logistics, office, retail and hospitality debt across Valencia and the wider Comunidad Valenciana. A specialist will review the asset and revert within one working day.
Step 1 of 2
40+ lendersWhole-of-market panel
4–8 weeksTypical completion
Rated ExcellentClient reviews
No obligationFree initial review
Last updated Reviewed by our Clifton International finance team.
In short
How does commercial property finance work in Valencia?
Valencia commercial finance funds logistics, offices, retail and hotel assets, typically at 50–65% loan-to-value over five to fifteen years, priced over Euribor. Lenders underwrite rental income, tenant covenant and asset quality rather than the borrower's personal earnings or country of residence.
Port and A-3 logistics stock is among the most actively financed asset class.
Investment, owner-occupier and repositioning strategies are all supported.
SL, SPV and international corporate borrowers are standard.
Bridging can complete quickly, then refinance onto a term commercial loan.
At a glance
Key facts
Figures reviewed:
Loan-to-value
Up to 60%
Facility size
€2m – €50m+
Term
3 – 15 years
Basis
Interest-only or amortising
Borrower
Spanish SL or corporate
Indicative pricing
From 0.70% per month (bridging) / from 3.5% p.a. (term)Priced to profile, LTV, asset and lender. Live pricing confirmed on enquiry.
Typical set-up costs
10% – 12% of purchase price (taxes, notary, registry, legals)Purchase costs in Spain are payable in addition to your deposit.
Typical timeline to drawdown
4 – 8 weeks (bridging faster where required)Assumes a complete file; valuation and legal capacity drive the critical path. Where speed is required consider short term bridging finance to secure the property.
Adviser response time
Within one working day
Indicative figures for guidance only, correct as at July 2026. Rates, costs and timelines vary by lender, borrower profile, asset and jurisdiction, and are not an offer of finance. How we derive these figures.
Methodology and assumptions
Figures are compiled by Clifton International specialists from live lender term sheets, indicative quotes and completed transactions arranged over the preceding 12 months.
Rates and costs are stated as ranges rather than a single number because pricing is set case-by-case on borrower profile, residency, asset type, location and loan-to-value.
Timelines assume a complete document file from the outset; valuation, legal capacity and (in Spain) NIE and notary availability drive the critical path.
Costs exclude any lender, broker or third-party fees not stated on the page, and exclude currency movement between agreement and drawdown.
Figures are reviewed at least quarterly and re-checked against lender pricing whenever a material market change occurs.
Last reviewed . Read the full Key facts methodology, or speak to our team for a quote based on your circumstances.
Pricing reference — Valencia
12-month Euribor
2.954%
Monthly average for
0.78 points higher than September 2025 (2.172%)
Commercial margin
+1.75% – 3.25%
The margin added over Euribor on investment debt, driven by tenant covenant, unexpired lease term and sector.
Implied all-in rate
4.70% – 6.20%
Euribor plus margin, before hedging costs. Illustrative, not an offer of finance.
Minimum cover (DSCR)
1.30x
Net rental income divided by annual debt service. Cover, not loan-to-value, usually sets the facility size.
Official monthly Euribor average published by the Banco de España — official mortgage market reference rates, published in the Boletín Oficial del Estado. Commercial margins and cover ratios on this page were last reviewed by our Spanish finance team in July 2026. The monthly average changes once a month; pricing on any individual asset depends on sector, tenant covenant, unexpired lease term, loan-to-value and borrower structure.
Debt-service cover — Valencia
How much can this asset borrow?
Commercial facilities are sized on debt-service cover ratio (DSCR) — net rental income divided by annual debt service — and then capped by loan-to-value. Enter the asset's figures to see which of the two constraints sets the facility.
Indicative maximum facility
€2,400,000
Set by the 60% loan-to-value cap — cover would support more debt.
Illustrative only and not an offer of finance. Defaults use 12-month Euribor of 2.954% (August 2026) plus a mid commercial margin, and a 1.30x minimum cover ratio, reviewed July 2026. Lenders test cover at a stressed rate and may apply sector-specific minimums.
Rates and hub guidance — Valencia
Where the pricing on this page comes from, and what sits above it.
Logistics and distribution along the port and A-3 corridor, let office stock in the city centre and Benimaclet business district, high-street retail, and hotel and aparthotel assets serving the city's growing visitor market.
Typically 50–60% of value. Long unexpired lease terms and institutional tenant covenants support the upper end; short-income, vacant or value-add stock is sized more conservatively.
Yes. The port of Valencia and the A-3 corridor are among Spain's most active logistics markets, and lenders will fund single-let and multi-let warehousing against lease length and tenant covenant.
Yes — SL and SPV ownership is standard for Valencia investment stock, with parent-company or sponsor guarantees where the borrowing vehicle is newly formed.
Yes. A short-term bridge can complete a Valencia acquisition in weeks and then be refinanced onto an investment facility once valuations, leases and trading information are fully packaged.
DSCR is net operating income divided by annual debt service. Take gross rent, deduct non-recoverable costs such as management, insurance, IBI and a maintenance allowance to get net operating income, then divide by the interest and capital payable over twelve months. Net income of €260,000 against debt service of €200,000 gives a DSCR of 1.30x.
A minimum of 1.30x on standard investment stock is the usual test. Hotels, leisure and other trading assets are typically held to 1.40x–1.50x because income is operational rather than contracted, while long-let assets with an institutional covenant can be accepted closer to 1.20x.
Lenders test at a stressed rate, not the pay rate. On a floating facility priced at around 5.45% all-in, expect a stress of one to two points above that, or a floor rate set by the credit committee. Hedging the loan with a cap or swap usually allows the test to be run closer to the hedged rate.
Whichever is lower. The lender sizes the debt that net income can service at the minimum cover ratio, then caps that figure at the loan-to-value limit. On a high-yielding asset the LTV cap usually binds; on a prime, low-yielding asset cover binds and the resulting leverage sits well below the headline LTV.
Signed leases with unexpired terms, a tenancy schedule, the last two to three years of certified accounts or trading figures for operational assets, a current rent roll, evidence of arrears, and a service-charge and non-recoverable cost breakdown. A RICS-equivalent valuation confirms the market rent underpinning the calculation.
Local coverage
Where we lend in and around Valencia
Eixample, El Carmen, Ruzafa, Patacona and the Valencia coast. We also arrange property finance across the neighbouring areas below — one adviser, one conversation, whichever location you buy in.
Not listed? We cover all of mainland Spain, the Balearics and the Canaries — tell us the town and we will confirm lender appetite.
Also in Valencia
Building or repositioning an asset in Valencia?
Schemes are funded on development terms while works run, then refinanced onto commercial investment debt once the asset is complete and income-producing.
Senior development debt for Valencia schemes — historic-core conversions, new-build apartments and coastal villa clusters.
Speak to a Valencia commercial property finance specialist.
Logistics, office, retail and hospitality debt across Valencia and the wider Comunidad Valenciana. A specialist will review the asset and revert within one working day.